Lamar Heads Into Third Quarter With A Raised Outlook And A More Skeptical Market
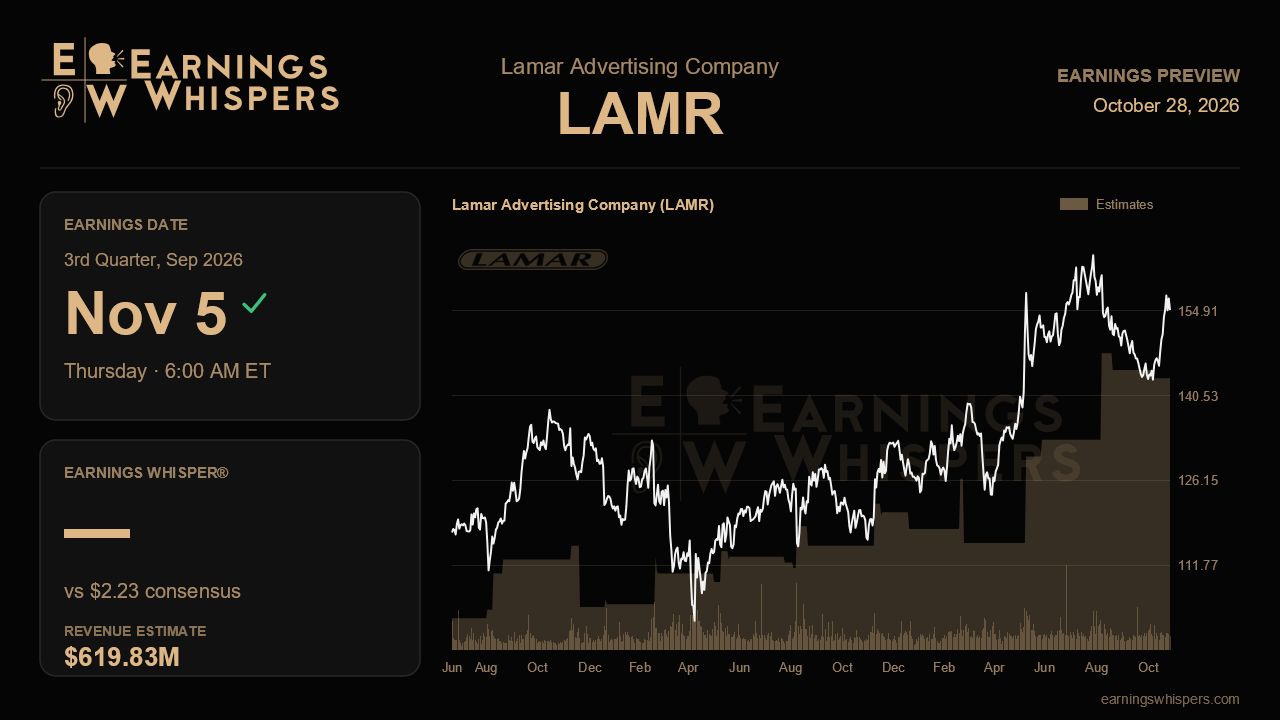
Lamar Advertising enters its third-quarter report with an unusual mismatch. Management has spent three straight calls describing a business that keeps getting better, with demand accelerating, margins climbing and a fresh argument that advertisers are migrating to billboards from radio, print, local TV and fraud-prone digital channels. It backed that up by lifting full-year funds from operations guidance to $8.75 to $8.90 per share. Yet the stock has slipped about 2% since the last report while the S&P 500 was essentially flat, and sentiment has turned noticeably more bearish. The release before the open on November 5 has to show the optimism is showing up in the numbers.
The Street is looking for per-share earnings of $2.23 on revenue of about $619.8 million. That implies revenue growth near 5.9% from $585.5 million a year ago, a meaningful step up from the roughly 3% to 4% acquisition-adjusted growth Lamar was posting through late 2025 and early 2026. Earnings are expected to rise only about 1.4%, though, which leaves a wide gap between top-line momentum and bottom-line conversion. Part of that is a tough comparison, since last year's third quarter ran at roughly a 48% EBITDA margin with little room to expand. Healthcare costs, which management flagged as adding about half a point to operating expenses, are another persistent drag. If revenue lands where expected but earnings barely move, it will raise questions about how much operating leverage this business really has.
The guidance comparison is striking. The consensus full-year FFO estimate of $8.41 sits below even the low end of management's raised range. That may partly reflect estimates that have not caught up, but it also suggests analysts are not fully crediting the company's outlook. A quarter that keeps Lamar on pace for the upper half of $8.75 to $8.90 would close that gap. Anything that forces management to lean on the bottom of the range would play into the skeptics' hands.
Operationally, the details matter more than the headline beat. Political spending has repeatedly come in ahead of the 2024 presidential cycle, an unusual feat in a midterm year, and the third quarter is when that spending should build. World Cup bookings of $3 million to $4 million add a modest lift. The more durable test is national and programmatic revenue. National grew 5.8% in the first quarter and programmatic about 25%. Continued strength there, plus any evidence that AI and technology-services advertisers are becoming a real category, would support the share-shift story. A slowdown in national, or growth that depends mostly on political dollars, would make the acceleration look cyclical.
Margins are the other swing factor. Management still targets a record full-year EBITDA margin of roughly 47.7%, at least a point above 2025. But it quietly pushed its 48% goal to 2027 or 2028 after pausing the second phase of its enterprise software rollout. This quarter should show whether expansion is still coming from organic pricing and occupancy or whether it is stalling. Commentary on acquisitions also deserves attention, since management said larger deals now draw more bidders as Clear Channel's balance sheet improves.
The stock sits around $155, comfortably above its 200-day moving average near $144 and in the upper half of its post-earnings range, though about 5% shy of the $163.94 high. That is not a stock pricing in disaster, but it is not pricing in perfection either. The central question is whether Lamar's acceleration is broad and repeatable or a well-timed burst of political and event spending. If national demand, pricing and margin progress all hold up alongside political, the raised guidance looks conservative and the cautious mood looks misplaced. If political carries the quarter on its own, the market's caution will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-07 | |
| Sep-21 | |
| Sep-15 | |
| Sep-01 | |
| Aug-13 | |
| Aug-06 | |
| Aug-06 | |
| Jul-10 | |
| Jul-06 | |
| May-22 | |
| May-18 | |
| May-14 | |
| May-08 | |
| May-07 |
