Kimberly-Clark Must Show China Diaper Slump And Destocking Were Temporary After Guidance Cut
Kimberly-Clark heads into its third-quarter report with a credibility question rather than a growth story. Three months ago, management trimmed its full-year outlook after a string of shocks hit at once: a social-media-driven safety scare that hammered its China diaper business, a fire at a Los Angeles distribution center, and an unexpected inventory cut by a North American adult-care customer. The company argued that most of these blows were one-off events layered on top of a durable base business. This report is the first real chance to test that claim.
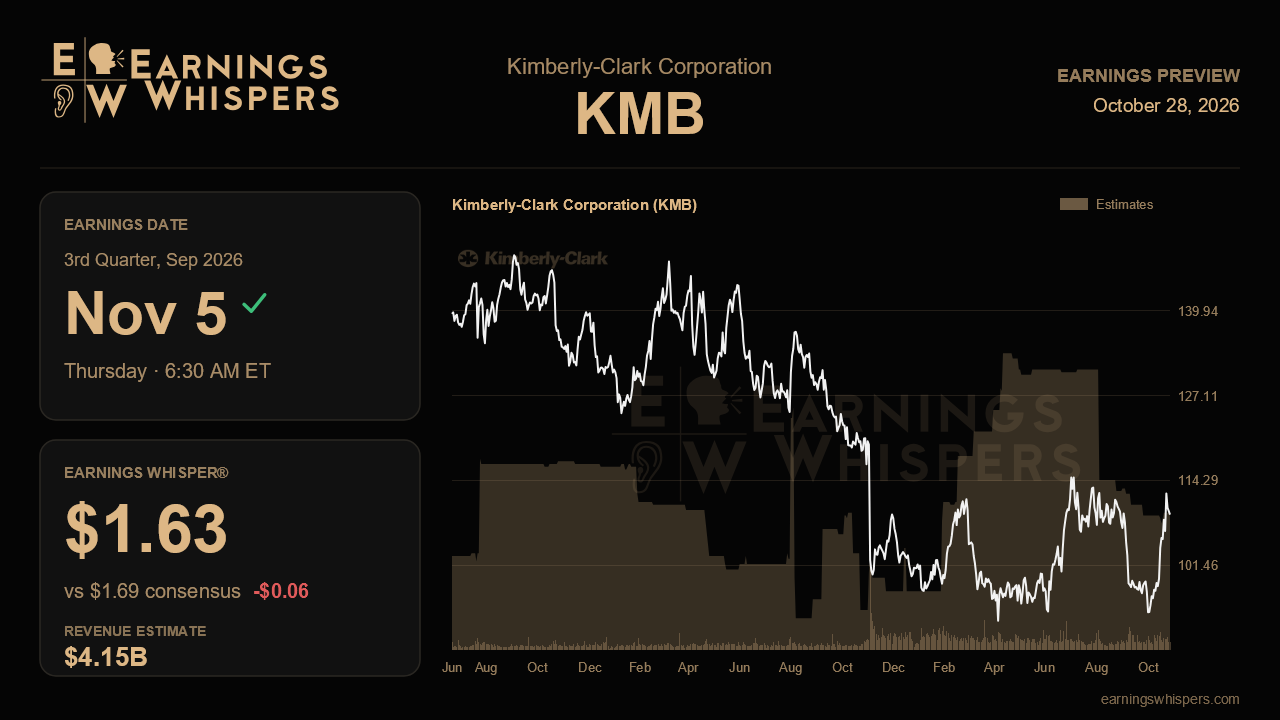
The Street is braced for a soft quarter. Consensus calls for earnings of $1.69 per share on revenue of about $4.15 billion. That implies sales flat with the year-ago period and a 7.1% decline in earnings from $1.82. The Earnings Whisper sits lower at $1.63, a gap of six cents that suggests some investors expect the China drag and cost pressures to bite harder than published estimates assume. Last quarter's $1.80 also got a lift from a $45 million U.S. tariff refund, so a sequential step down should not by itself be read as deterioration.
China is the biggest swing factor. Management estimated the disruption would cost roughly 200 basis points of top-line growth in the second half, along with about $70 million in operating profit and around 16 cents of EPS, and said it had not yet seen a turn. Any sign that sell-through is stabilizing would support the idea that this was a sharp but temporary hit. Continued weakness, or a larger estimated drag, would cast doubt on the second-half math and on the 2027 framework that management has already put on hold.
North America is the quieter but arguably more important test. Weighted category growth there slowed to 1.9% from 3.7% the prior quarter, management flagged strain among lower-income shoppers, and competitors are pushing harder on promotions alongside new low-cost diaper entrants. The company's defense rests on its streak of ten straight quarters of positive volume and mix and on holding or gaining share in about 70% of its North American sales. If volume and mix stay positive and the adult-care destocking does not repeat, the transitory narrative holds. If price concessions start to eat into volume gains, the category slowdown begins to look structural.
Margins should be the company's stronger suit. Gross productivity reached 6.4% last quarter, and management said tariff refunds plus mitigation would fully offset about $150 million of second-half inflation, much of it tied to Middle East-related input costs. Holding price net of cost close to neutral would be meaningful validation. Updates on Canview integration, where synergy planning was described as running ahead of plan with the close pulled forward, and early progress on the Suzano joint venture and alternative fiber program, offer longer-term support but are unlikely to drive this quarter's numbers.
Sentiment has warmed noticeably, swinging from modestly bearish before the last report to moderately bullish now, even though the stock has essentially gone nowhere since the guidance cut and trailed the S&P 500 by about 1.3 percentage points. At $109.10, shares sit well above their 200-day average of $102.82 and have recovered from post-earnings lows near $94, trading in the upper portion of their range and a little more than 3% below the $112.70 high. That rebound suggests investors are already giving management some benefit of the doubt.
The central issue is whether the guidance cut was a reset or the start of a slide. A reaffirmed lowered outlook, stabilizing China trends and positive North American volume would keep the story of strong execution weathering temporary shocks intact. Another cut would make it hard to blame the setbacks on bad luck alone.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 |
Kimberly-Clark Forecasts Quarterly Sales Decline Following Social-Media Firestorm in China
KMB
The Wall Street Journal
|
| Oct-15 | |
| Oct-15 | |
| Oct-13 |
Kimberly-Clark, Kenvue Win Conditional EU Approval for $40 Billion Tie-Up
KMB
The Wall Street Journal
|
| Oct-13 | |
| Oct-10 | |
| Oct-06 | |
| Oct-03 | |
| Oct-02 |
