Kimberly-Clark Matches Expectations As Kenvue Close And Bigger Synergy Talk Overshadow Another Soft Standalone Quarter
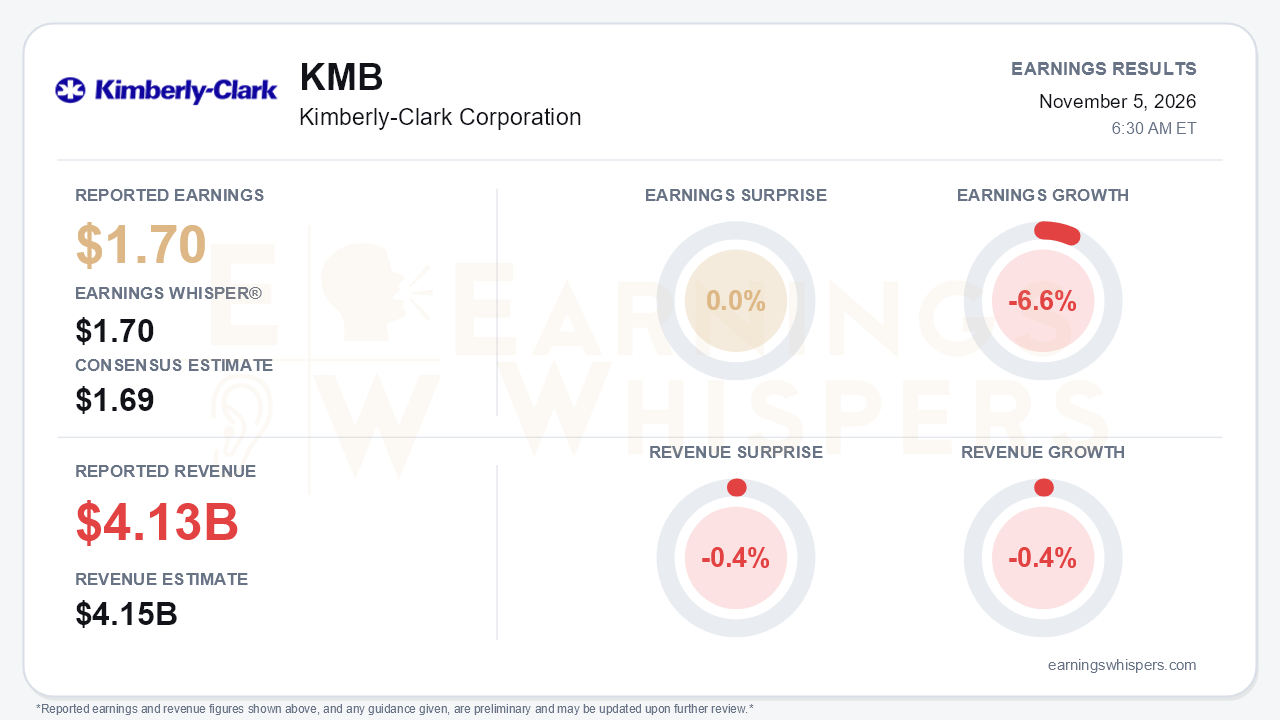
Kimberly-Clark delivered a quarter that was exactly as advertised, and that is part of the problem. The company earned $1.70 per share in the September quarter, a penny above the $1.69 consensus and precisely in line with the $1.70 Earnings Whisper number. Revenue of $4.134 billion came in 0.4% below the $4.15 billion consensus. Earnings fell 6.6% year over year, and revenue slipped 0.4%. There was no upside surprise to lean on, and the standalone business is still shrinking its profit base. The central tension is that management spent the call talking about a much larger future company, Kimberly-Clark plus Kenvue, while the legacy business continued to underdeliver against the plan it set at the start of the year.
The quality of the quarter deserves scrutiny. The press release itself offered no financial detail and simply pointed investors to supplemental materials. The call, however, made clear that full-year guidance was only reaffirmed, not raised, after being cut in the second quarter for China disruption and retailer destocking. The first-quarter vision of 70-80 basis points of gross and operating margin expansion and a second-half acceleration has not materialized. Pricing is the clearest crack. Total-company price is down about 70 basis points year to date and North America is down about 80 basis points. Management now expects roughly flat pricing for the year, a retreat from the low-single-digit North America increases flagged last quarter. Inflation keeps creeping higher. Second-half gross inflation is now estimated at about $200 million, up from roughly $150 million in August, and the full-year figure is about $250 million, driven by a spike in North America spot freight.
North America absorbed most of the damage. Retailer inventory reductions cost about 130 basis points in the quarter. A major new product launch was postponed because of quality issues on a new manufacturing asset, and the loss of a club diaper account cost roughly another point. Share has been weaker for two quarters. Productivity remains a genuine offset, with gross productivity of 6.1% year to date and 5.8% in the third quarter. Tissue gained 20 basis points of share for a third straight strong quarter. China also looks steadier now that the regulator SAMR has publicly confirmed Huggies safety and demand has stabilized to slightly improved.
The forward narrative is where management's tone clearly improved. The Kenvue acquisition closed this week, with the new organization and operating model live from day one. Kenvue posted roughly 3% organic growth in the quarter, and its internal scorecard has moved from about 100% red a year ago to about 70% green. Zyrtec, Nicorette, Rogaine, baby brands and Band-Aid are all growing. The CEO now says the company will beat its $1.9 billion cost synergy target, a notable shift from last quarter, when management was not signing up for more. Management also put numbers on the deal for the first time. It expects 2027 EPS dilution no worse than mid-single digits versus standalone Kimberly-Clark, followed by a return to a high-single-digit EPS growth rate in 2028 off the 2026 base. Bears still have legitimate ammunition. Kenvue skincare is lagging its category and Listerine is down about two points. SKU rationalization could create near-term drag, and Kenvue intangible amortization will remain inside adjusted EPS. The departure of EVP Russ Torres, with the CEO taking a more direct operating role, adds execution risk at the exact moment integration begins. The delayed North America launch and a diaper-rash innovation are now slated for early 2027.
Investor expectations entering the print were subdued but improving. Earnings Whispers sentiment rose from -0.11 after the August report to roughly neutral at +0.02, a meaningful but not dramatic shift. The stock has gone essentially nowhere, trading at $108.79 before the report, 0.4% below the open following the prior release. That flat result hides a volatile path. Shares fell to $93.95 in early October, then rallied nearly 16% to within 3.6% of the $112.82 inter-earnings high set on October 30. The stock sits about 5.5% above its 200-day moving average. The Earnings Whispers trend signals are mostly negative, with sequential growth and momentum still deteriorating, although AVWAP remains positive after the October rebound.
The bottom line is that Kimberly-Clark's in-line quarter preserved a credible deal-driven story without fixing the standalone one. The Kenvue close, a more confident synergy outlook and a quantified 2027-2028 path give investors something concrete to underwrite. Meanwhile, falling earnings, slipping price, rising freight inflation and a delayed launch show that the core business is still losing ground. With shares having rebounded sharply into the report, the burden now shifts to integration execution and a North America recovery rather than promises.
Read our earnings preview for Kimberly-Clark Corporation: https://www.earningswhispers.com/article/KMB/22126
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-29 | |
| Oct-28 |
