Loar's Sliding Stock Puts Its $200 Million New-Business Conversion Story To The Test
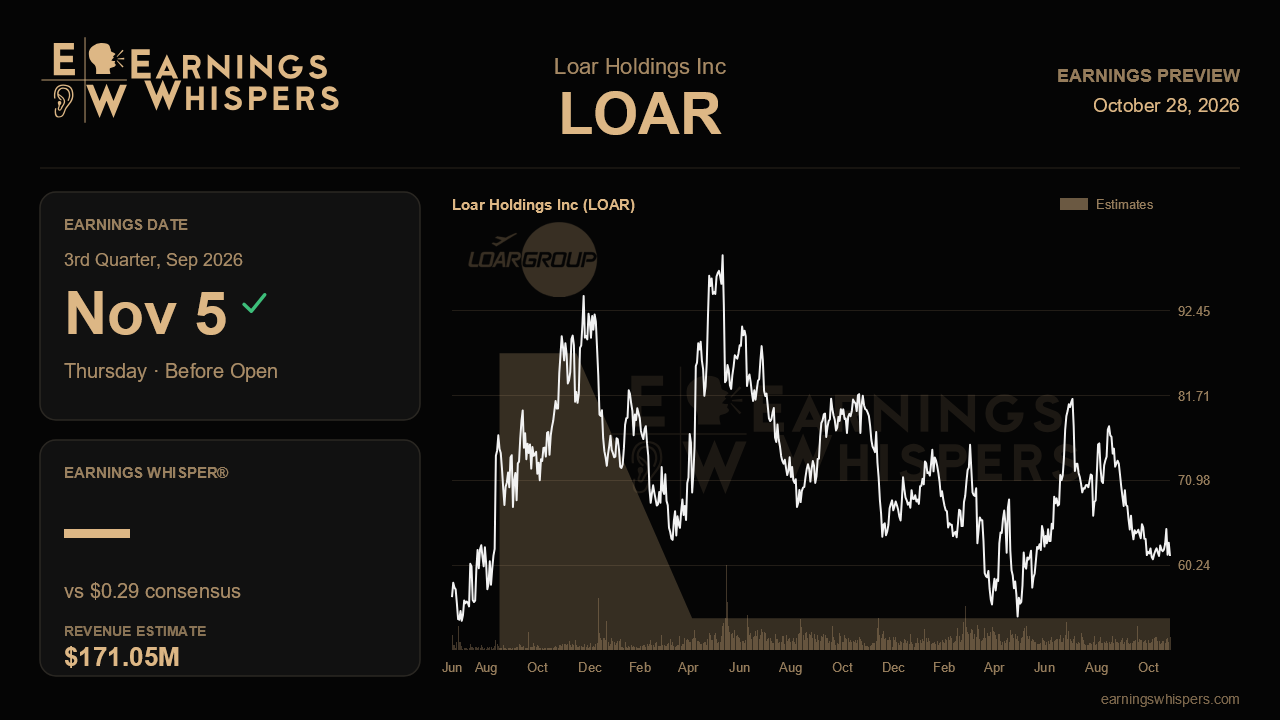
Loar Holdings heads into its third-quarter report with a striking disconnect. Three months ago management delivered its third straight guidance raise, reported a 16th consecutive record quarter for adjusted EBITDA and, for the first time, pointed to roughly $200 million of its organic new-business pipeline converting into firm, sole-source purchase orders. The market's response since then has been to knock the shares down about 24%, while the S&P 500 went essentially nowhere. That leaves Thursday's pre-market release less about whether the business is good and more about whether the momentum is durable enough to justify paying up again.
The Street is looking for earnings of $0.29 a share on revenue of $171.1 million. On the top line, that is a 35% jump from a year ago, flattered by the Harper and LMB acquisitions, but it is essentially flat with the $171.6 million Loar posted last quarter. Earnings are expected to slip about 6.5% from the year-ago $0.31 and fall short of last quarter's $0.33. Some of that drag is familiar: last quarter, higher non-cash amortization and interest tied to the two deals shaved 60 basis points off gross margin and left GAAP net income flat, even as adjusted EBITDA margin climbed to 40.5%. Investors should read the bottom line with that acquisition accounting in mind rather than treat a soft EPS print as an operating stumble.
The bigger reference point is the full-year outlook. Management now expects 2026 net sales of $665 million to $675 million, adjusted EBITDA of $265 million to $270 million and adjusted EPS of $1.32 to $1.36, each lifted for a third consecutive time. A flat sequential revenue estimate looks undemanding against a company that just upgraded its commercial original-equipment outlook from low-double-digit to high-double-digit growth after OE sales rose 28% in the second quarter, up from 18% in the first. If 787, A320 and 737 build rates kept feeding that line, a revenue beat should be within reach. The harder question is whether management raises again. After three lifts, holding the range might be read as a pause in momentum, while a fourth increase would directly counter the skepticism priced into the stock.
The newest catalyst deserves the closest look. The $200 million of converted orders was the proof point management spent a year building toward, and this report should show whether those programs are moving toward production on schedule. Management flagged learning-curve risk on first production parts and said it may need to invest in capacity for fans and motors, restraints and brakes. Rising capital spending tied to demand would be a healthy sign; margin slippage or delivery delays would suggest the ramp is harder than advertised. Updates on the roughly $750 million pipeline, Harper's path to doubling EBITDA and the Boeing cross-sell opportunity will also matter. Defense, guided to only mid-single-digit growth after a choppy first half, remains the swing segment where another weak quarter could revive concerns about lumpiness.
Sentiment has soured noticeably. Bearish readings jumped to about 64% from roughly 22% heading into the last report, and the shares, at $61.40, sit below their 200-day moving average of $66.68 and only about 3% above the post-earnings low of $59.74, a long way from the $81.52 high. That positioning lowers the bar in one sense, since a clean quarter could catch a pessimistic crowd off guard, but a break below recent support on disappointing news is also plausible.
Ultimately, the report hinges on whether Loar can show that last quarter's acceleration was a trend rather than a high-water mark. Continued commercial OE strength, visible progress on the new-business ramp and a steady or higher full-year outlook would validate the bull case the market has recently abandoned. Anything that hints at stalled conversion or capacity strain would make the selloff look prescient.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-07 | |
| Oct-01 | |
| Oct-01 | |
| Sep-11 | |
| Aug-13 | |
| Aug-06 | |
| Aug-05 | |
| Jul-15 | |
| Jul-15 | |
| May-29 | |
| May-07 | |
| May-06 | |
| Apr-17 | |
| Apr-02 |
