Lincoln National Must Back Its Inflection-Point Claim With Alt Returns And Buybacks
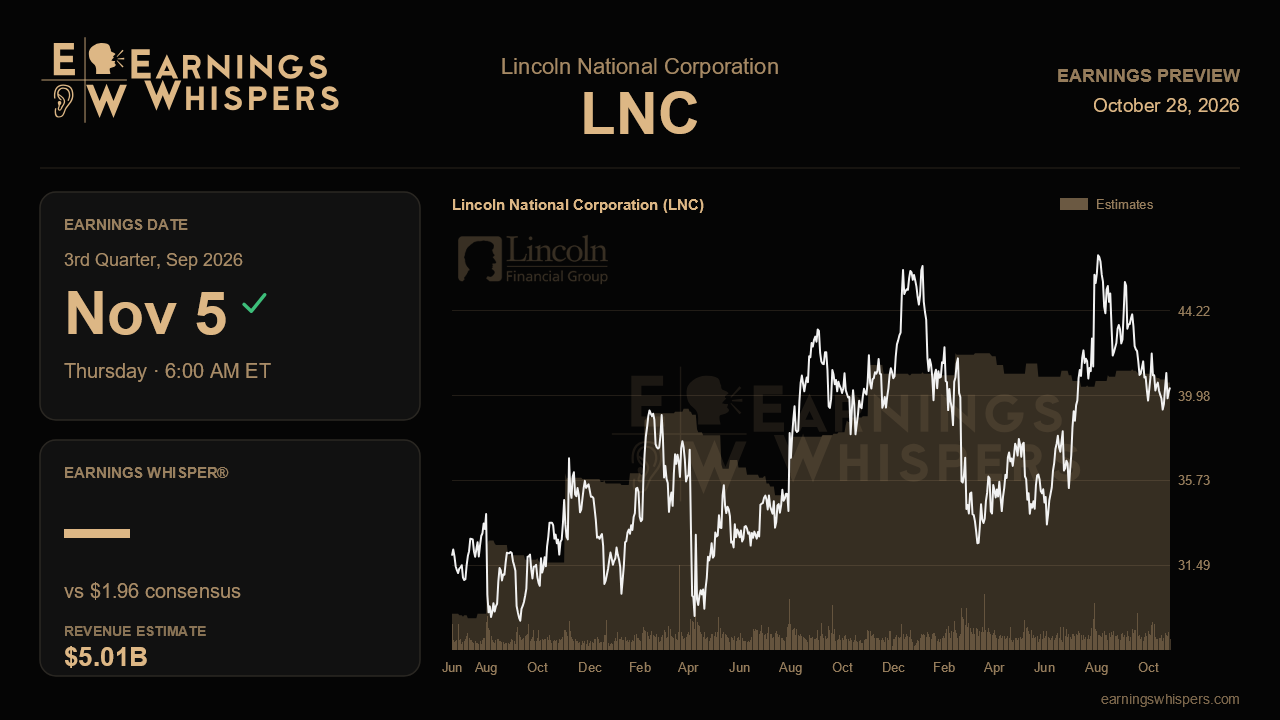
Three months ago, Lincoln National's management told investors the company had reached an inflection point, with its multi-year repositioning largely complete and ahead of schedule. The market has not bought it yet. Shares have fallen 8.1% since that report while the S&P 500 gained 4.6%, leaving the stock nearly 13 percentage points behind the index. The third-quarter release, due before the open on November 5, is the first real chance to show that the capital story management laid out is turning into tangible results.
Wall Street expects earnings of $1.96 per share, about 3.9% below the $2.04 earned a year ago and a step down from the $2.24 posted last quarter. Revenue is forecast at $5.01 billion, up roughly 10% from a year earlier. The gap between rising revenue and slipping earnings tells the story. Analysts appear to be carrying forward the normalization in Group Protection that management flagged, rather than assuming a clean rebound across the business. No formal guidance accompanies the estimate, so the bar is set by the company's own qualitative commitments.
The biggest swing factor is alternative investments. Last quarter they returned only about 4.9% annualized against a 10% target, a shortfall worth roughly $43 million after tax that followed several quarters of 12%-plus returns. Management said it expected a rebound to or above target in the third quarter. If that happens, it alone could put a meaningful cushion under the consensus figure. Another weak print would raise doubts about how much of the earnings base depends on a volatile asset class, and would make the miss look less like a one-off.
Group Protection is the other operating question. Earnings there fell to $147 million from a record $173 million, and the disability loss ratio rose to 71.9% from an unusually low 64.2%. Management said this year-over-year headwind would last through year-end, so the test is whether the ratio holds steady around current levels or keeps climbing. Stabilization would confirm that this is a return to normal rather than a deterioration. Offsetting that, Life earnings have benefited from about 18 months of favorable mortality, and Retirement Plan Services has widened base spreads for three straight quarters, to 119 basis points. More of the same would show the business mix carrying real weight. Annuities are less exciting, with flat operating income and roughly $2.9 billion of net outflows, largely from traditional variable annuities. Any sign that fixed annuity sales are recovering would help.
The capital narrative, though, is what drove last quarter's improved tone. Holding company cash net of pre-funding climbed to about $900 million, up from $655 million two quarters earlier. The Talcott reinsurance deal, which cedes about 37% of the remaining guaranteed universal life block, is expected to close in the fourth quarter and add $30 million to $40 million in annual free cash flow. Management also signaled it would resume share buybacks for the first time since 2022, with more than $700 million of authorization reconfirmed. Concrete repurchase activity or a firm timeline, along with confirmation that the Talcott deal is on track, would make the inflection-point argument hard to dismiss. Investors should also expect details on the redefined operating income measure that starts next quarter.
Sentiment has edged up from neutral to modestly bullish. The stock sits at $40.38, just above its 200-day moving average but near the bottom of its post-earnings range of $38.88 to $47.67, so expectations look restrained. That leaves room for a positive surprise. The deciding issue is straightforward: Lincoln needs an alternative-investment rebound and visible progress on buybacks to show that its improving capital position can outweigh the drag from group normalization.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-27 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-09 | |
| Sep-01 | |
| Aug-25 | |
| Aug-18 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 |
