Precision Drilling Misses A Lofty Whisper As U.S. Reactivation Costs Delay The Margin Payoff Management Now Promises For Q4
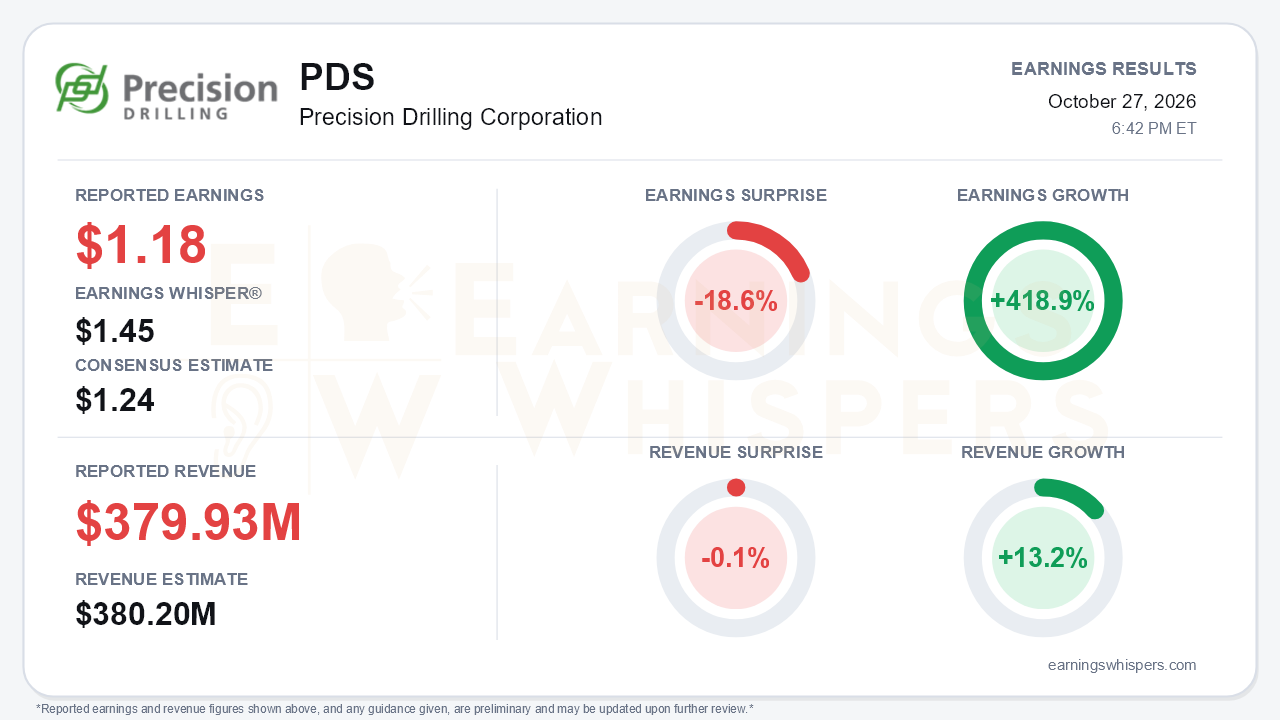
Precision Drilling (NYSE: PDS) delivered the volume growth investors expected but not the profit conversion. Third-quarter earnings of $1.18 per share fell short of the $1.24 consensus and well below the $1.45 Earnings Whisper number, an 18.6% miss. Revenue of $379.93 million was essentially in line with the $380.2 million consensus. Earnings grew 418.9% year over year and revenue rose 13.2%. These normalized figures are in U.S. dollars, while the company reported in Canadian dollars: C$532 million of revenue and C$1.65 of diluted EPS. The central tension is timing. Rig activity, pricing and contract coverage all moved the right way, but the cost of adding U.S. rigs absorbed much of the benefit this quarter. That pushed the margin inflection into a fourth-quarter guide the market must now take on faith.
The quality of the year-over-year comparison deserves scrutiny. The swing from a C$7 million loss to C$21 million of net earnings came mainly from lapping a C$33 million deferred tax charge in last year's quarter, not from a step change in operations. That swing came despite C$8 million of extra depreciation from shorter drill-pipe useful lives. Adjusted EBITDA rose only 6% to C$125 million against 15% revenue growth. Contract Drilling's EBITDA margin compressed to 26.7% from 29.9%. Lower share-based compensation, C$8 million versus C$11 million, also flattered the EBITDA comparison. The pressure point was the U.S.:
- Revenue there rose 29% and utilization days climbed 19%, outpacing the industry's 10% increase.
- Day-rate-driven revenue per day reached US$33,270.
- Operating costs per day jumped 14.7%, as six reactivations cost roughly US$2,125 per utilization day versus US$502 a year ago.
- U.S. daily margin fell to US$7,653 from US$8,700.
- International revenue per day dropped 14% on rig mix, recertification downtime and elevated Middle East costs.
Sequentially, the picture is far better than the miss suggests. Revenue growth accelerated from roughly 11% in the second quarter. Adjusted EBITDA rose from C$97 million in the second quarter, and earnings recovered from a small loss. U.S. rigs averaged 43, up from 35 in the prior quarter, and the Permian count doubled to 16 from a year ago. Canada averaged 73 rigs with heavy-oil demand pushing Super Single utilization up 18%. The modest dip in Canadian revenue per day reflected rig mix, not pricing. Completion and Production Services grew EBITDA 10% at a steady 26% margin.
The call preserved a credible earnings-recovery story, and guidance is where it lives:
- **U.S. margins:** Management expects a step change to US$9,500–10,500 per day in the fourth quarter. That would be the best in two years and firmer than the second-quarter call's "approaching $10,000." Only one reactivation is planned, with 52 warm rigs available.
- **Canada margins:** The Canadian guide of C$13,500–14,500 sits above the third quarter's C$12,817, with near-full Super Series utilization expected through winter.
- **Contract coverage:** The Canadian contract book stands at 28 rigs versus 16 a year ago. U.S. contract discussions are stretching toward 18–24 months.
- **Canadian catalysts:** LNG Canada Phase 2 reached FID, and the Pacific Link pipeline received a national-interest designation.
- **Capital spending:** The capex budget was raised again, to C$275–285 million. That compares with C$245 million at the start of the year and is tied to 25 contracted upgrades plus a pending multi-rig Canadian deal running through 2029.
Bears have legitimate ammunition:
- **Rig count:** The U.S. rig outlook was trimmed to the low-to-mid 40s from earlier talk of the high 40s.
- **Costs:** SG&A guidance rose to C$100 million, and depreciation guidance rose to C$325 million. Labor, drill pipe and diesel inflation are surfacing in both countries.
- **Cash and liquidity:** Operating cash flow slipped to C$71 million as working capital built. Cash fell to C$23 million, and liquidity eased to about C$460 million from C$502 million.
- **Tax dispute:** The CRA reassessment carries a maximum exposure of roughly C$155 million plus interest. Precision has recognized no liability. It would have to pay half of any assessed amount upfront once reassessments are issued. Debt reduction (C$75 million year to date) and buybacks (C$47 million, with a ramp signaled for 2027) remain intact for now.
The market setup is more complicated than the surprise implies. Shares have climbed 26.4% since the open after the July report to about $99.96, roughly 14.4% above the 200-day moving average. That run explains why the whisper sat so far above consensus. Investor sentiment improved from slightly negative to slightly positive, a move of about 0.13. That is a meaningful shift in tone but hardly euphoric. Price and AVWAP trend readings remain positive, consistent with a stock that entered the report with momentum and a higher bar.
The bottom line is that Precision missed on execution timing, not on demand. Activity, pricing, contract duration and the Canadian backdrop all strengthened, while reactivation costs, international softness and creeping inflation held back third-quarter profits. With the stock already well extended, the fourth-quarter U.S. margin step-up is now the test of whether the recovery story justifies its run.
Read our earnings preview for Precision Drilling Corporation: https://www.earningswhispers.com/article/PDS/20786
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Sep-29 | |
| Sep-16 | |
| Jul-28 | |
| Jul-28 | |
| Jul-13 | |
| Jun-29 | |
| May-14 | |
| May-05 | |
| Apr-30 | |
| Apr-29 | |
| Apr-01 | |
| Mar-31 |
