Natural Health Trends Narrows Its Loss Through Cost Cuts, But Revenue Has Reset 20% Lower And The Dividend Went Missing
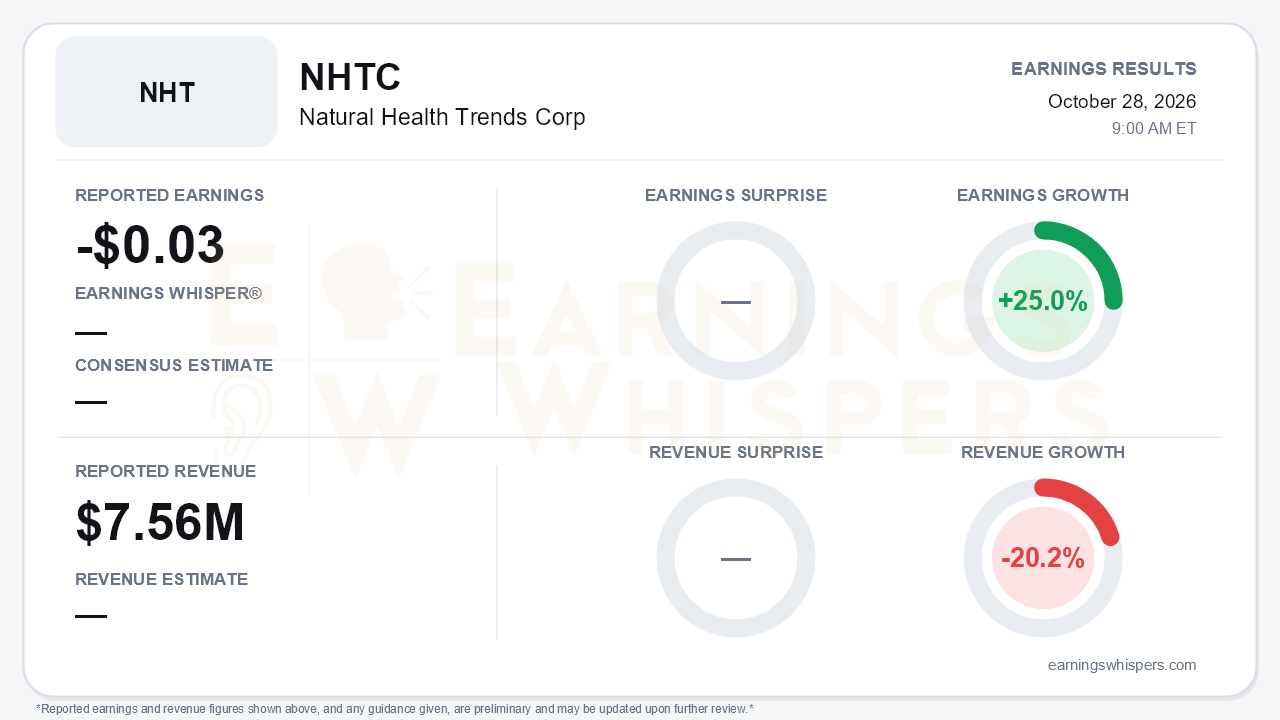
Natural Health Trends (NASDAQ: NHTC) reported a third-quarter loss of $0.03 per share, a 25.0% year-over-year improvement from the $0.04 loss a year earlier, on revenue of $7.56 million, down 20.2%. No consensus estimate was available. The central tension is that management is shrinking losses through cost cuts while the revenue base underneath keeps contracting. Operating loss fell 57% sequentially to $277,000. But revenue held at $7.6 million only after a steep slide from $9.7 million in the fourth quarter of 2025 and $9.2 million in the first quarter of 2026. A narrower loss on a much smaller business is not the same as a recovery.
The quality of the improvement deserves scrutiny. Net loss nearly halved, to $232,000 from $431,000 a year ago. The much lower share count, 8.6 million weighted shares versus 11.5 million, actually magnified the per-share loss. The bigger driver was commissions, which fell to 35.9% of revenue from 40.9% in the second quarter and 41.8% in the first. That is welcome leverage, but part of the saving reflects disciplinary action against members under a code-of-conduct matter. That is a cost benefit that could prove expensive if it thins the field force. Gross margin of 74.2% improved from 73.7% a year earlier, helped by a shift to East Asian manufacturing, but slipped from 75.2% in the second quarter on promotional mix. Management said the incentives and lower-priced packages accounted for most of the year-over-year revenue decline.
The call reinforced a softer narrative. On the plus side, restructuring savings reached about $500,000 in the quarter and $1.1 million year to date, tracking toward the $1.5 million annualized target. Active Members rose to 27,040 from 26,000 in June, though that remains below 28,030 a year ago. Management also said half of the markets outside Hong Kong and China grew sequentially. On the other side, management added regulatory uncertainty in China to the consumer pessimism already weighing on its largest market. The first-quarter description of a "stabilized top line" proved premature, given the roughly 17% sequential drop that followed in the second quarter. Earlier "clear path to profitability" language gave way to an emphasis on "financial discipline." The 25th anniversary celebration drew about 1,000 attendees versus the 1,500 previously anticipated, and the hoped-for momentum is not yet visible in sales.
Capital return is where the setup changed most. No quarterly dividend was declared on the call, after $0.10 per share payouts were declared on the fourth-quarter 2025 and first-quarter 2026 calls. The press release emphasized buybacks instead, with $15.8 million of authorization available. That authorization is nearly equal to the company's $17.6 million in cash and marketable securities. Those balances have fallen from $28.9 million at year-end and $21.2 million at the end of March. The decline reflects $5.9 million of year-to-date repurchases, $1.7 million in dividends and $3.3 million of operating cash burn. Actual buyback activity has slowed sharply: only $27,000 was spent in the third quarter and $56,000 in October. Operating cash use improved from $5.0 million a year earlier, but deferred revenue fell from $5.6 million to $3.0 million, a $2.5 million drawdown that flatters reported revenue relative to new cash coming in. Shrinking cash is also eroding other income, which fell to $112,000 from $206,000.
Near-term catalysts are product- and technology-driven:
- the Move Prime joint-health drink, launching in coming weeks;
- a traditional Chinese medicine product for China in coming months;
- an AI-powered member app already rolled out in China, with AI search and product training to follow.
These are reasonable levers for a business whose problem is member purchasing activity, but none has been proven at scale.
Investor sentiment and current pricing data were not available for this review. Shares opened at $1.86 after the July report, well below the current 200-day moving average of $2.36, indicating the stock was already trading at depressed levels relative to its longer-term trend heading into this period. Removing the dividend takes away what had been a central support for a micro-cap with a shrinking top line.
The bottom line is that NHTC delivered real cost progress: commissions are down, operating losses have narrowed for consecutive quarters, and cash burn has eased. But revenue has reset roughly 20% lower and the China backdrop has broadened. The commission improvement carries field-force risk, and the dividend that anchored the investment case was not declared. Until new products and the AI app show up in sequential revenue growth, the quarter reads as successful damage control rather than a turnaround.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-21 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-22 | |
| Apr-30 | |
| Apr-29 | |
| Apr-29 | |
| Apr-22 | |
| Mar-05 | |
| Mar-05 | |
| Mar-04 |
