Amphenol Tops Consensus And Shatters Its Own Guide But Misses The Whisper As Order Momentum Cools Beneath AI Surge
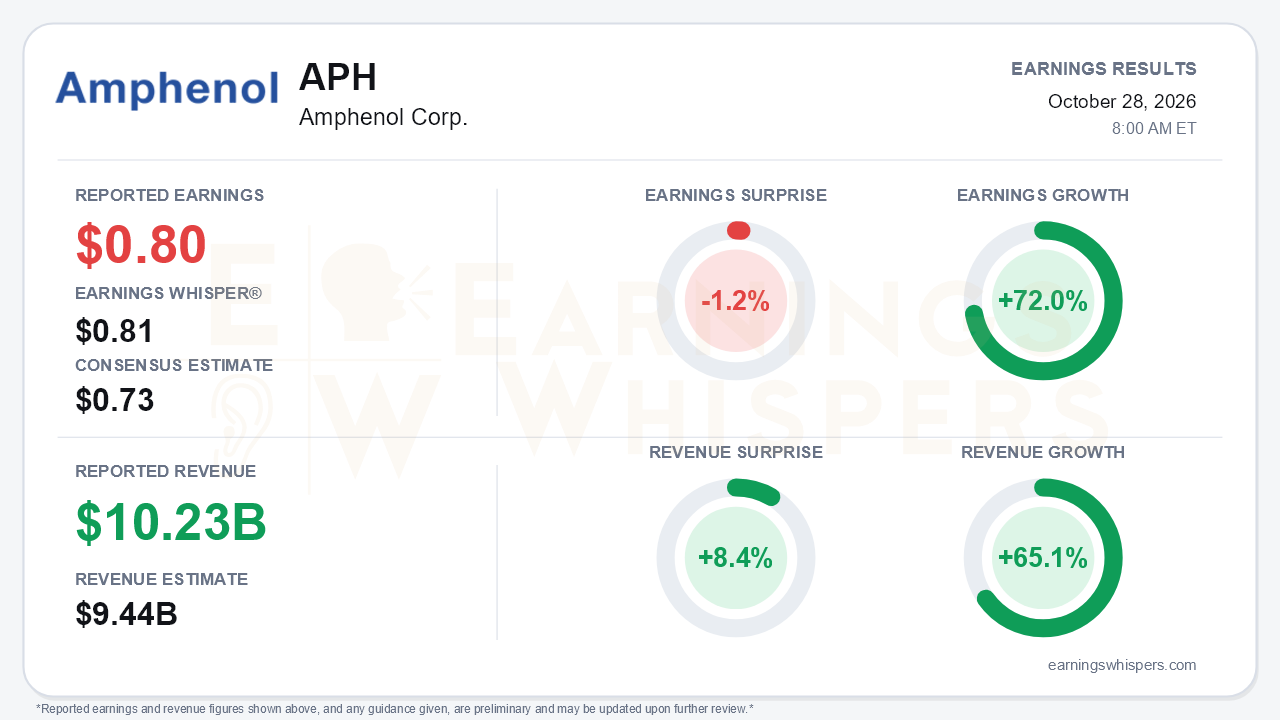
Amphenol delivered its first $10 billion quarter and blew through its own guidance. It still fell just short of the bar that mattered most to the market. Adjusted EPS of $0.80 cleared the $0.73 consensus but missed the $0.81 Earnings Whisper by 1.2%. Revenue of $10.23 billion beat consensus by 8.4% and grew 65.1% year over year. Earnings grew 72.0%, and organic sales growth re-accelerated to 37% from 30% in the second quarter. By almost any operational yardstick this was a dominant quarter. The central tension is that the forward indicators are quietly decelerating even as reported results accelerate. A stock that had already run to a 52-week high and then sharply reversed was priced for perfection, not just excellence.
The quality of the quarter is largely high, with a few caveats. GAAP EPS was $0.79 versus $0.80 adjusted. The gap came mainly from a $60 million discrete charge tied to settling foreign tax matters, partly offset by excluded stock-compensation tax benefits. More important for run-rate earnings, Amphenol lifted its adjusted tax rate to 27.0%. It cited unfavorable China tax determinations and a continued shift of income to higher-tax jurisdictions. Interest expense also rose to $212 million from $81 million after the CommScope financing. Adjusted operating margin reached 29.7%, up from 27.5% a year ago but essentially flat with the second quarter's 29.8% as tariff-recovery benefits faded. Management said margin excluding those recoveries rose roughly 70 basis points sequentially, and the CFO suggested 29.7% is not a ceiling. Free cash flow was a record $1.6 billion despite a $416 million working-capital build and capex of $457 million.
The engine is unmistakably AI. IT datacom grew 77% organically and 30% sequentially, roughly double the mid-teens increase management had expected. AI now accounts for about three-quarters of that business, and IT datacom has climbed to 48% of total sales from 38% four quarters ago. The breadth was better than the AI narrative alone suggests. Industrial organic growth climbed for a fourth straight quarter, reaching 25%. Mobile devices grew 29% and defense grew 30%. CommScope keeps outperforming: management raised its 2026 sales outlook to $5.1 billion from $4.6 billion and its EPS accretion to $0.18 from $0.15.
Bears have legitimate ammunition beneath those headlines:
- **Communications networks:** organic sales collapsed 28% year over year, from a 6% decline in the second quarter and flat results before that. Management guided to a further fourth-quarter decline on broadband softness.
- **Book-to-bill:** record orders of $12.2 billion still produced a 1.19 ratio. That continues a steady slide from 1.31, 1.24 and 1.23 over the prior three quarters, and one end market has now dropped below parity.
- **Fourth-quarter outlook:** IT datacom is guided to only mid-single-digit sequential growth after the 30% surge, with industrial and automotive expected to moderate. The Q4 guide of $10.3 billion to $10.5 billion and $0.81 to $0.83 in EPS sits above estimates but implies little sequential progress from the third quarter's $10.23 billion and $0.80.
- **Concentration:** the call raised questions about neocloud funding and longer-dated backlog.
Capital deployment remains aggressive and confident. Amphenol raised its dividend 20%, authorized a new $4 billion buyback starting in 2027, and committed about $1.6 billion to four acquisitions with roughly $750 million in combined annual sales. Three of those deals are not yet in guidance and are expected to dilute margins modestly. Net leverage fell to 1.1x, so the balance sheet can absorb the spending comfortably.
The market setup is more complicated than the surprise implies. Shares opened at $76.15 after the July report, surged to a 52-week high of $89.93 on October 6, then slid to an inter-earnings low of $71.44 on October 23, just days before the release. At $78.21 heading into the print, the stock was up only 2.7% since the last report. It sat 3.9% above its 200-day moving average and 13% below its recent peak. Investor sentiment cooled from mildly positive (0.146) to roughly neutral (-0.018), a meaningful but not dramatic shift that suggests enthusiasm had already been tempered. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative.
The bottom line is that Amphenol's quarter was operationally exceptional. It delivered accelerating organic growth, record orders and cash flow, another CommScope upgrade, and guidance above estimates. Yet the narrow Whisper miss, a sliding book-to-bill, a deepening communications networks decline, and a flattish fourth-quarter trajectory give skeptics something to argue about. The growth story remains credible, but it is increasingly tethered to AI datacom spending. Investors will likely judge the stock on order momentum more than on the size of the beat.
Read our earnings preview for Amphenol Corp.: https://www.earningswhispers.com/article/APH/20823
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 7 hours | |
| 12 hours | |
| 12 hours | |
| 14 hours | |
| 16 hours | |
| 17 hours | |
| Oct-21 | |
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Oct-02 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 |
