Nexstar's Political Windfall Faces Its Real Test As Tegna Litigation And Leverage Weigh
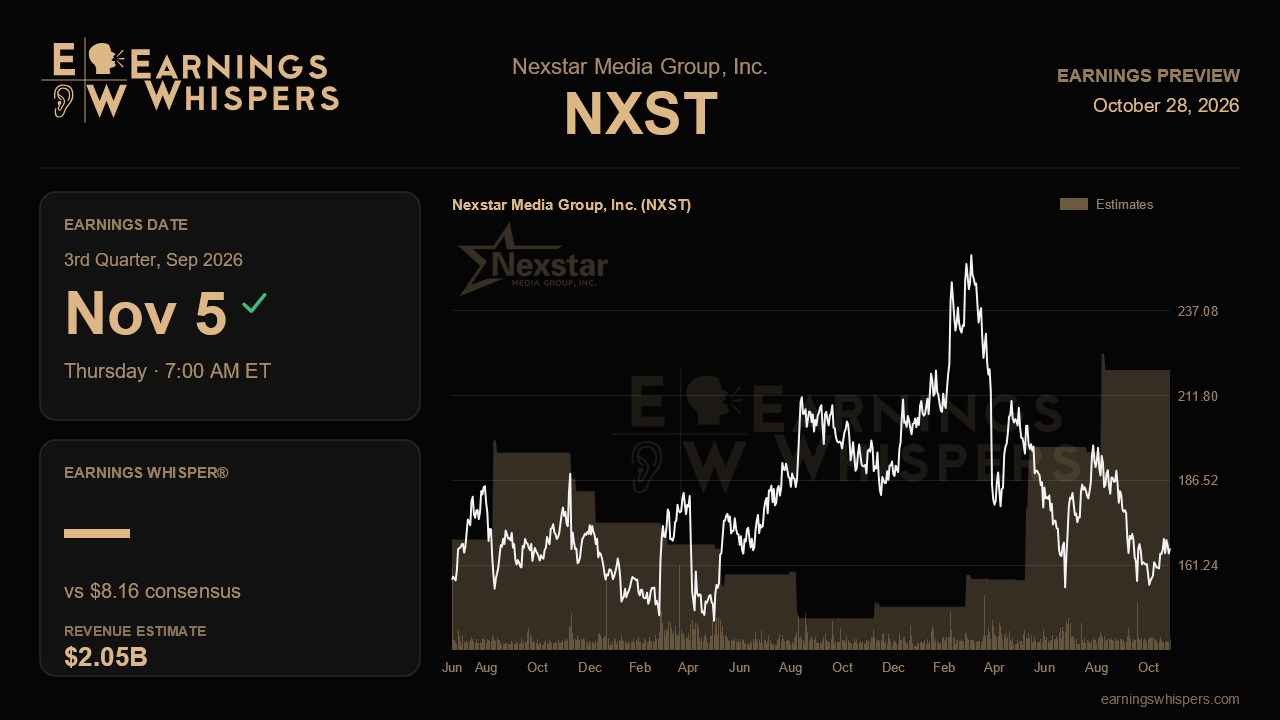
Nexstar heads into its third-quarter report with an unusual split personality. Operationally, the combined Nexstar-Tegna business just posted the best quarter in its history, and management spent the last call describing political advertising running hotter than its own plans. The stock has gone the other way. Shares have fallen about 9% since that report while the S&P 500 was essentially flat, and at roughly $166 they sit well below the 200-day moving average near $193 and closer to the bottom of the post-earnings range than the top. The market seems to be pricing the balance sheet and the courtroom rather than the income statement.
The numbers the Street wants are big. Consensus calls for EPS of $8.16 on revenue of about $2.05 billion, implying growth of roughly 281% and 71% from the year-ago quarter, when Nexstar earned $2.14 on $1.20 billion before Tegna was in the fold. Much of that jump reflects the acquisition, so the year-over-year comparison flatters. The sequential picture is more revealing. Revenue is expected to edge up only modestly from last quarter's $1.99 billion, yet the EPS estimate is more than double the prior quarter's $3.61. With no stated EPS basis, readers should be cautious about how comparable that figure is, but the gap signals that analysts expect midterm political dollars, which carry very high incremental margins, to drop through to the bottom line in force.
That makes political the first thing to check. Management said it raised internal political targets a couple of times during the second quarter and pointed to competitive Ohio Senate and gubernatorial races as sources of third-quarter upside. That is a notable progression from earlier calls, when the company called the cycle too early to judge and later framed its share of broadcast political in more measured terms. A third-quarter political number that confirms this momentum would validate the most important part of the bull case. A tally that merely matches plans would look like a letdown given how often targets were lifted.
Core advertising is the second test. Combined non-political ad revenue fell 5.8% in the second quarter, worse than the flattish to low-single-digit declines management had floated earlier, and the third-quarter guide called for a mid-single-digit decline that was only slightly better. Political crowding out regular inventory can mask underlying weakness, so the trend matters more than the level. Evidence that the new Nielsen local measurement methodology, effective at the end of August, is lifting local impressions would be an early sign of a structural tailwind. Distribution deserves scrutiny too, since Tegna's retransmission revenue slipped as rate increases failed to offset subscriber losses, and DirecTV declined the FCC's status-quo extension in July. The CW, which management has repeatedly said is on track for fourth-quarter profitability with full-year losses improving by more than 30%, should show losses narrowing further as the ESPN and Roku distribution deals take hold.
The swing factor for the stock, however, may be cash. Total debt stands near $11.7 billion, net leverage was 4.22 times, buybacks are paused, and management targeted more than $1 billion of debt paydown in the second half. With roughly $300 million of Tegna synergies stripped from the covenant calculation because the bench trial is not until July 2027, deleveraging has to come from organic free cash flow. Sentiment has soured sharply, moving from roughly neutral before the last report to clearly bearish now, which lowers the bar somewhat but also shows how little benefit of the doubt remains.
Ultimately, this quarter has to prove that the political surge converts into fast, visible debt reduction. If free cash flow and paydown track toward management's second-half goal while core advertising stabilizes, the improving narrative from last quarter holds despite the litigation delay. If political strength fails to translate into a meaningfully lighter balance sheet, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-22 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 | |
| Oct-12 | |
| Oct-06 | |
| Oct-01 | |
| Sep-17 | |
| Sep-03 | |
| Sep-02 |
