Payoneer Faces A Margin Test As Revenue Grows But Profits Are Expected To Shrink
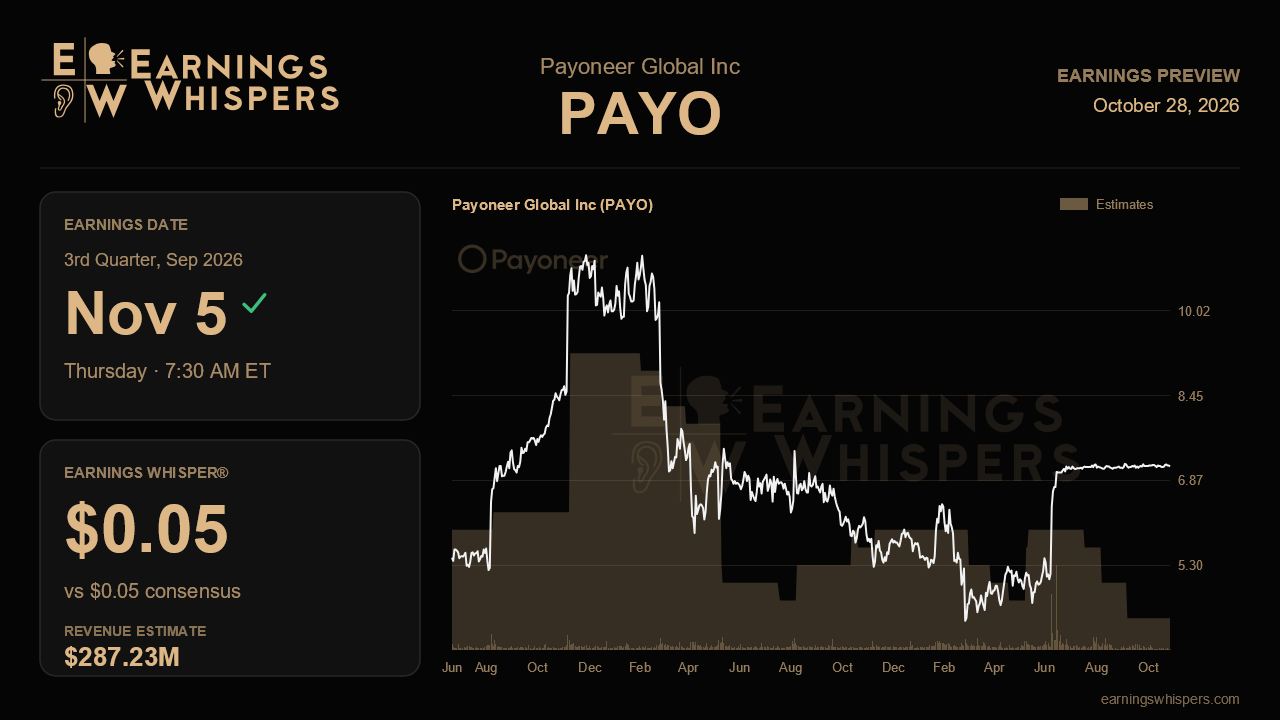
Payoneer heads into its third-quarter report with a puzzle that the top line alone cannot solve. Wall Street expects the company to sell more than it did a year ago, yet earn less on each share. That gap between growth and profitability is the real story behind the November 5 release, due before the opening bell. It arrives as the stock sits pinned against the top of a remarkably narrow trading band.
Consensus calls for earnings of $0.05 per share on revenue of about $287.2 million. Revenue would rise roughly 6.1% from the $270.9 million reported a year earlier, which is respectable but hardly a sprint for a company pitching itself as a central player in global digital commerce. Earnings, by contrast, are expected to fall about 16.7% from the year-ago $0.06. The Earnings Whisper also sits at $0.05, matching consensus. The market's informal bar therefore offers no extra cushion and no hidden optimism to clear.
The sequential picture is more encouraging and may matter more for sentiment. Last quarter Payoneer earned just $0.02 on revenue of $274.3 million. Reaching the current estimates would mean revenue climbing nearly 5% in a single quarter while per-share profit more than doubles. That is the crux of the setup. Analysts are not just modeling more volume. They are betting that a larger share of incremental revenue reaches the bottom line after a thin second quarter. If revenue lands near forecast but earnings stall closer to last quarter's level, it would suggest that costs, pricing or business mix are absorbing growth faster than the Street assumes. A result that meets or beats on both lines would argue that the weak second-quarter margin was a trough rather than a new baseline.
With no updated company outlook to anchor against, the report itself has to carry the burden of proof. That raises the importance of whatever management says about the fourth quarter and the year ahead. Commentary that supports continued sequential improvement in profitability would likely matter more than a penny either way on the headline number. A cautious tone on expenses or take rates could overshadow an in-line print.
Sentiment has softened its edge without turning friendly. Readings sit at 27.2% bearish, compared with 40.7% bearish heading into the prior report. That points to fewer skeptics, though skeptics still clearly dominate. The stock tells a similar story of wary patience. Shares are up just 0.1% since the last report, roughly in line with a flat S&P 500, and have traded between $7.02 and $7.19 the entire time. That tight channel follows a far more dramatic prior quarter, when the stock ran from $4.52 to $7.18. At $7.13, Payoneer sits well above its 200-day moving average of $6.10 and within a whisker of its post-earnings high. The chart is effectively coiled at resistance, and the report could serve as the catalyst for a breakout or a retreat.
The central question is whether Payoneer can show that its growth is profitable growth. Mid-single-digit revenue gains are already embedded in expectations. What will determine whether the stock clears its recent ceiling is evidence that margins are rebuilding from last quarter's low point. Without that evidence, a shrinking year-over-year profit line will look less like a pause and more like a structural problem.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-22 | |
| Oct-19 | |
| Oct-13 | |
| Sep-30 | |
| Aug-17 | |
| Aug-06 | |
| Aug-03 | |
| Jul-23 | |
| Jul-13 | |
| Jul-13 | |
| Jul-02 | |
| Jun-25 |
