Parker-Hannifin's Record Orders Face A Skeptical Market As Shares Slide 16% Into Fiscal Q1
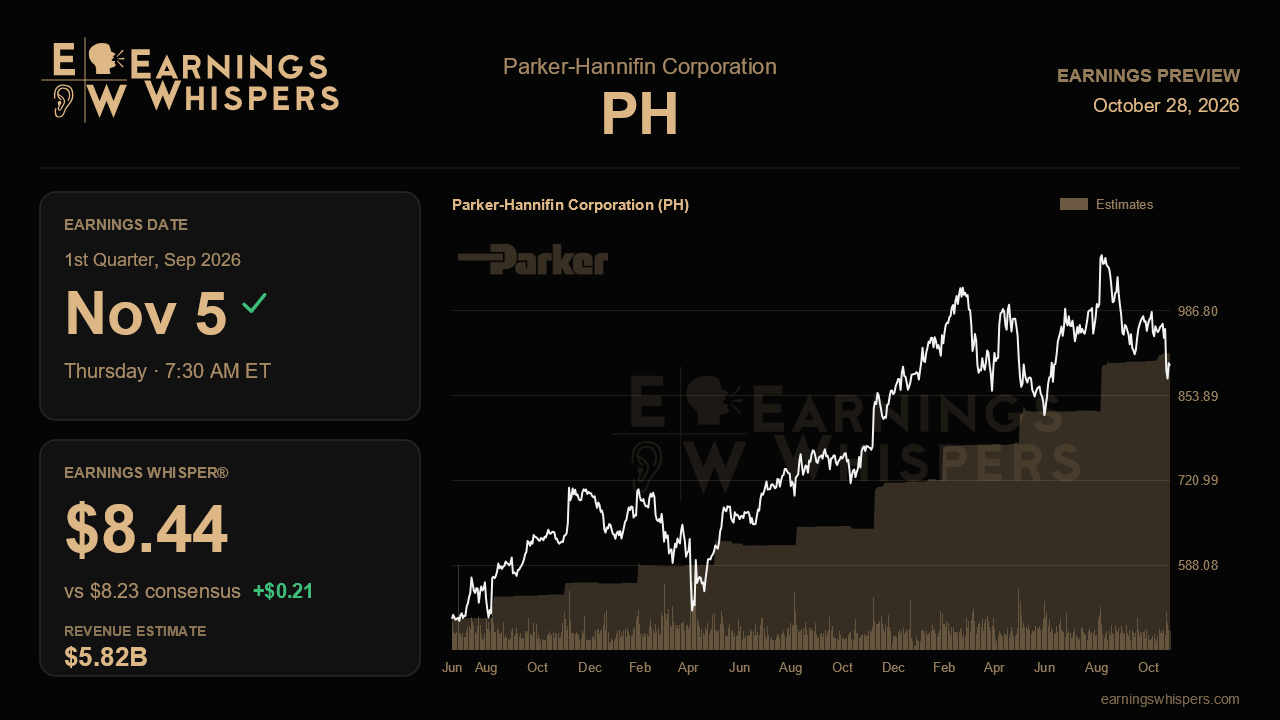
Parker-Hannifin closed its fiscal year with the strongest set of numbers in its modern history, then watched its stock fall more than 16% while the S&P 500 went essentially nowhere. That gap is the story heading into the fiscal first-quarter report on November 5. Management talked about accelerating orders, a record backlog and a raised long-term margin target. The market is now asking whether that momentum carried into the new year or whether the fourth quarter marked a peak.
The Street expects earnings of $8.23 per share on revenue of about $5.82 billion, which would be growth of roughly 14% on both lines from $7.22 and $5.08 billion a year ago. That is strong growth by any industrial standard. Revenue growth of that size runs well ahead of the 7% organic growth management guided for the full year, so the estimate appears to include contributions from acquired businesses as well. The whisper number of $8.44 sits about 2.5% above consensus, a modest but real signal that the more engaged crowd expects another beat. Consensus also implies a sizable step down from the $9.27 earned last quarter even though revenue is expected to edge higher, which suggests analysts are modeling margins below the record fourth-quarter level of 28%. That leaves some room for upside if pricing and productivity hold.
The full-year setup is unusual. Management guided fiscal 2027 earnings of $34.25 to $35.25, with a midpoint of $34.75, yet the full-year consensus of $34.00 sits below even the low end of that range. Analysts do not seem to fully believe the guidance, despite a track record of beating it. In fiscal 2026, the company raised its outlook steadily, and final EPS of $32.31 came in above both the $30.70 guide from the second quarter and the $31.20 guide from the third. If the first quarter tracks toward the guidance midpoint, the gap between management and the Street becomes hard to justify.
The most important evidence will be orders and backlog. Last quarter, three-month order rates jumped 16% in North America and 24% internationally, a sharp acceleration from the 7% and 6% pace a quarter earlier. Management presented this as the long-awaited broadening of the short-cycle industrial recovery. Backlog that holds near or above the record $12.8 billion, along with orders that stay solidly positive, would support that view and the first-ever guide for growth in every market vertical. A sharp drop in orders would suggest the fourth-quarter surge was partly pull-forward. On margins, the company guided 27.7% for the year with incrementals at the top of its 30% to 35% range. Results close to that pace would show the new 30% target for fiscal 2031 rests on real execution rather than ambition. Aerospace, guided to 8.5% organic growth after four straight double-digit years, should moderate gracefully rather than abruptly.
Investors also want an update on deals. Curtis is integrated, while Filtration Group and the high-margin Circor aerospace and defense business are pending. Together they would push leverage toward roughly 3 times. Any comment on closing timing, financing costs and the pace of debt reduction will matter for the earnings math beyond this quarter.
Sentiment has cooled from solidly bullish before the last report to roughly neutral now. The stock trades around $901, below its 200-day moving average near $949 and closer to the bottom of its post-earnings range than the $1,100 top. Expectations, in other words, have reset lower even as fundamentals were reported at their best. The question this report must answer is whether the order acceleration was durable. If it was, a valuation built for a slowdown starts to look misplaced.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 5 hours | |
| Oct-20 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-01 | |
| Sep-24 | |
| Sep-17 | |
| Sep-15 | |
| Sep-15 | |
| Sep-11 | |
| Sep-10 |
