Portillo's Must Prove Its Positive Summer Comps Survived Tougher Promotional Comparisons
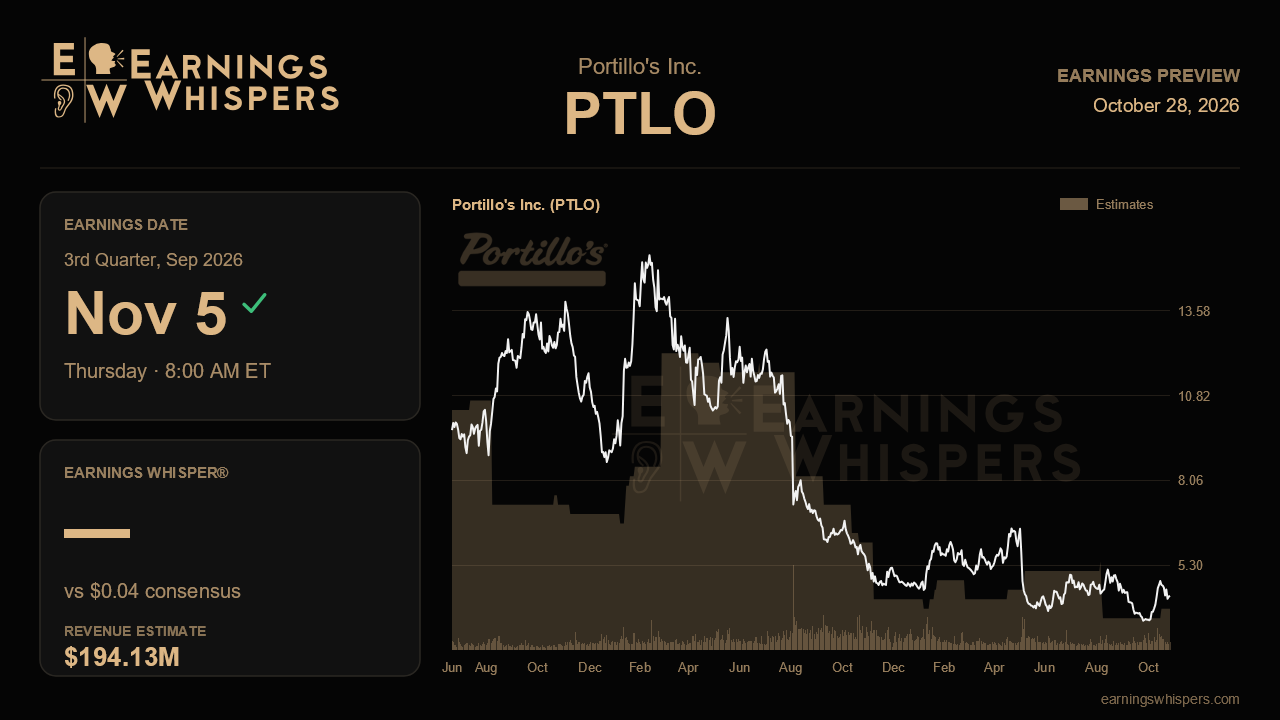
When Portillo's last reported, management did something restaurant executives rarely enjoy. It trimmed its margin outlook, admitted that some Texas and Arizona restaurants were built too fast and too close together, and announced a corporate layoff. One bright spot cut through the gloom: same-restaurant sales were running slightly positive early in the third quarter. The report due before the open on November 5 will show whether that early momentum lasted through the full quarter or faded as the company began lapping heavier promotions.
The Street is looking for earnings of $0.04 per share on revenue of about $194.1 million. That would double last year's $0.02 and lift sales roughly 7% from $181.4 million. The doubling sounds impressive but rests on a tiny base, and it would still mark a sharp step down from the $0.09 earned last quarter. The revenue gain also needs some explaining. With comparable sales hovering near flat, most of that growth has to come from newer restaurants. Those are the same Sun Belt units whose sales expectations management just cut, so the mix of revenue matters as much as the headline total.
The guidance framework sets the bar. Management now expects full-year adjusted EBITDA of $92 million to $96 million. It also lowered its restaurant-level margin target by roughly 75 basis points at the midpoint from the earlier 20.5% to 21.0% range. Second-quarter restaurant margin came in at 21.7%, down about 190 basis points from a year earlier, as commodity inflation jumped to 7% on beef and produce. Third-quarter results need to show that inflation is moderating toward the mid-single-digit pace management still expects for the year. If beef costs stayed hot, the reset margin target could start to look optimistic.
Traffic is the operational question that matters most. Transactions fell 3.4% in the second quarter, and management warned of more than 200 basis points of headwind in the back half from lapping last year's promotions. Executives argued that much of this pressure is deliberate, since they are pulling back on low-margin deals rather than chasing volume. That argument holds only if pricing and check growth offset the lost visits without hurting margins. Positive full-quarter comps would support the strategy. A slide back into negative territory would suggest the promotional pullback is costing more than expected. Growth in the Perks loyalty program, which reached a record 15.1% of sales, along with continued strength in Chicagoland, would help show that the core customer base is holding up.
This quarter also offers the first look at the self-help story. The $10 million to $15 million savings program, built on headcount cuts, supply chain gains and lower indirect spending, was expected to begin contributing in the third quarter. Early evidence in general and administrative expenses would add credibility. Free cash flow has turned positive and the company has been paying down its revolver, which had $97 million drawn last quarter. Further reductions in that balance would reassure investors worried about about $338 million of net debt. Updates on the pending real estate review, the smaller Dallas-Fort Worth airport prototype and the brand strategy rollout under the new CFO and executive chef could shape the longer-term outlook more than the quarterly numbers do.
The market has not given management much benefit of the doubt. Shares have fallen 6.3% since the last report while the S&P 500 was flat. At $4.31, the stock trades below its 200-day moving average of $4.84 and sits near the middle of its post-earnings range of $3.29 to $5.24. Sentiment remains slightly bearish, though less so than heading into last quarter, suggesting skepticism has eased somewhat. The central test is simple to state. Portillo's needs to show that comparable sales stayed positive and that margins held near the reset guidance despite tougher comparisons. If it can, the strategic reset starts to look like a plan. If not, it looks more like another guidance cut waiting to happen.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-08 | |
| Oct-06 | |
| Sep-18 | |
| Aug-13 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-23 | |
| Jul-23 | |
| Jul-15 | |
| Jun-29 | |
| Jun-10 | |
| Jun-05 |
