ScanSource Must Prove Its Growth Inflection Is Real As MicroAge Deal Nears Close
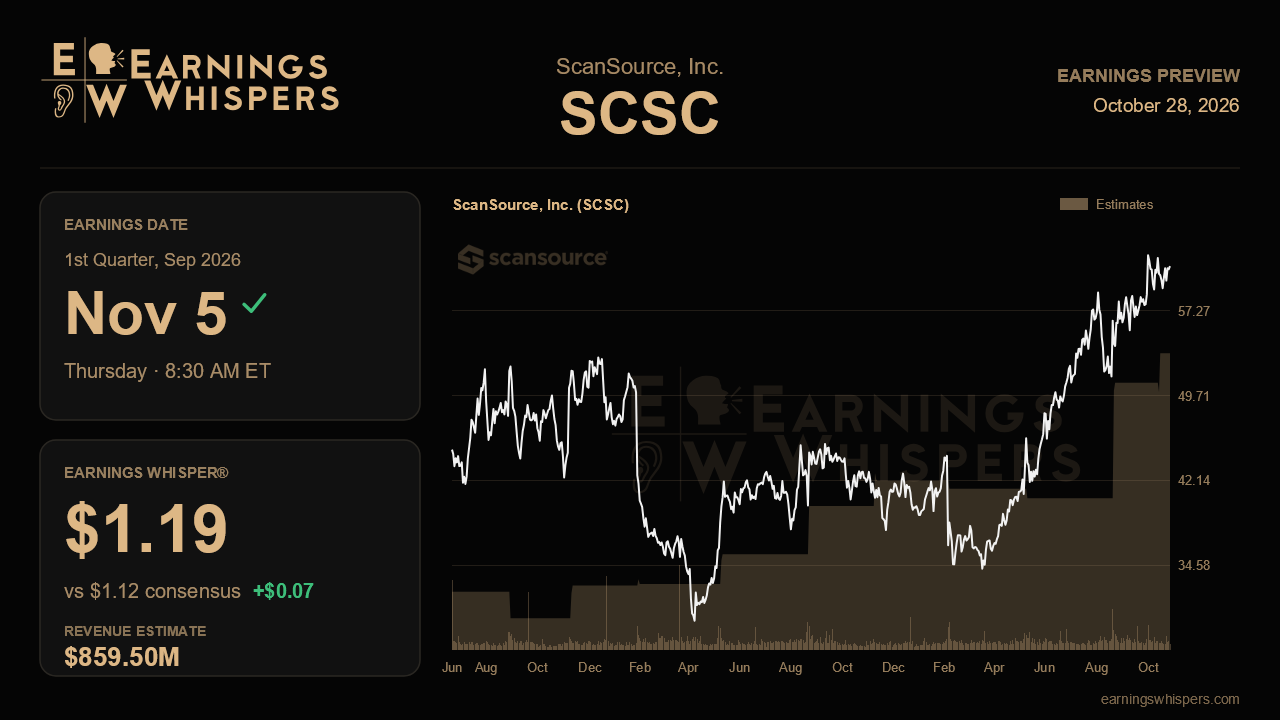
ScanSource heads into its fiscal first-quarter report with a story that changed sharply in a single quarter. After spending much of fiscal 2026 trimming guidance and describing a back-half-dependent recovery, management closed the year with 17% revenue growth, a record $1.46 in adjusted earnings per share and a confident fiscal 2027 outlook. It also signed the MicroAge acquisition, its biggest strategic bet in years. The stock has not fully bought in, slipping 5.5% since that report while the S&P 500 edged higher. The November 5 release, due before the open, is the first real test of whether the acceleration carries forward.
The Street expects earnings of $1.12 per share on revenue of $859.5 million. That revenue figure would be up 16.2% from $739.7 million a year ago, effectively extending the fourth quarter's pace, while EPS would rise only 5.7% from $1.06. That gap matters. Analysts are modeling strong sales growth but little operating leverage, which suggests caution about margins, deal-related costs or financing as MicroAge approaches its closing. The whisper number of $1.19 sits modestly above consensus, a sign that some market participants see room for a cleaner flow-through to the bottom line. Even so, a step down from $953.1 million and $1.46 in the June quarter means sequential comparisons will look softer, so year-over-year growth is the right lens.
Guidance frames the bigger opportunity. Management now calls for fiscal 2027 revenue of $3.42 billion to $3.55 billion, along with 6% to 10% organic growth and adjusted EBITDA of $158 million to $165 million, roughly a 4.6% margin. Full-year consensus of $3.17 billion sits well below the bottom of that range, likely because many models have not fully incorporated MicroAge. That leaves room for upward estimate revisions if the company reaffirms its outlook, but it also puts the burden on management to show the acquisition math works. Any details on closing timing, initial contribution and integration costs will shape how quickly analysts close that gap.
Operationally, the key evidence is whether the Specialty Technology Solutions segment sustains the momentum that drove fourth-quarter sales up 18% and adjusted EBITDA up 28%. Management credited broad-based demand and the return of large deals that had previously stalled or been broken into pieces, along with a more aggressive share-taking posture under new sales leadership. A quarter with growth in the mid-teens and stable or improving segment margins would validate that narrative. Recurring revenue, which grew more than 10% and now supplies about a third of gross profit, should keep providing ballast. Management also said growth would be weighted to the first half because comparisons get tougher later in the year, so a slowdown already this quarter would be hard to explain away. Brazil remains a drag, and the Juniper line, delayed by supplier constraints, is not expected to help until the second half, so neither should be a surprise. Cash flow deserves attention too, since the fiscal 2027 free cash flow target of at least $85 million already sits below last year's $114 million.
Sentiment has cooled noticeably, moving from slightly bullish before the last report to mildly bearish now, despite the far stronger fundamental tone. Technically, the stock still trades well above its 200-day moving average near $47.55, and its post-earnings range of roughly $53 to $67 sits entirely above the prior quarter's range. At $61.25, it is in the middle of that band rather than pressing a breakout.
The central question is whether the June quarter marked a durable turn or a well-timed burst of delayed deals. If ScanSource posts mid-teens growth with operating leverage and reaffirms an outlook that already sits above the Street, the skepticism reflected in the stock and sentiment looks overdone. If growth fades or margins slip just as MicroAge adds complexity, the recovery narrative gets much harder to defend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-22 | |
| Sep-02 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-17 | |
| Aug-05 | |
| Jun-30 | |
| May-07 | |
| May-07 | |
| May-07 | |
| Apr-21 |
