Ralph Lauren Faces A Higher Bar As Wall Street Bets Q1 Momentum Carries Into Fall
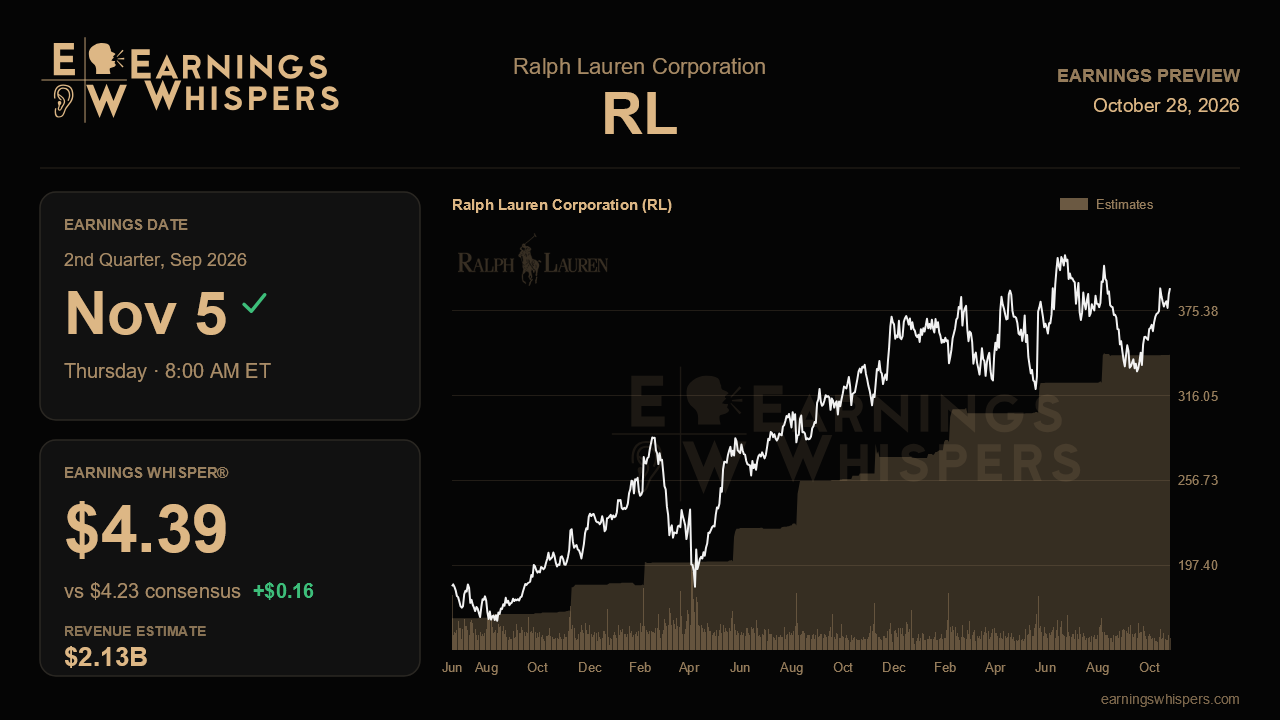
Ralph Lauren has spent more than a year proving that a heritage brand can grow like a challenger, and the fiscal second-quarter report due before the open on November 5 is the first real test of whether the latest acceleration was a durable step up or partly a quirk of timing. Last quarter's 13% constant-currency revenue gain blew past management's own mid-to-high single digit outlook, and executives raised nearly every full-year target. Now the company has to show that the engine is still running without the help of a one-time wholesale tailwind.
The Street is looking for earnings of $4.23 a share on revenue of roughly $2.13 billion, which would mean growth of about 11.6% on the bottom line and 5.9% on the top line versus last year's $3.79 and $2.01 billion. That revenue figure implies a sharp downshift from the first quarter's pace, which makes sense once the moving parts are considered. North America wholesale jumped 22% last quarter, helped by resumed shipments to a luxury account and order timing that may have pulled sales forward. The dollar has also turned from a tailwind into a headwind worth roughly 50 to 100 basis points of revenue this year. Against a raised full-year guide of 5% to 6% constant-currency growth, consensus sits comfortably in line rather than stretched. The Earnings Whisper of $4.39, however, runs about 4% above consensus, signaling that the more aggressive crowd expects another margin-driven beat.
Margins are where that optimism lives. Gross margin expanded 130 basis points to 73.6% last quarter and operating margin climbed 150 basis points to 18.5%, prompting management to lift its full-year operating margin expansion target to 60 to 80 basis points. The key ingredient has been average unit retail, which rose 15% in the first quarter and has posted double-digit gains for several straight quarters. Management now expects mid-to-high single digit AUR growth for the year, up from a more normalized mid-single digit view. Another strong pricing print with stable gross margin would validate the idea that the brand's elevation strategy has real staying power, while a sharp AUR slowdown would suggest the easy gains are behind it. Tariffs remain the swing factor, though the first half carries the lighter roughly 10% assumption, so the bigger cost pressure should land later.
Geography will tell the demand story. Asia rose 25% last quarter with China up more than 40%, and the region's full-year guide was nudged higher. China is expected to cool toward mid-teens growth in the back half, so a still-robust second quarter would reassure. Europe is the weak link, with retail comps up just 1% amid soft traffic, energy costs and Middle East disruption. Stabilization there would ease worries; further slippage would challenge management's prudent low-to-mid single digit view. Early read-throughs on the Korea app launch and new key-city stores could also hint at future growth runways, and any detail on how quickly off-price and lower-tier doors are being exited will shape back-half expectations.
The market has modestly rewarded the beat-and-raise. Shares are up 4.3% since the last report while the S&P 500 is essentially flat, and at $391.25 the stock trades comfortably above its 200-day moving average of $366.47 and in the upper half of its post-earnings range, about 5% below the $411.19 high. Sentiment has edged up slightly to 48.3% bullish from 46.3%, hardly euphoric. That combination suggests confidence without a fully priced-in blowout.
Ultimately, the quarter hinges on whether pricing power and Asian strength can offset the fading wholesale boost, a stronger dollar and a sluggish Europe. If margins expand in line with the raised plan and management reaffirms or nudges the full-year outlook despite those headwinds, the on-offense narrative stays intact. If growth decelerates more than expected or the margin guide stalls, last quarter's surge may start to look like the peak rather than the new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-23 | |
| Oct-22 | |
| Oct-16 | |
| Oct-15 | |
| Oct-12 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 | |
| Oct-02 | |
| Sep-30 | |
| Sep-29 |
