Sony Faces A Margin Test As Profit Is Expected To Grow On Shrinking Revenue
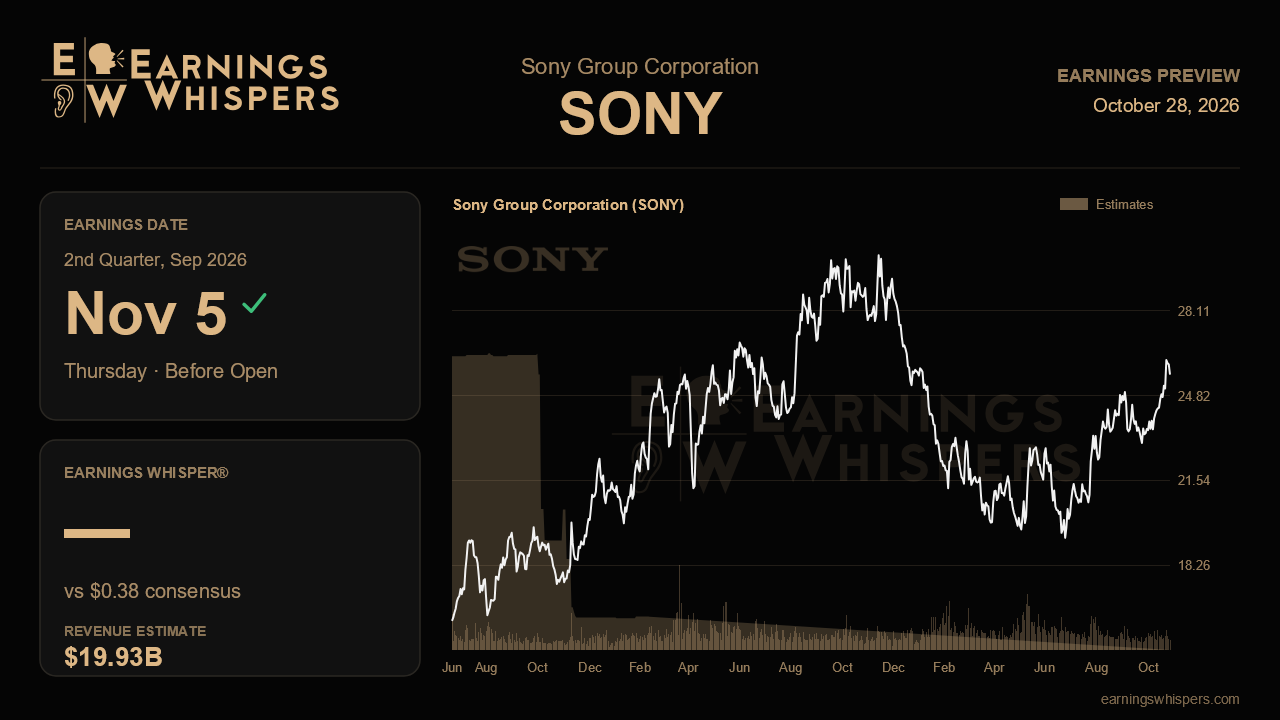
Sony heads into its fiscal second-quarter report with an awkward-looking equation that the market seems willing to embrace: less revenue, more profit. Wall Street expects the Japanese entertainment and electronics conglomerate to earn $0.38 per share on revenue of about $19.93 billion when it reports before the open on November 5. That would be an 8.6% gain in earnings from the $0.35 a share earned a year earlier, even as sales fall 5.4% from $21.08 billion. A company that can grow its bottom line while its top line contracts is either getting better at turning revenue into profit or benefiting from a favorable shift in what it sells. This report should show which explanation holds.
The sequential picture adds a useful wrinkle. Last quarter Sony posted $0.36 a share on $17.81 billion in revenue, so consensus calls for a meaningful step up in sales from the prior period alongside only a modest two-cent rise in earnings. In other words, analysts are not banking on dramatic operating leverage from the quarter-over-quarter revenue increase. That makes the year-over-year comparison the more interesting one. The Street is effectively assuming that Sony's profit per dollar of revenue improves materially versus a year ago, and the report needs to show where that improvement comes from. Because Sony reports in yen and these figures are expressed in dollars, currency translation can also blur the revenue trend, so the underlying operating story matters more than the headline sales number.
The breadth of Sony's portfolio is what makes this setup plausible and also what makes it tricky. The company spans gaming consoles and software, music, motion pictures and television, image-based semiconductors and consumer electronics. Those businesses carry very different margin profiles. Revenue from recurring, content-driven businesses tends to be far more profitable than hardware sales, so a quarter in which lower-margin hardware revenue fades while higher-margin content and services hold steady could produce exactly the pattern analysts are modeling. Confirmation would look like earnings meeting or beating the $0.38 estimate without help from one-time items. A challenge would be a revenue shortfall that also drags down earnings, which would suggest the decline reflects weakening demand rather than a healthier mix.
There is no fresh company guidance to measure the consensus against, which places extra weight on the release itself and any update to Sony's full-year outlook. If management reaffirms or lifts its annual targets, the market will likely read the revenue decline as manageable. If it trims them, the profit-growth narrative embedded in current estimates would come under pressure quickly.
Sentiment has swung notably more constructive. Earnings Whispers readings show a 29.0% bullish tilt heading into this report, a sharp reversal from a 17.1% bearish reading before the previous one. The stock has followed suit, rising 7.3% since the last report versus a 3.4% gain for the S&P 500, outperforming by roughly 4 percentage points. At $25.64, shares trade well above their 200-day moving average of $22.29 and sit within about 3% of their post-earnings high of $26.31, near the top of a range that bottomed at $22.22. The stock is effectively testing a breakout, which means the bar has risen. Improved mood and price action leave less room for a merely adequate quarter.
The central question is whether Sony can prove that its earnings growth is structural rather than incidental. If profits rise as expected while revenue contracts, and the explanation points to a durable shift toward higher-margin businesses, the recent rally has a solid foundation and a push through resistance becomes credible. If instead the revenue decline bleeds into margins or the outlook softens, the newfound optimism could unwind just as quickly as it arrived.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 | |
| Oct-14 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-05 | |
| Oct-05 | |
| Sep-24 | |
| Sep-03 | |
| Sep-01 | |
| Aug-27 | |
| Aug-26 |
