Steve Madden Faces A Tariff-Free Comparison, But Freight And Margins Will Decide The Quarter
Steve Madden heads into its third-quarter report with about as friendly a comparison as a footwear company could ask for. A year ago, the company was absorbing 145% tariffs on Chinese goods, fielding order cancellations and watching gross margin lose several hundred basis points. That quarter is now the base, and Wall Street expects a big rebound against it. The harder question is whether the margin story management told last quarter can survive rising freight costs, a lingering Middle East conflict and gross margin tailwinds that are starting to fade.
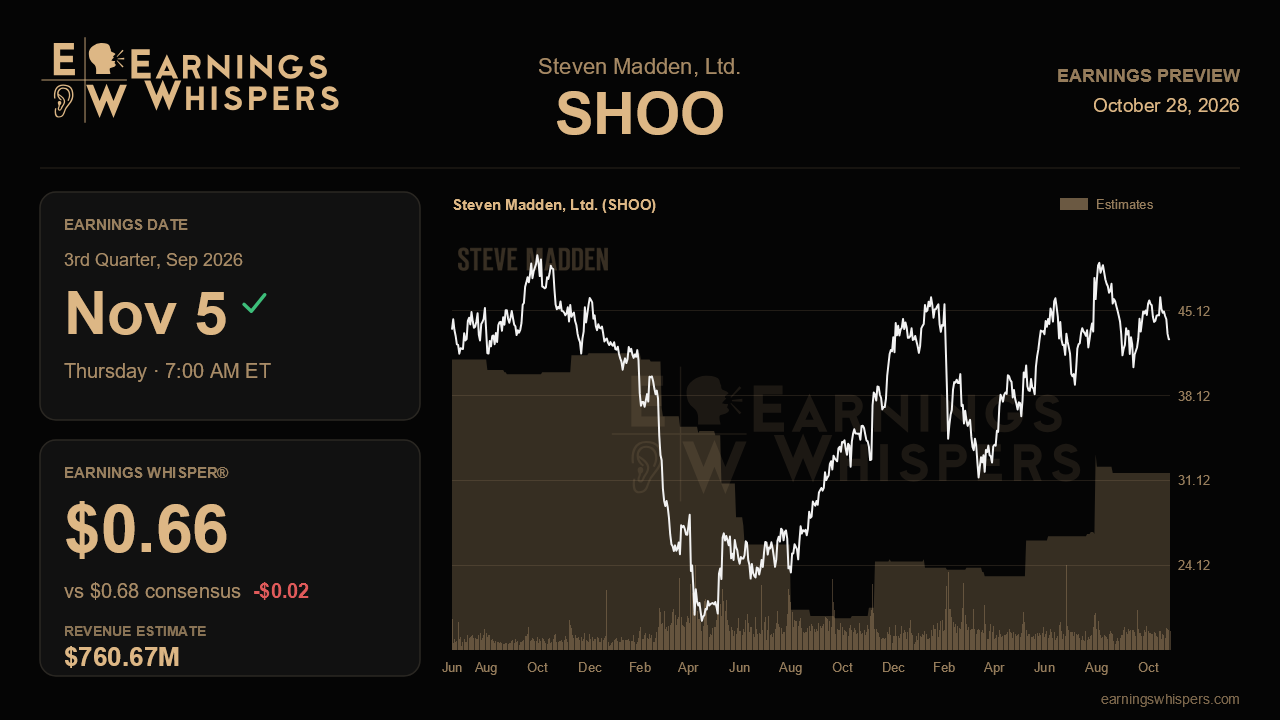
Consensus calls for earnings of $0.68 per share on revenue of $760.7 million. That works out to roughly 58% EPS growth and nearly 14% sales growth. The revenue figure deserves attention. Kurt Geiger was acquired in May 2025, so the year-ago quarter already included it, and the acquisition no longer inflates the growth rate. A 14% gain would therefore point to real organic strength, faster than the 11% ex-Kurt Geiger growth reported in the second quarter. The Earnings Whisper sits at $0.66, a touch below consensus. The gap is small, but it suggests the more informed expectations are not leaning toward an easy beat.
Management has raised its full-year outlook at each step this year. Revenue growth guidance went from 9% to 11% after the fourth quarter, to 10% to 12% after the first, and to 11% to 13% last quarter. EPS guidance, which had been pulled entirely during the tariff chaos, came back at $2.00 to $2.10 and now stands at $2.05 to $2.15. The Street's $2.11 estimate sits in the upper half of that range. Analysts are clearly giving the company credit for its momentum, and that raises the bar for another increase.
The second-quarter call gave plenty of reasons for confidence. Gross margin jumped 460 basis points to 46.5%, and branded wholesale rose 20%. Steve Madden comps climbed 17% in the US, and the brand's handbags returned to 30% growth. Online searches for the brand have also accelerated sharply over three quarters. That set of results earned higher outlooks for both Steve Madden and Dolce Vita. Validation this quarter would look like branded wholesale strength persisting past the Nordstrom Anniversary window and gross margin still expanding year over year. Management did warn that the size of that gain would narrow as pricing, Kurt Geiger mix and private-label mix begin to lap.
The risks are concrete. Management built in about six cents of extra back-half freight cost, driven by air shipments to chase best-sellers and ocean disruptions tied to the Iran conflict. Supplier cost pressure is also creeping into margin. International comps were held to 1% as Gulf markets fell about 40%, and private label is still expected to decline by mid-to-high teens this year. Any sign that freight or supplier costs are running ahead of plan would undercut the margin narrative quickly. So would commentary that leans on fourth-quarter tariff assumptions, which are still modeled at 15% pending Section 301 reviews. Kurt Geiger updates on the Macy's rollout that began in October and on the India launch slated for the fourth quarter will shape views on next year more than on this quarter.
The market has not paid for the guidance raises. Shares are down about 5% since the last report, while the S&P 500 gained nearly 5%. At $42.78, the stock sits just above its 200-day moving average and toward the lower end of its post-earnings range of $40.38 to $49.70. Bullish sentiment has also cooled, slipping to 29.7% from 35.1% a quarter ago. The setup is a company with improving fundamentals and a skeptical audience. The verdict will likely depend less on top-line growth than on gross margin. If Steve Madden can show that strong full-price demand is absorbing freight and supplier costs without derailing year-over-year margin gains, the recovery story stays intact. If costs start eating the upside, the Street's position near the top of guidance will look stretched.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-13 | |
| Oct-02 | |
| Sep-11 | |
| Aug-12 | |
| Aug-05 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-28 | |
| Jul-16 | |
| Jun-30 | |
| Jun-16 |
