Shake Shack's Traffic Is Strong, But Beef Costs Will Decide Its Third Quarter
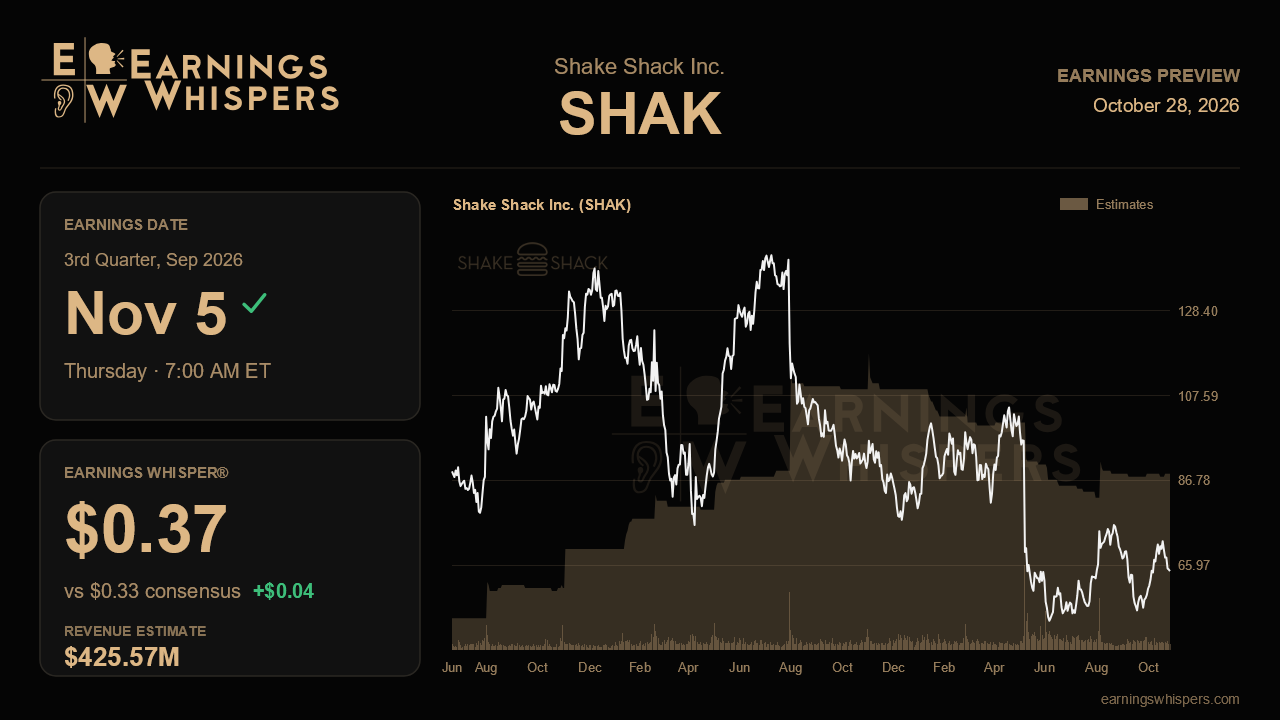
Shake Shack heads into its third-quarter report with an unusual split personality. Customers keep showing up, with 22 straight quarters of positive same-shack sales and four consecutive quarters of traffic gains, yet the company's profit outlook has been moving in the wrong direction. A record run-up in beef prices pushed management to steer full-year adjusted EBITDA to the low end of a range that had already been trimmed, and it stopped offering quarterly guidance altogether. That leaves the November 5 release, due before the opening bell, as the first clean look at how much of the cost shock is landing on the bottom line.
Wall Street expects earnings of $0.33 a share, down about 8% from $0.36 a year ago, on revenue of roughly $425.6 million, up nearly 16%. That gap between double-digit sales growth and shrinking profit is the whole story in miniature: new restaurants are filling the top line while commodity and distribution costs eat the margin. The revenue estimate also implies only a modest step up from the second quarter's $417.6 million, which looks achievable given the pace of openings. Management's full-year revenue range of $1.60 billion to $1.70 billion brackets the $1.65 billion consensus right at the midpoint, so the Street is not leaning on anything heroic for sales. The Earnings Whisper of $0.37, a meaningful four cents above consensus, suggests some investors think the official estimates have been cut too far.
Whether that optimism holds depends largely on restaurant-level margin. It came in at 23.0% last quarter, down 90 basis points from a year earlier and below what management had targeted. Beef peaked in June at mid-teens inflation and was expected to stay elevated through the back half, while fuel and distribution costs added pressure. Crucially, the company chose not to fully pass these costs through to menu prices, preferring to protect its value positioning against aggressive fast-food competition. A margin that stabilizes near second-quarter levels would validate that trade-off; another meaningful year-over-year decline would raise doubts about even the low end of the $225 million to $235 million EBITDA range.
Demand is the other half of the test. Second-quarter comps rose 3.5% with roughly 90 basis points of help from World Cup promotions, and management pushed back firmly on the idea that sales were fading as the quarter closed, pointing to June as the strongest stretch. Without that event tailwind, and against tougher comparisons as the company laps last year's marketing spending, holding positive traffic would be strong evidence that the West Coast-inspired menu, the permanent Big Shack and a surging app channel are doing real work. Unit growth should remain a bright spot, with a 60 to 65 opening target for the year after record first and second quarters. Licensing deserves a glance too, since the Middle East conflict has weighed on the company's highest-volume licensed region.
Sentiment has warmed noticeably, rising to about 30.5% bullish from roughly 10.2% before the last report, yet the stock has not followed. Shares are down 3.7% since the prior release, trailing the S&P 500 by about three points, and at $64.54 they sit well below the 200-day moving average near $75.57, roughly in the middle of a post-earnings range between $54.73 and $76.41. That combination suggests a market that likes the brand but wants proof on profitability.
The defining question is whether Shake Shack can show that beef inflation is a temporary squeeze rather than a lasting reset in earnings power. Steady traffic plus a margin that has found its floor would keep the growth narrative intact and give the new finance chief a credible foundation for revisiting the shelved long-term targets. Further margin erosion, especially paired with softer comps, would confirm the market's skepticism.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 11 hours | |
| Oct-23 | |
| Oct-15 | |
| Oct-14 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-01 | |
| Sep-30 | |
| Sep-16 | |
| Sep-16 | |
| Sep-09 | |
| Sep-08 | |
| Sep-01 |
