Tripadvisor Must Show Viator's Summer Slump Was Transitory As Bears Pile In
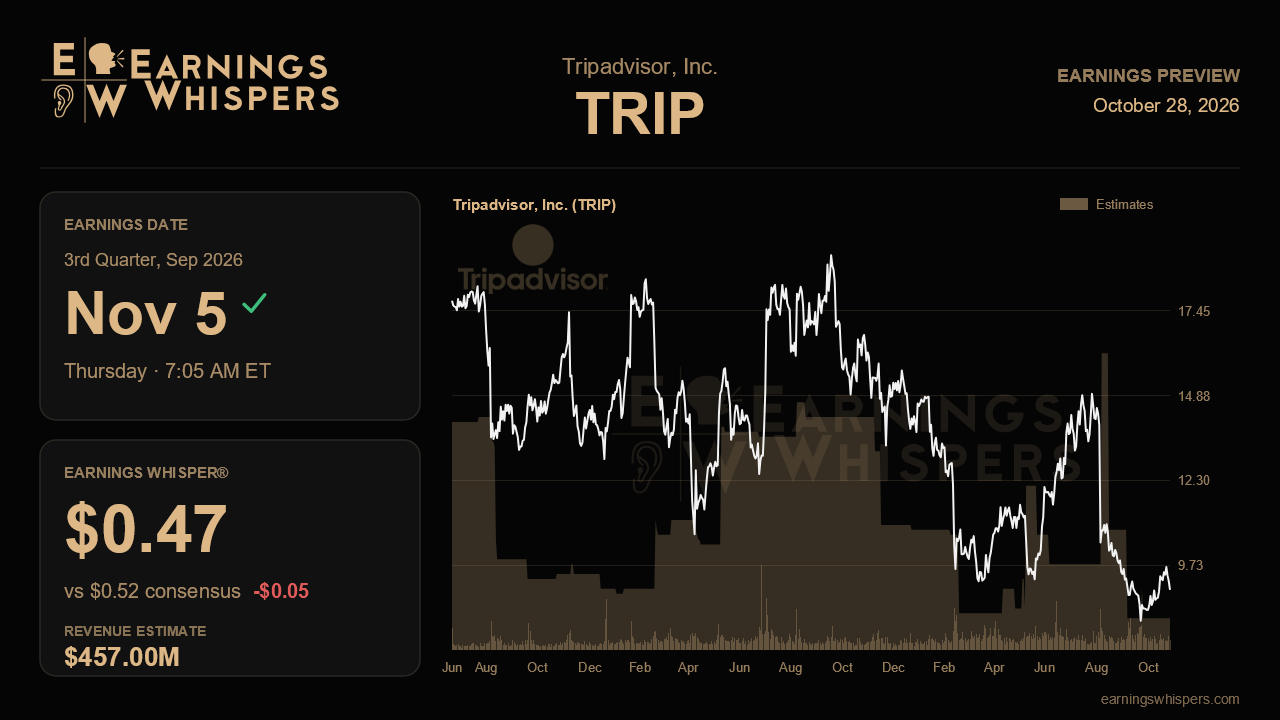
Tripadvisor heads into its third-quarter report with its own explanation on trial. Three months ago, management blamed a softening experiences business on weather cancellations, a weaker US-to-Europe travel corridor and customers trading down to cheaper tours. It called those pressures transitory rather than structural and set a deliberately prudent outlook. The November 5 release, due before the open, is the first real test of whether that framing holds, or whether the slowdown that began in March has become the new baseline.
The Street is looking for non-GAAP earnings of $0.52 per share on revenue of about $457.0 million. That revenue figure would be roughly 17.4% below the $553.0 million reported a year ago. Earnings, meanwhile, are expected to rise from $0.41. A contraction that steep sits awkwardly beside the roughly flat full-year revenue outlook management offered in the spring. That gap points either to a changed business mix or to a much harsher demand picture, and the release needs to make clear which one investors are dealing with. The Earnings Whisper of $0.47 sits meaningfully below consensus. That suggests the market is braced for a profit shortfall and that clearing the published estimate is not assumed.
The arc of the past three calls explains the caution. Late last year, management described an exit rate of 18% bookings growth and promised accelerating low-teens experiences revenue in 2026. In the first quarter, strong January and February gross booking value growth was interrupted by Middle East conflict and disruption in Mexico and Hawaii. That forced a cut to roughly flat consolidated revenue and margins. By the second-quarter call, Viator's point-of-sale growth had cooled to the mid-teens, July was described as uneven, and management admitted it could not predict when conditions would normalize. Each update has lowered the bar, so the key question now is whether this one finally holds steady.
The evidence that would validate management's story is fairly specific. Experiences bookings would need to stabilize or improve as the summer weather issues fade. Booking values would need to show the trade-down to lower-priced tours easing. Management would also need to back its claim of durable fall intent with actual autumn trends rather than hope. Margins matter too. The roughly $85 million in annualized cost savings and the earlier target of 300 to 400 basis points of experiences margin expansion should provide some cushion against soft revenue. If profitability slips alongside demand, the operating-model overhaul will look far less protective than advertised. A further decline in Viator growth, or commentary that international softness is spreading, would challenge the transitory thesis outright.
The strategic threads offer potential offsets but no quick fix. Tripadvisor has been the first partner to integrate with Google Gemini and has deals with OpenAI, Perplexity, Microsoft, Amazon and Anthropic. Traffic from AI sources is growing quickly, but it remains small next to historic search. Any quantification of that channel would be welcome. Progress on the portfolio review, including strategic alternatives for The Fork, could reshape the story faster than any operating metric.
The market has already rendered a harsh preliminary verdict. Shares have fallen 17.9% since the last report while the S&P 500 was essentially flat. At $8.98, the stock sits well below its 200-day moving average of $11.11 and much closer to its post-earnings low of $8.02 than its high of $11.93. That entire range sits beneath the prior quarter's band. Sentiment has also turned more bearish, at 33% compared with 22% heading into the previous report. Depressed expectations lower the hurdle, but they do not supply a catalyst. Ultimately, the report hinges on whether experiences demand shows signs of bottoming. Without that evidence, management's transitory language will be hard to defend for another quarter.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-20 | |
| Oct-05 | |
| Sep-28 | |
| Sep-24 | |
| Sep-24 | |
| Sep-22 | |
| Sep-22 | |
| Sep-15 | |
| Sep-02 | |
| Aug-24 | |
| Aug-19 | |
| Aug-18 | |
| Aug-11 |
