US Foods Must Prove Independent Restaurant Momentum Can Outrun Fading Q2 Tailwinds
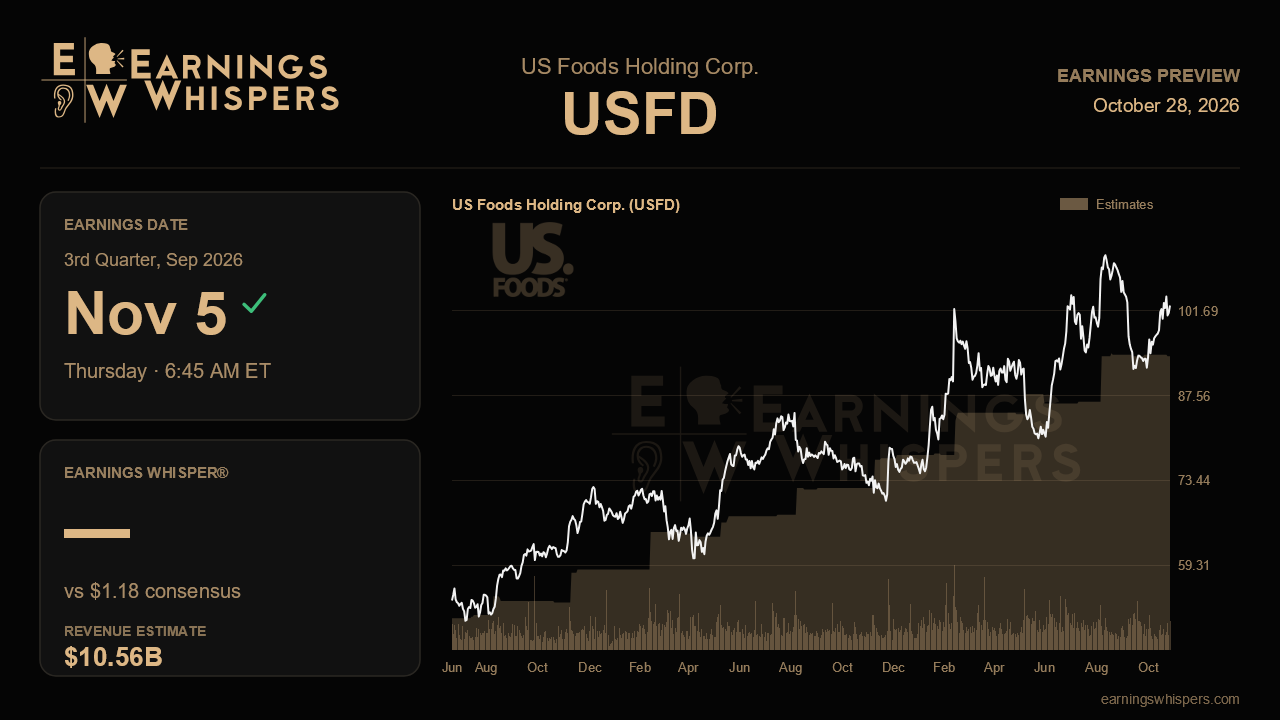
US Foods heads into its third-quarter report with an unusual disconnect. Management just delivered what its CEO described as the strongest quarter of his tenure, with independent restaurant volume accelerating for a fifth straight period and adjusted EBITDA margin hitting a record. Yet Wall Street's full-year earnings forecast sits at the very bottom of the company's reaffirmed range, and the stock has lagged the market since that upbeat report. The September quarter will help show which view is right.
Analysts expect earnings of $1.18 per share on revenue of about $10.56 billion. That revenue figure implies growth of roughly 3.6% from a year ago. Steady, but hardly a sprint. The earnings picture is more impressive: against $1.00 in the year-ago quarter, consensus points to growth near 18%. That gap between sales and profit growth is the heart of the US Foods story. Management is trying to squeeze more profit out of every case through procurement savings, cheaper indirect costs and productivity tools. For the full year, the company still expects adjusted EPS of $4.70 to $4.94 on revenue of $41.0 billion to $41.79 billion. The Street's $4.70 EPS estimate hugs the low end even though its $41.43 billion revenue forecast sits near the middle. In other words, analysts believe the sales but doubt the margin expansion will fully carry through.
That skepticism has some basis, and management itself supplied it. Part of the second-quarter EBITDA beat came from timing: fuel cost recovery ran near 70%, far above the usual 30% to 40%, and some vendor management gains were pulled forward. Executives also warned that gross profit per case growth would moderate in the third quarter as the company laps last year's Food Fanatics event. Elevated fuel costs drove about a third of the rise in operating expense per case. The new fully variable seller compensation plan, which went live company-wide in June, is expected to lift selling costs for a couple of quarters. A softer margin print this quarter would therefore not be a surprise. The real question is whether it looks like the expected timing pause or something more stubborn.
The volume side offers the cleanest test of the bullish narrative. Independent case growth climbed from 3.9% to 4.1%, then 4.6%, then 5.1% over the past four quarters, while net new account generation was the best in three years. Holding that pace, or extending it, while restaurant foot traffic stays soft would suggest the comp overhaul and new AI sales tools are winning share rather than disrupting the salesforce. Early signs on attrition were flat, so any slippage in independent growth would raise fair questions about the transition. Chain volume, down 1.5% last quarter, is a secondary watch point. Further updates on Pronto, now expected to reach about $1.3 billion in 2026 and more than $1.7 billion in 2027, would show whether that small-market delivery push is tracking ahead of plan.
Sentiment has edged slightly more bearish than it was heading into the last report, and the stock's 2.6% decline since then, against a roughly flat S&P 500, shows that the record quarter did not earn much credit. At $102.57, shares remain well above the 200-day moving average of $94.08. They sit in the upper half of their post-earnings range but still about 8% below the $111.42 high, so this is not a breakout setup.
Ultimately, this report turns on whether US Foods can show that its record margins reflect durable self-help rather than a fortunate fuel quarter. Sustained independent case acceleration, cost savings on track toward the $300 million-plus target, and a full-year outlook that holds firm would argue the Street is too conservative at the bottom of guidance. A stall in independent volume alongside heavier comp and fuel costs would suggest the market's caution was warranted.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 | |
| Oct-02 | |
| Sep-29 | |
| Sep-26 | |
| Sep-25 | |
| Sep-25 | |
| Sep-25 | |
| Sep-25 | |
| Sep-24 | |
| Sep-21 | |
| Sep-18 |
