Vericel Must Prove Its Second-Half Macy Slowdown Is Caution, Not Reality
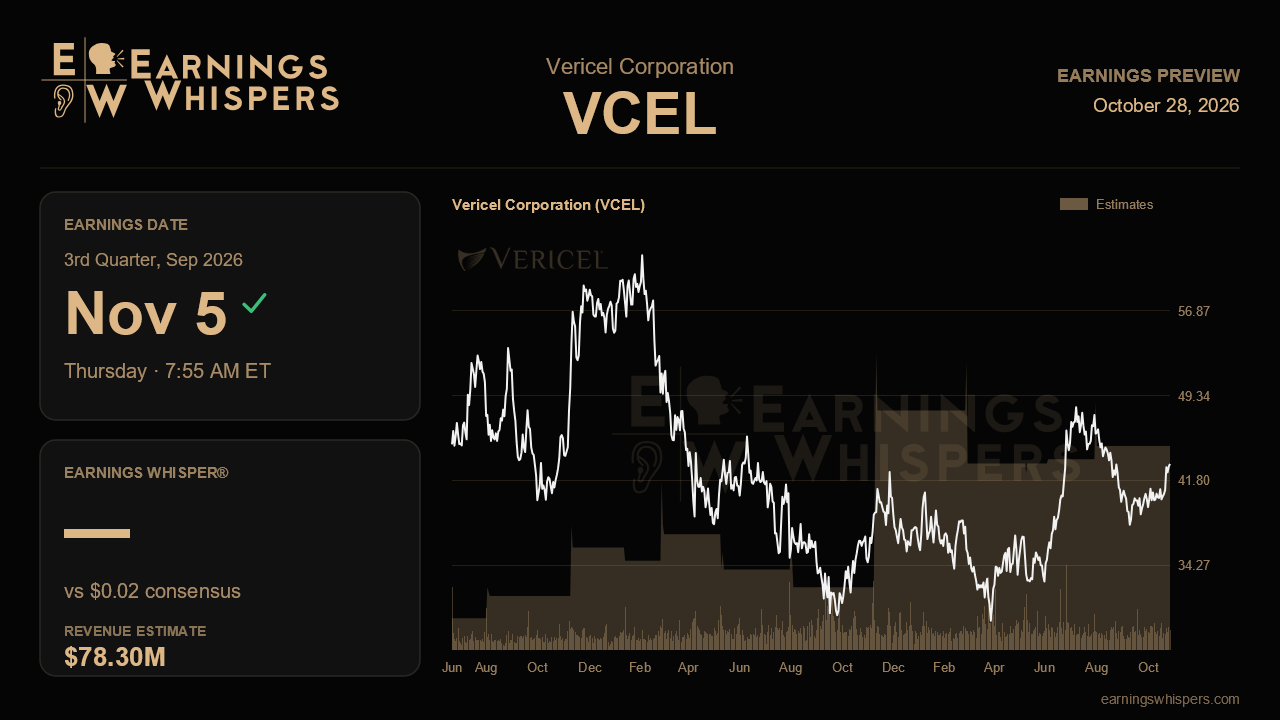
Vericel enters its third-quarter report with an odd disconnect. The company has raised its full-year outlook three times, posted five straight quarters of 20%-plus growth in its Macy cartilage repair franchise and authorized its first-ever share buyback, yet the stock has dropped 11.5% since the last report while the S&P 500 gained 4.6%. Investors appear to be focusing less on the record first half and more on the slowdown baked into management's second-half math.
Wall Street expects revenue of about $78.3 million, up 16% from $67.5 million a year ago and only modestly above the $77.5 million record set last quarter. Earnings are a different story. Consensus calls for a profit of just $0.02 a share, down 80% from $0.10 a year earlier. That decline is mostly by design. Management has called 2026 a transition year, absorbing costs from a new manufacturing facility, an expanded sales force, the ankle trial and international expansion. Gross margin guidance of about 75% and adjusted EBITDA margin of roughly 27% were left unchanged last quarter, with meaningful operating leverage pushed to 2027 and beyond. A thin bottom line should not shock anyone. A further slip in those margin targets would.
The revenue outlook is where the real test lies. Vericel now guides to $330 million to $340 million for the year, and the consensus of $330.9 million sits near the bottom of that range. In other words, the Street is not betting on another raise. Management's own framework implies Macy revenue of roughly $65.5 million in the third quarter, essentially flat with the second quarter and consistent with high-teens growth rather than the 22% to 23% pace of the first half. Executives described that assumption as a prudent, unchanged method rather than a forecast of weakening demand, and hinted that internal expectations are higher. This report is the first real chance to check that claim. If Macy growth stays near 20% or better, the conservative framing is validated and the low-end consensus looks stale. If growth lands in the mid-teens, the deceleration narrative gains credibility.
The drivers management cited for Macy's acceleration deserve close attention. The 25 new sales territories added across three regions are now fully in place, and Macy Arthro, the arthroscopic delivery option, plus commercial excellence efforts were credited with lifting trailing growth from 19% to 23%. Continued expansion in surgeon adoption and biopsy activity would suggest those investments are still compounding. Burn Care offers a secondary swing factor. Guidance there has climbed from $36 million to $40 million at the start of the year to $46 million to $50 million, helped by the BARDA contract, and Nexabrid just set a quarterly record of $1.5 million with about 80 ordering centers. Further progress would support the argument that Vericel is no longer a single-product story. Updates on the UK marketing application, ankle study enrollment and early buyback activity will round out the picture.
Sentiment has soured noticeably, with the bearish reading nearly doubling from the prior quarter. The shares at $43.27 sit roughly midway between the post-report low of $37.35 and high of $49.32, and remain comfortably above the 200-day moving average near $38.58. That leaves room to move in either direction without a clear technical signal.
The central question is simple. Was the second-half slowdown in guidance an act of caution, or a warning? A Macy quarter that outpaces management's implied run rate, paired with steady margins and a fourth guidance increase, would keep the beat-and-raise narrative intact and make the recent selloff look premature. A quarter that merely matches the conservative framework could confirm the market's suspicion that peak growth has passed.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Sep-22 | |
| Sep-08 | |
| Aug-03 | |
| Jul-30 | |
| Jul-16 | |
| Jul-16 | |
| Jul-02 | |
| Jun-09 | |
| May-07 | |
| Apr-23 | |
| Apr-02 | |
| Mar-09 | |
| Mar-04 |
