Vontier Needs Margins And Buybacks To Carry Q3 As Sales Guidance Points Lower
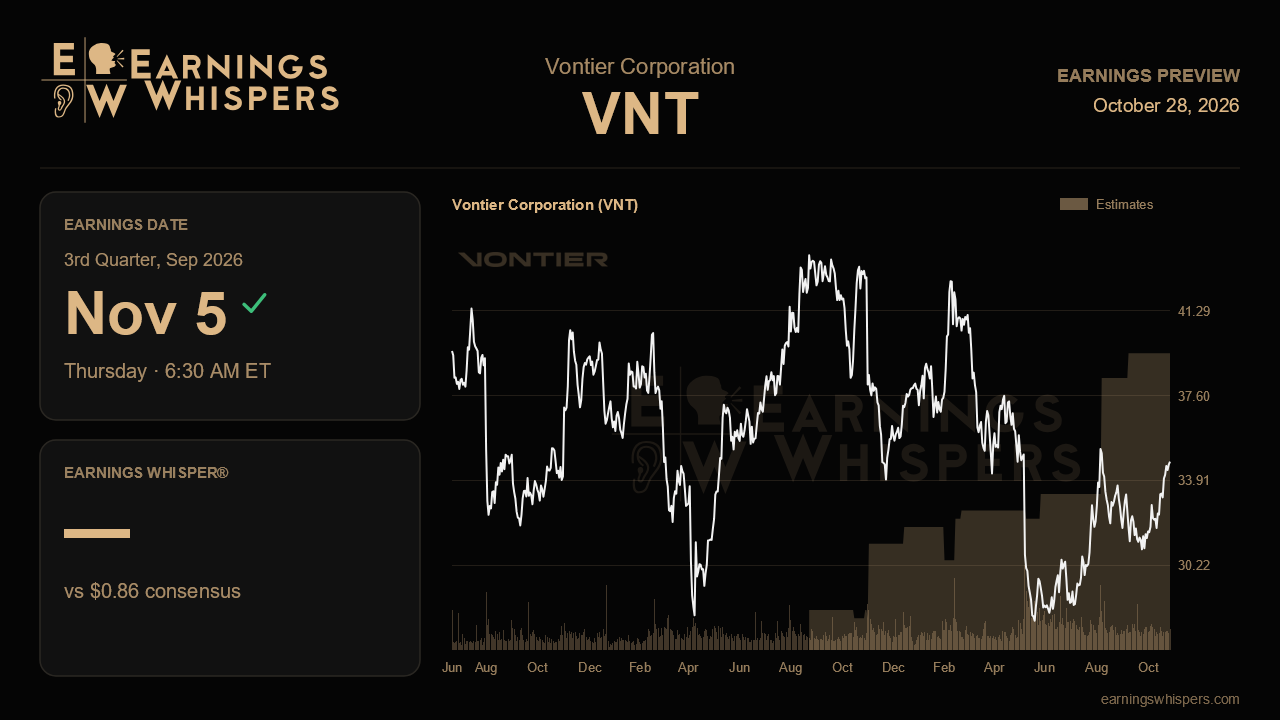
Vontier enters its third-quarter report with an awkward split between its earnings story and its sales story. Management raised its full-year profit outlook last quarter and spoke with noticeably more confidence about a path to double-digit earnings growth. Yet its own third-quarter revenue guidance of $720 million to $735 million sits below the $752.5 million it booked a year ago. That means per-share growth this quarter has to come from cost discipline, mix and a much smaller share count rather than from volume. The November 5 release, due before the open, will show whether that formula is holding.
The Street is looking for $0.86 a share, roughly 10% above last year's $0.78 and right at the top of management's $0.82 to $0.86 range. That is a full but not reckless bar. Analysts are giving full credit for execution without assuming upside beyond the guidance. Oddly, the full-year consensus of $3.39 sits below the raised $3.45 to $3.55 annual outlook. It is not even inside the prior $3.35 to $3.50 range by much. Some skepticism about the back half appears to remain, which leaves room for a fourth-quarter guide that simply holds the line to reassure.
The operating checklist comes straight from last quarter's call. Environmental and Fueling Solutions was the standout, with core growth near 5% and double-digit dispenser growth. That earned a lift in the segment's annual outlook to mid-single digits. Continued dispenser strength and further uptake of the FlexPay 6 terminal would validate that upgrade. FlexPay 6 was already attached to about a quarter of new dispensers. Mobility Technologies is the more delicate test. The roughly $25 million vehicle-identification comparison headwind that weighed on the first half should now be gone, and management guided the third quarter to about 5% core growth. Hitting that number matters, because the segment's full-year growth target has already been trimmed twice. Car-wash software migrations are slipping on permitting delays, and well over 90% of the installed base remains on legacy systems. Any sign that those conversions are slipping further would undercut the recurring-revenue narrative.
Repair Solutions is where the story could crack. The segment missed its margin plan by about $1.5 million last quarter, and its annual operating profit was cut by $7 million to $8 million. Management now expects segment margin to fall about 150 basis points for the year, and new leadership has been brought in from NAPA to fix it. A further slide would put pressure on the companywide margin expansion target, which was already lowered to about 100 basis points from 130. Memory-chip inflation adds another cost headwind that pricing has only partly offset. On the positive side, savings were tracking ahead of the $15 million target, and early contribution from the ECOS fleet-energy acquisition would support the connected-software pitch. Buybacks also help: about $200 million had been repurchased by midyear against a full-year assumption near $250 million.
The market has not given management much credit for the raise. Shares have slipped 4.2% since the last report while the S&P 500 was essentially flat. Sentiment has also soured, with the bearish reading deepening to 32.9% from 19.4% a quarter ago. At $34.73, the stock sits modestly above its 200-day average but roughly 5% below its post-earnings high of $36.58. It has recovered well off the $30.43 low without challenging the top of the range.
The central question is whether Vontier's higher earnings forecast reflects durable operating improvement or mainly financial engineering and cost cuts layered over softer revenue. Firm fueling demand, a clean Mobility Technologies rebound and stabilizing Repair Solutions margins would support the confident tone from last quarter. Another round of segment trims would suggest the buybacks are doing too much of the work.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-16 | |
| Oct-15 | |
| Oct-08 | |
| Oct-05 | |
| Oct-02 | |
| Sep-18 | |
| Sep-18 | |
| Sep-04 | |
| Aug-26 | |
| Aug-25 | |
| Aug-13 | |
| Aug-13 | |
| Aug-06 | |
| Aug-06 |
