NCR Voyix Needs Retail Platform Gains To Outrun A Sagging Restaurant Business
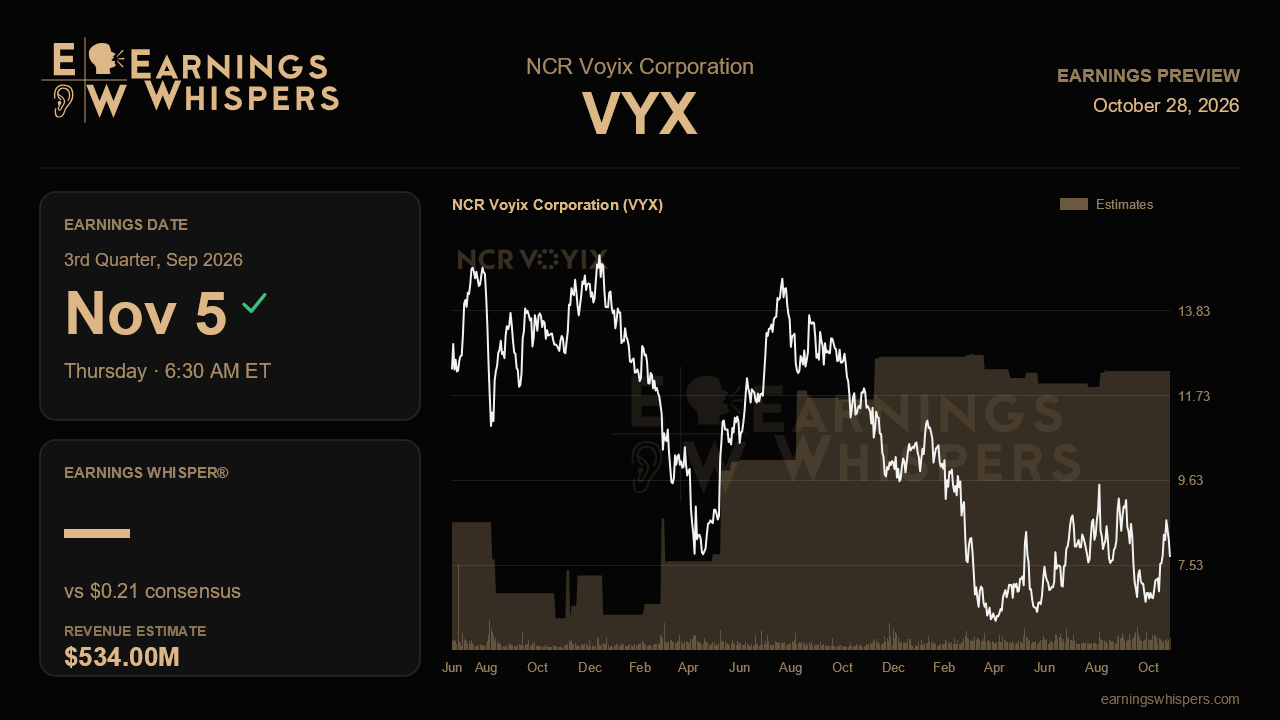
NCR Voyix enters its third-quarter report with a split personality that the market has so far chosen to judge by its weaker half. On the last call, management reaffirmed its full-year outlook and pointed to real traction in retail software, yet the stock has fallen 18.2% since then while the S&P 500 slipped less than 1%. The November 5 release, due before the open, is a test of whether the retail platform story can carry enough weight to offset a restaurant segment that has been losing altitude.
The Street is looking for earnings of $0.21 per share on revenue of about $534 million. That would be a solid sequential step up from the $0.11 and $523 million posted last quarter, but well below the $0.27 and $684 million of a year ago. The roughly 22% revenue decline is less alarming than it looks, since the company has been reshaping its portfolio, including the Brazil divestiture, and leaning away from hardware. The more telling comparison is guidance. Management still expects 2026 adjusted earnings of $0.89 to $0.92 per share on revenue of $2.188 billion to $2.303 billion, and consensus sits at $0.89 and $2.20 billion, both hugging the bottom of those ranges. In other words, analysts are not doubting the guidance outright, but they are not giving management much benefit of the doubt either. A quarter that keeps the company tracking toward the midpoint would quietly reset that skepticism.
Retail is where the validation must come from. Last quarter, retail revenue excluding hardware rose 4%, recurring software jumped 15%, and segment EBITDA climbed 20% to $97 million with a 350 basis point margin gain. The Voyix Commerce Platform has become the core proof point: signed contracts rose from 21 to 25, ten customers were live across more than 2,000 lanes, and management expected roughly another 1,000 lanes by the end of September. That lane target is the cleanest checkpoint in this report. Hitting it would suggest the faster, fully remote installation approach and the new AI migration tools are actually compressing the time between signing a deal and booking revenue. Remaining contract value, which slipped from $293 million to $286 million sequentially, also deserves scrutiny. Management has warned the figure moves unevenly as contracts convert to revenue, which is fair, but another decline without a corresponding jump in recognized software revenue would be harder to explain away.
Restaurants are the swing factor. Revenue excluding hardware fell 6%, EBITDA dropped 15% to $58 million, and margins shrank 380 basis points, hurt by delayed hardware refreshes, lingering small-business softness that dates back to late 2025, and the Brazil exit. Software growth of just 3% excluding Brazil was a modest improvement from flat, so any further acceleration would matter. The Pizza Ranch win for Aloha Next and the upcoming store-in-a-box offering for smaller operators are encouraging, but they are early. Meanwhile, memory chip inflation of $20 million to $30 million, passed through as higher prices, has caused customers to defer hardware purchases, a drag management expects to linger into 2027. Any sign that this pullback is spreading or deepening would pressure both revenue and the guidance range.
Sentiment has edged only slightly more bearish than before the last report, so the gloom is not new, but the share price tells a harsher story. At $7.73, the stock sits just under its 200-day moving average and in the lower part of its post-earnings range of $6.53 to $10.14, reflecting a market that has priced in more disappointment than the reaffirmed guidance implies.
The central question is simple: can retail margin expansion and live platform deployments grow fast enough to absorb restaurant weakness while keeping the year on track? If lane rollouts hit plan and restaurant declines stabilize, the reaffirmed outlook looks credible and the selloff overdone. If restaurants slide further and guidance drifts toward its floor, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-14 | |
| Oct-14 | |
| Oct-06 | |
| Oct-01 | |
| Aug-13 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 |
