Advanced Drainage Faces Its Resin Test As Margin Squeeze And Pull-Ahead Payback Arrive
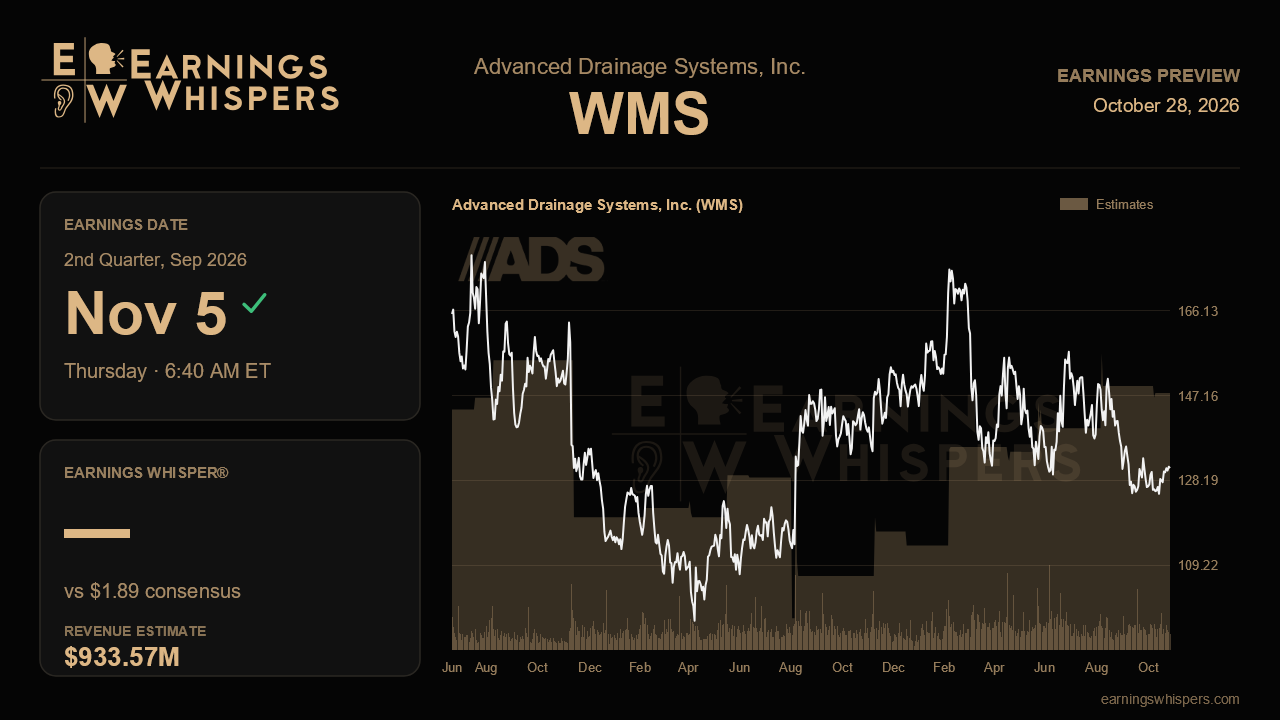
Advanced Drainage Systems spent last quarter telling investors, in effect, not to get used to it. The company posted its first billion-dollar quarter and a 35.8% adjusted EBITDA margin, then immediately warned that the two things flattering those numbers, cheap inventory carried at older material costs and customers buying early ahead of price increases, would both reverse in the September quarter. The report due before the open on November 5 is where that warning either plays out as scripted or proves to be understated.
Wall Street is braced for a step back on profit. Consensus calls for earnings of $1.89 per share, down about 4% from $1.97 a year ago, on revenue of roughly $933.6 million, up nearly 10%. That gap between rising sales and falling earnings tells the story. Much of the top-line growth reflects acquired revenue, with the NDS business contributing around $95 million in the June quarter. Meanwhile, the $25 million to $30 million of stormwater and non-residential orders pulled into the prior quarter leaves a hole in this one. Management has guided the sequential margin decline to exceed its usual seasonal drop of about 300 basis points. From 35.8%, that points to a margin below the 33.8% posted a year ago, which squares with the Street's lower EPS figure.
The full-year frame has not budged. Management reaffirmed fiscal 2027 revenue of $3.35 billion to $3.55 billion and adjusted EBITDA of $1.0 billion to $1.05 billion, the same ranges set when the year began. Consensus revenue of $3.45 billion sits exactly at the midpoint, so analysts are neither stretching nor hedging. The question is whether a heavier-than-normal margin hit in the second and third quarters still leaves room to land inside the EBITDA range. If the company holds guidance again after absorbing peak resin costs, that is a meaningful vote of confidence. A trim, particularly to EBITDA, would suggest the inflation management called dynamic is outrunning its pricing.
Pricing is the swing factor. Management said price increases are only offsetting inflation dollar for dollar, which protects profit dollars but dilutes margin percentages by design. Transportation costs, driven by diesel and common carriers, were expected to stay elevated all year, and executives acknowledged that inflation is narrowing the cost advantage over concrete pipe in some regions. Evidence that volumes are holding up despite higher prices would validate the strategy; signs of share loss to concrete would challenge it. End markets matter too. Non-residential grew 14% organically last quarter and ran ahead of plan, while residential slipped to flat. Investors should want non-res strength to survive the pull-ahead payback and see whether residential stabilizes or worsens. Allied storage products, up 18%, and the Infiltrator wastewater business, helped by the new Edge treatment product, are the higher-margin pieces that can cushion mix. Early reads on NDS cross-selling trials launched in August and progress at the expanded Cordele, Georgia recycling plant would add support for the longer-term margin story.
The market has already priced in plenty of gloom. Shares have fallen about 15% since the last report while the S&P 500 was essentially flat, and at $130.94 the stock sits well below its 200-day moving average of $143.95 and in the lower part of its post-earnings range of $122.84 to $156.82. Sentiment has cooled sharply, from 35.7% bullish heading into last quarter to just 9% now. That lowered bar does not guarantee relief, but it means a margin decline that lands roughly where management signaled may not shock anyone.
Ultimately, this report hinges on whether the margin compression is the well-telegraphed, temporary inventory roll management described or something deeper. A margin that dips as forecast, steady non-residential demand and a reaffirmed EBITDA range would keep the narrative intact. A steeper squeeze paired with softer volumes would suggest pricing power is fading just as costs peak.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Oct-05 | |
| Sep-28 | |
| Sep-16 | |
| Sep-14 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-16 | |
| Jul-09 | |
| Jun-18 | |
| Jun-11 | |
| May-21 |
