Xeris Needs Recorlev's Expanded Sales Force To Deliver A Steep Second-Half Revenue Climb
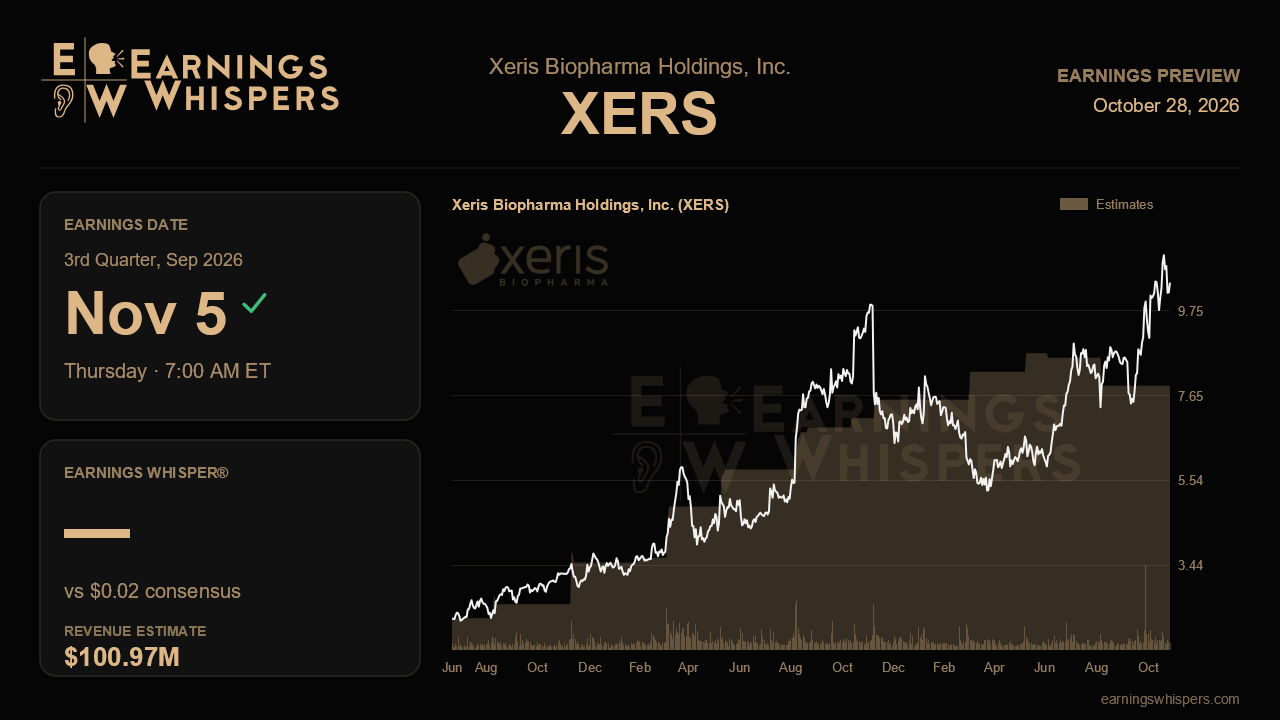
Xeris Biopharma has spent the past year building a story around Recorlev, its Cushing's syndrome drug. The third-quarter report, due before the open on November 5, is where that story has to show real growth. Management has said for months that the payoff from January's commercial expansion would land mostly in the back half of 2026. The back half has now arrived, and the math behind the full-year outlook depends on that promise holding up.
Wall Street expects revenue of about $101.0 million, up 35.8% from $74.4 million a year ago, and a small profit of $0.02 per share. That would be a sequential gain of roughly $9 million from the $92.1 million reported in the second quarter, about the same step-up the company managed between the first and second quarters. Management's full-year range sits at $385 million to $390 million. The low end has been raised twice, from an original $375 million, while the $390 million ceiling has never moved. Consensus of about $386 million sits near the bottom of that range. First-half revenue totaled roughly $175 million, so even the low end requires about $210 million in the second half. A $101 million third quarter would leave a fourth quarter near $110 million to stay on track. The Street is not asking for heroics, but it is asking for acceleration.
Recorlev carries most of that load. Its sales rose from $37 million a year ago to $56.8 million last quarter, up 81% year over year, and added about $7 million sequentially in the second quarter. The roughly 80-rep expansion targeting around 12,000 prescribers was described as tracking to plan. A Recorlev gain meaningfully larger than $7 million would be the clearest sign that the new reps are converting targets into prescriptions. A gain that merely repeats last quarter's pace would raise questions about whether the expected second-half lift has been pushed out.
Gvoke, the glucagon franchise, is the swing factor. It recovered to $22.5 million last quarter after a weak $20.8 million but remains below the $25 million run rate of a year ago, after Medicare coverage and out-of-pocket headwinds. Management pointed to back-to-school seasonality as a tailwind, and the third quarter is when that should appear. A return toward $25 million would ease pressure on Recorlev. Another quarter stuck in the low $20 millions would suggest the Medicare drag is lasting longer than expected. The third product line, steady at $11.7 million and newly protected by a patent allowance running to at least 2039, should be a stabilizer rather than a driver.
Profitability deserves equal attention. Gross margin reached about 86% on a richer product mix, and adjusted EBITDA climbed to $19.3 million. Management also lifted planned SG&A spending to about $50 million above 2025 levels, so operating leverage depends on revenue outpacing that extra spend. The July retirement of the 2028 convertible notes removes about $3 million in annual interest. This should be the first clean quarter without last period's $31 million non-cash remeasurement charge distorting GAAP results. Any update on starting the XP8121 Phase 3 by year-end, and on the Recorlev generic-drug patent litigation, will shape the longer-term view.
Expectations have climbed sharply. The shares are up about 45% since the last report while the S&P 500 was flat, and sentiment has swung from mildly bearish to clearly bullish. At $10.45, the stock trades well above its 200-day average of $7.46, though still about 8% below its post-earnings high of $11.42. That leaves less room for a merely adequate quarter. The central question is whether Recorlev's growth visibly accelerates enough to make the fourth-quarter target look routine. If it does, a move toward the top of the range becomes credible. If not, the ceiling that management never raised may start to look like the more meaningful number.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-15 | |
| Oct-02 | |
| Sep-29 | |
| Sep-29 | |
| Aug-26 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 | |
| Jul-02 | |
| Jun-30 | |
| Jun-11 | |
| Jun-11 |
