Accendra Health's Q3 Must Prove Collections Fix And Back-Half EBITDA Ramp After 88% Collapse
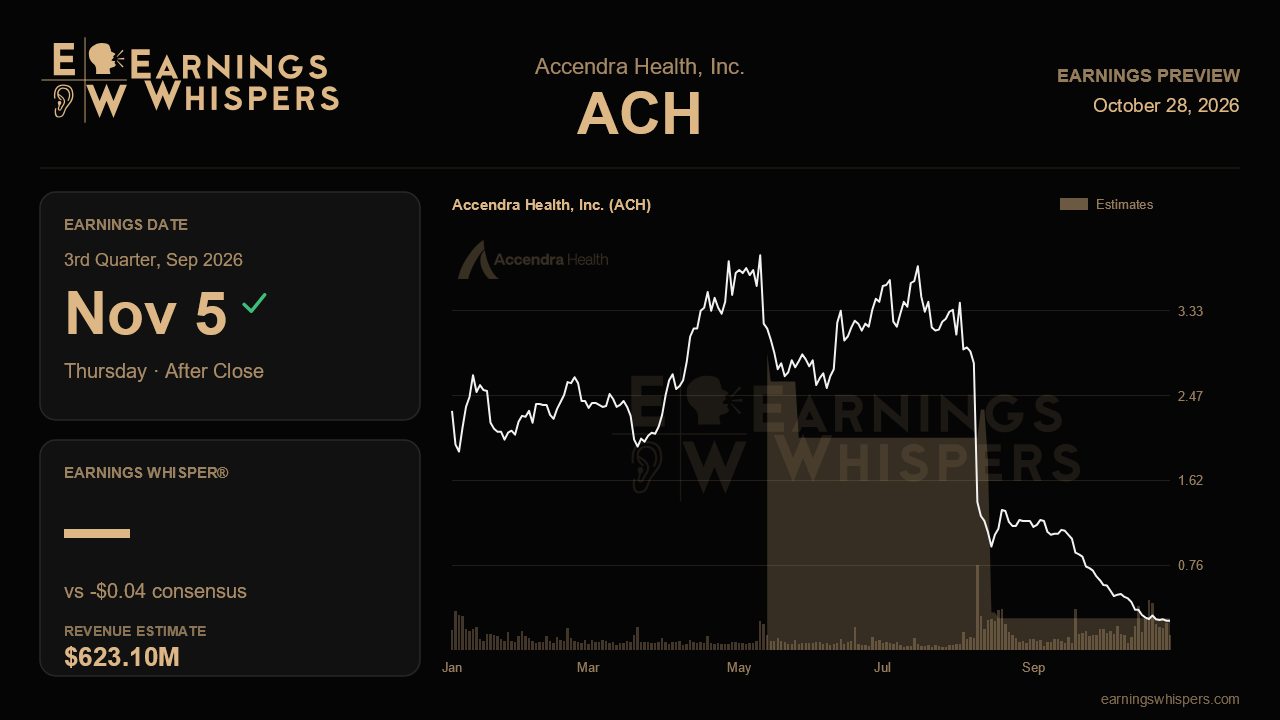
Few companies walk into an earnings report with as much to prove, and as little benefit of the doubt, as Accendra Health. Since its last report, when management cut its revenue, EBITDA and free cash flow targets, disclosed a spike in commercial-payer audits, and announced the CEO's planned retirement, the stock has lost roughly 88% of its value and now trades around 20 cents. The November 5 report, due after the close, is less about a quarterly beat than about whether the reduced outlook is still achievable and whether the business has enough liquidity to get to the 2027 recovery management keeps describing.
The Street is looking for a loss of 4 cents per share on revenue of about $623.1 million. That would be a sizable narrowing from the 19-cent loss in the second quarter, with revenue up modestly from $613.2 million. On the top line, consensus looks reasonable against the lowered full-year range of $2.45 billion to $2.55 billion, which works out to roughly $625 million a quarter at the midpoint. The bigger stretch is profitability. Adjusted EBITDA ran about $58 million in the first quarter and $60 million in the second, so hitting the cut range of $300 million to $320 million requires the back half to average somewhere around $90 million to $100 million a quarter. Management has framed the fourth quarter as the real jump-off point, but a third quarter that shows little improvement from the $60 million level would make the annual target look shaky only one quarter after it was reset.
The collections problem is the swing factor. The payer-audit waterfall cost about $10 million in the second quarter and about $20 million across the first half, swelled receivables and pulled staff away from automation projects. A clear decline in that drag, along with improving receivables, would support the idea that this was a temporary disruption rather than a lasting change in how big commercial payers treat the company. Equally important is whether the cost reductions that were paused in the first half have resumed, since those savings underpin the margin step-up the plan depends on.
Cash is the other pressure point. The company ended the quarter with only about $8 million on hand, introduced an at-the-market equity program and an NOL rights plan, and its higher cash interest burden of roughly $40 million a year begins hitting in December. Free cash flow guidance has already fallen from at least $100 million to roughly breakeven. With the stock near 20 cents, any equity raised through the ATM would be heavily dilutive, so evidence of internally generated cash, including proceeds from the non-core asset sales and early benefits from the third-party logistics initiative, matters a great deal.
There are real operating positives to defend. Sleep growth improved to about 5.5% last quarter, diabetes recovered to 4% growth on insulin pump strength, and ostomy and urology have consistently grown at a high-single-digit pace. The June refinancing pushed maturities out to 2029. Continued momentum in those categories, plus progress on the new sole-source and fee-for-service agreements, would show the core franchise is intact even as respiratory and wound remain weak. Updates on the CEO search would also help reduce the leadership overhang.
Sentiment has soured further, with bearish readings climbing from about 40% to nearly 49%, and the stock sits at the very bottom of its post-earnings range of $0.19 to $1.74, far below its 200-day average of $2.27. Expectations could hardly be lower, but that does not make a relief rally automatic. The report hinges on one question: can Accendra show that collections are normalizing and EBITDA is climbing toward a $90 million-plus quarterly pace fast enough to fund itself without leaning on deeply dilutive equity? A convincing answer keeps the reset plan alive. Another shortfall would suggest the guidance cut was not the last one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-09 | |
| Sep-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-27 | |
| Jul-27 | |
| Jun-24 | |
| Jun-23 | |
| Jun-10 | |
| May-22 | |
| May-12 |
