CONMED Beats On EPS And Lifts Its Profit Outlook, But A Second Trim To Top-Line Guidance Tempers The Acceleration
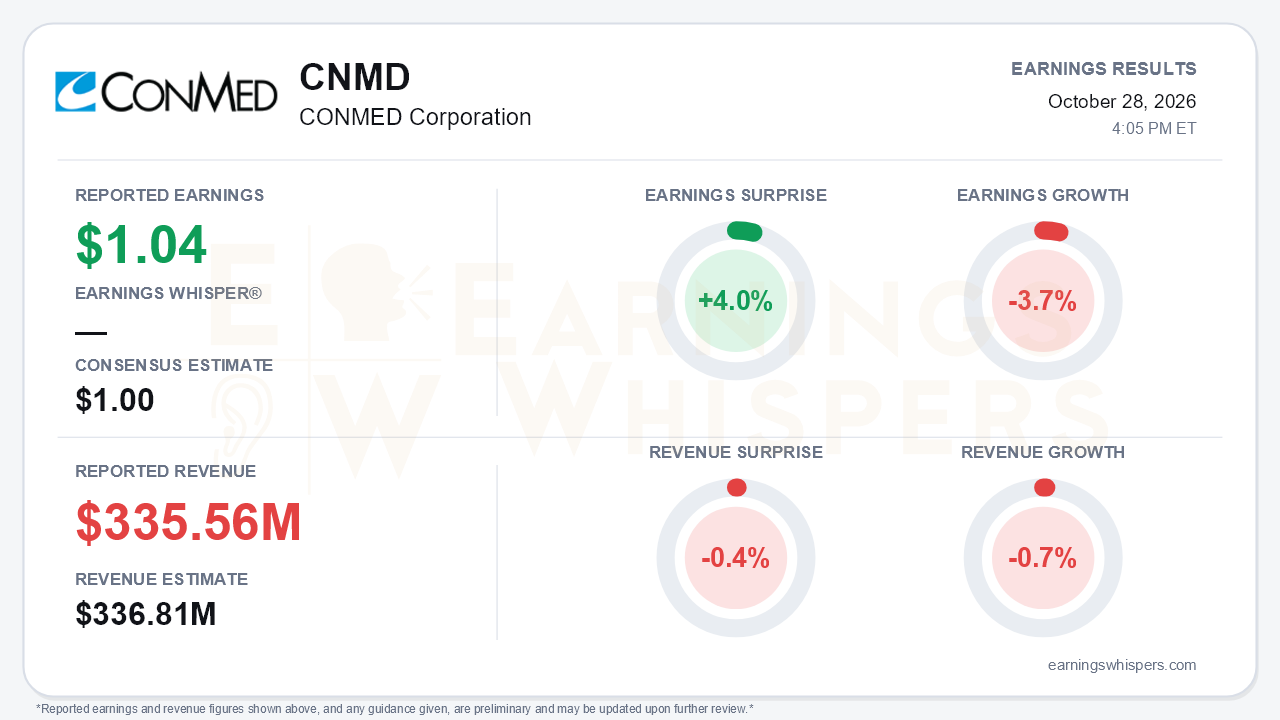
CONMED delivered the earnings beat investors look for, but the details are less clean than the headline. Adjusted EPS of $1.04 topped the $1.00 consensus by 4.0% and cleared management's own $0.98-$1.03 guide. Revenue of $335.56 million missed consensus by 0.4%, and earnings still fell 3.7% year over year. (The company's release cites a 3.2% decline against its $1.08 prior-year adjusted figure.) Revenue slipped 0.7%, weighed down by the deliberate exit from GI products. On an organic constant-currency basis, sales grew 6.7%, up from roughly 6% in Q2 and 2.1% in Q1. That is a real acceleration. The central tension is that management raised full-year EPS guidance while cutting the top end of its organic growth range for the second straight quarter.
GAAP results look dramatic but need context. Diluted EPS jumped to $0.66 from $0.09, up 613.7%. That swing reflects the absence of last year's $19.7 million product rationalization write-off and much lower optimization charges, not a sevenfold improvement in the business. The underlying margin picture is steadier:
- Adjusted gross margin was 56.4%, up modestly from 56.1%.
- Adjusted operating margin edged up to 15.4% from 15.1%.
- Adjusted EBITDA margin improved to 20.2% from 19.4%.
The drag sits below the operating line. Adjusted interest expense rose to $10.5 million from $6.3 million after the convertible refinancing, absorbing much of the operating gain. A lower share count and a 23.5% adjusted tax rate helped cushion the decline in adjusted EPS.
The geographic split shows where growth is coming from:
- **International:** Organic sales jumped 13.8%, with general surgery up 15.5% and orthopedics up 12.7%.
- **U.S. total:** Organic sales grew only 0.8%.
- **U.S. orthopedics:** Sales fell 1.7%, extending a slide from +5.5% in Q1 and flat in Q2 amid a commercial reorganization and distributor transition. Management now targets a return to growth in the first half of 2027.
- **U.S. general surgery:** Sales rose just 1.9% as OEM Buffalo Filter declines persisted.
The product platforms tell a better story. AirSeal re-accelerated into the high-single to low-double-digit range, as promised last quarter. Direct smoke evacuation grew at a similar pace, and BioBrace was strong abroad. Still, roughly $1.5 million of international distributor timing helped Q3 and is not expected to repeat in Q4. That one-off is part of why the full-year organic growth range narrowed to 5-5.5%, from 5-6% after Q2 and 5-6.5% after Q1.
The quality of the guidance raise deserves scrutiny. Full-year adjusted EPS guidance moved to $4.54-$4.61 from $4.48-$4.60, following an earlier raise from $4.30-$4.45. However, several pieces of the outlook point the other way:
- The FX tailwind assumption grew to about $9 million from $7-7.5 million.
- The adjusted tax rate assumption fell to roughly 24.5% from 25%.
- Gross margin guidance slid to the low end of the prior range, about 57.5%, on international mix and discrete inventory items.
- Interest expense guidance rose again, to about $33.7 million.
- Free cash flow guidance held at about $115 million after last quarter's cut from $125 million, and Q3 free cash flow fell 3.6%.
Put simply, the EPS raise leans on currency and taxes more than on operating upside, and bears have legitimate ammunition on cash conversion.
The forward catalysts are nonetheless credible:
- **Robotics:** AirSeal's new indication for Intuitive's 8 mm hex cannulas on the da Vinci 5 extends its reach into robotic surgery.
- **Smoke evacuation:** Smoke-free operating room laws now cover 23 states and about 60% of the U.S. population, up from 20 states and 51% earlier in the year, with more than ten others considering legislation.
- **Earnings tailwind:** The roughly $0.45 GI-related EPS headwind in 2026 should partly roll off in 2027.
- **Balance sheet:** Leverage fell to 2.7x from 3.1x in Q1.
- **Capital allocation:** A new CFO is targeting cash conversion, inventory and interest costs, and management signaled appetite for revenue-accretive M&A and a capital-structure review amid strategic-interest chatter.
The market setup is more complicated than the surprise implies. Investor sentiment improved from -0.10 to +0.03, moving from mildly negative to roughly neutral. That is a meaningful shift but hardly euphoric. Shares entered the report at $47.20, essentially unchanged (-0.6%) from the open after the July report. The quarter's path was volatile:
- The stock spiked to a 52-week high of $53.66 in early August.
- It then slid to $43.97 in early October.
- It entered the report about 12% below that peak.
The stock remains about 14% above its 200-day moving average, so the longer-term trend is intact even after surrendering the post-July spike. Price trends are generally positive, but the AVWAP reading remains negative, consistent with buyers since the August peak still sitting on losses.
The bottom line is that CONMED is executing on the profit side and showing genuine organic acceleration in its growth platforms, but this was not a clean raise. The U.S. business, especially orthopedics, is the weak link. International strength was flattered by timing, and the EPS increase rests heavily on currency, taxes and share count while interest costs and cash conversion move the wrong way. The 2027 setup, with the GI drag fading, U.S. ortho recovery targeted and strategic optionality in play, is where the bull case now lives.
Read our earnings preview for CONMED Corporation: https://www.earningswhispers.com/article/CNMD/20918
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-01 | |
| Aug-26 | |
| Jul-29 | |
| Jul-29 | |
| Jul-22 | |
| Jul-20 | |
| Jul-13 | |
| Jul-13 | |
| Jul-10 | |
| Jul-02 | |
| Jun-17 |
