Akamai's AI Cloud Bet Faces A Proof Test As GPU Revenue Must Start Arriving
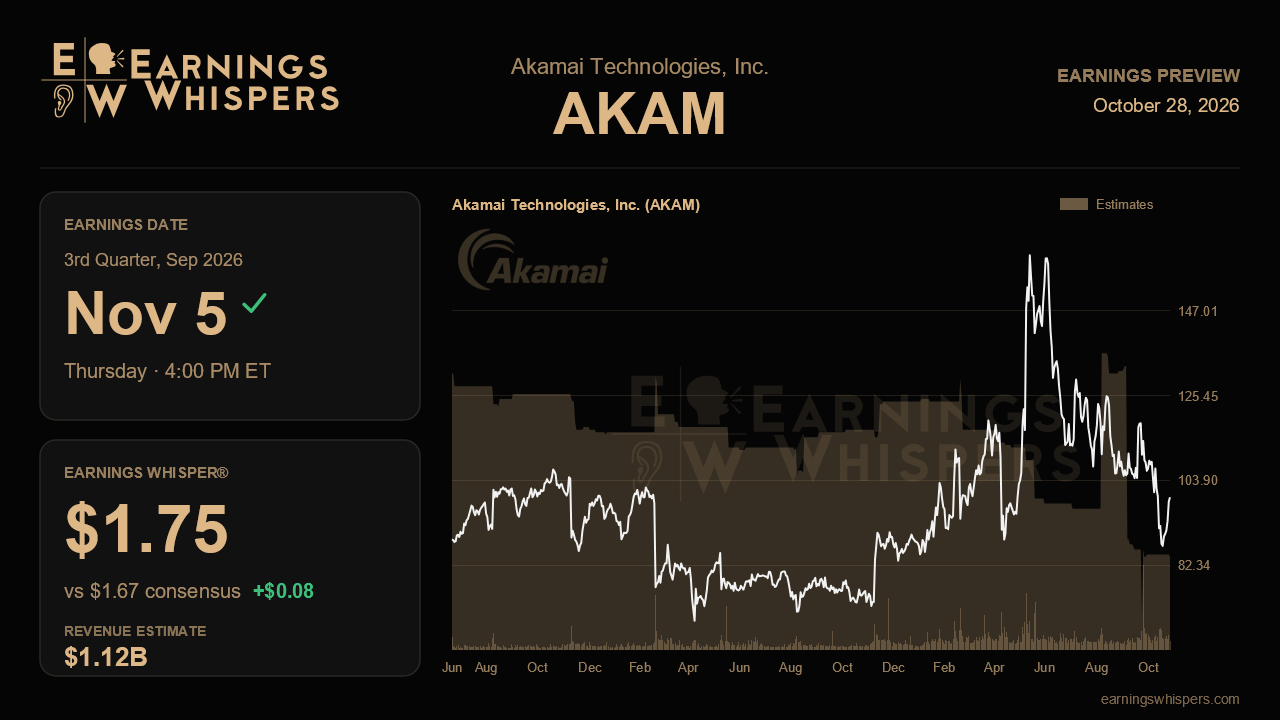
Akamai heads into its third-quarter report with an unusual mismatch between story and stock. Management has spent the year stacking up multi-year commitments for its cloud infrastructure business, which now total more than $2.8 billion, and it lifted its 2027 revenue growth outlook to the low teens. Yet the shares have dropped nearly 20% since the last report while the S&P 500 was essentially flat. The market is not doubting the demand. It is questioning what the build-out costs, how long it takes, and whether the revenue arrives on schedule. This quarter is the first real test of that timing.
The Street expects non-GAAP earnings of $1.67 a share on revenue of about $1.12 billion, which would be roughly 6.2% revenue growth from a year ago. That is modest, steady growth rather than a breakout, and it sits squarely in the middle of management's revenue guidance of $1.105 billion to $1.130 billion. On earnings, consensus is a touch below the $1.70 midpoint of the $1.60 to $1.80 range, while the whisper number of $1.75 points to some hope for an upper-half result. The gap is not huge, but it suggests that simply matching consensus may not be enough. For the full year, management narrowed its outlook to $6.40 to $7.05 a share on revenue of $4.445 billion to $4.530 billion, trimming the top end of both. Consensus of $6.78 sits slightly above the midpoint, so the Street is not demanding heroics, but it is not bracing for further cuts either.
The operational details matter more than the headline numbers. Last quarter, GPU shipments slipped from the second quarter into the third, pushing out both capital spending and a few weeks of cloud infrastructure revenue. That means this report should show the deferred revenue being recognized. Cloud infrastructure growth has been stuck at 39% for two quarters after peaking at 45%. A move back above that level would support management's claim that growth will rise sharply in the fourth quarter and keep climbing into 2027. Another quarter near 39% would leave investors relying more on management's word than on results. Because GPU capacity is completely sold out, any new delay in data-center readiness or hardware delivery would cut directly into revenue rather than simply push back the order book.
Profitability is the other half of the trade. Guidance for the non-GAAP operating margin has slipped at every update this year, from 26% to 28% down to roughly 25% to 26%, compared with 29% to 30% in 2025. Capital spending has climbed to about 40% of revenue. The company also raised $3.5 billion in convertible debt and paused its buyback, so the per-share support from repurchases is gone for now. A margin result that holds in the guided range would show that the squeeze is controlled. Any further cut would reopen the debate about whether the build phase is getting more expensive, especially with memory and server costs rising and the LayerX deal weighing on earnings. Management's earlier statement that large deals carry cash gross margins in the mid-60s to mid-70s will hold up better if third-quarter results begin to show some of that economics.
The security business, growing about 10%, needs to stay a steady anchor, helped by API security and new wins such as CrowdStrike. Investors will also want to see that the decline in content delivery does not deepen.
Sentiment has warmed noticeably from essentially neutral a quarter ago, even as the stock trades below its 200-day moving average of $112.35 and in the lower half of its post-earnings range. That leaves room for relief if the numbers line up. Ultimately, the report hinges on one question: does the delayed GPU revenue show up and push cloud infrastructure growth higher while margins hold? If both happen, the investment-heavy story stays credible. If either falls short, the stock's slide may look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 12 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 |
