Akamai's $11.6 Billion Anthropic Deal Rewrites The 2027-28 Outlook, But Near-Term Guidance, Margins And Capex Move The Wrong Way
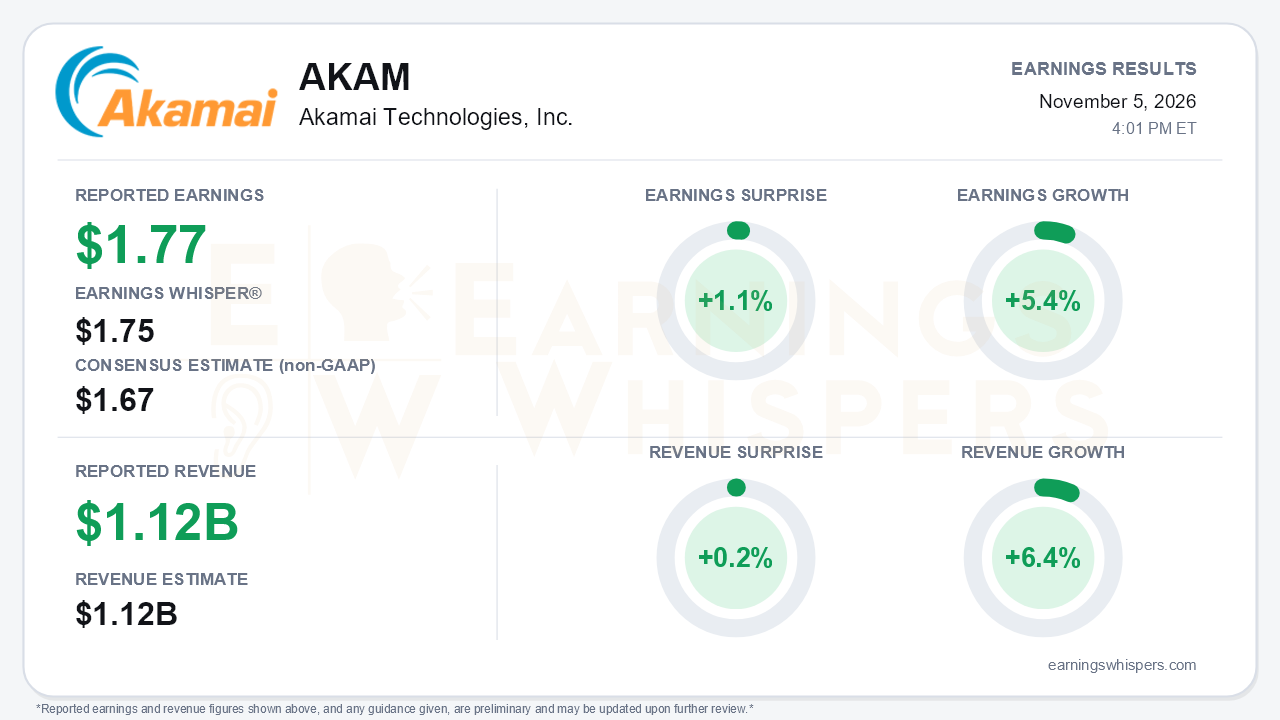
Akamai Technologies posted third-quarter non-GAAP earnings of $1.77 per share on revenue of $1.122 billion. EPS cleared the $1.67 consensus and topped the $1.75 Earnings Whisper number by 1.1%. Revenue edged past the $1.12 billion consensus by 0.2% and grew 6.4% year over year. The quarter itself, however, was close to a footnote. The real news was a sharply larger cloud infrastructure bet. It was anchored by an $11.6 billion, seven-year Anthropic CPU-workload commitment and brought Akamai's first explicit 2027 and 2028 revenue targets. At the same time, near-term guidance moved lower, margins compressed and capital spending surged. That is the central tension. Akamai is offering a much bigger long-term revenue story while asking investors to fund it with weaker profitability and a heavier balance sheet in the meantime.
The quality of the beat deserves scrutiny. Earnings Whispers' normalized figures show 5.4% EPS growth. Akamai's own reconciliation tells a different story: non-GAAP EPS fell 5% from $1.86 a year ago, so the year-over-year direction depends on which comparison basis is used. Several cleaner measures point in the same direction. Non-GAAP operating margin fell to 25% from 31%. GAAP operating income dropped 35%, and GAAP EPS of $0.77 was down 21%. Adjusted EBITDA declined 5%. Below the operating line, net interest income of $41.7 million, more than double last year's level, helped offset weaker operating profit. The non-GAAP share count also benefited from a $0.04 note-hedge adjustment. Sequentially the picture was better: non-GAAP EPS improved from $1.59 in the second quarter, and constant-currency revenue growth accelerated to 7% from 5%.
Beneath the headline, the mix shift continued. Security grew 10% in constant currency to $622 million. The decline in delivery revenue eased to 3%, from 5% in the second quarter and 8% in the first, which matters because that drag has suppressed consolidated growth. Cloud infrastructure services (CIS) rose 35% in constant currency to $109 million. That was a deceleration from 39% and kept the segment below 40%. The longer-dated numbers moved far more:
- Multi-year CIS commitments signed this year now exceed $14 billion, versus more than $2.8 billion at the second-quarter report.
- Management guided 2027 CIS revenue to $1.1 billion to $1.3 billion and total 2027 revenue growth to 17% to 22% in constant currency. In the second quarter, the 2027 outlook was "low teens."
- The 2028 revenue target exceeds $7 billion, based only on signed deals. It excludes a further $9 billion Anthropic option that carries warrants.
- For the first time, management quantified fully ramped large-deal economics: roughly $2.2 billion in annual revenue, about 75% adjusted EBITDA margin, about 30% non-GAAP operating margin and a roughly 15% ROIC.
Management's tone was its most confident yet. It also launched new AI products, Akamai Inference and Akamai Agent Sandbox.
Bears have legitimate ammunition on the near-term outlook:
- Supply-chain and third-party data center delays pushed about $30 million of revenue from the fourth quarter into 2027.
- The 2026 CIS growth guide was cut to 40% to 42%, from at least 50%.
- Full-year revenue guidance narrowed lower to $4.44 billion to $4.465 billion, and the operating margin guide slipped to about 25%.
- Fourth-quarter EPS guidance of $1.50 to $1.70 came in below estimates.
- Management expects margins to bottom in the first half of 2027, roughly a point below current levels, as colocation costs ramp ahead of revenue.
Capital intensity is the other pressure point. Full-year capex is now projected at $3.46 billion to $3.66 billion, including a fourth quarter of up to $2.6 billion with roughly $1.7 billion of memory pre-purchases. Third-quarter cash capex of $605 million already exceeded operating cash flow of $433 million. Buybacks were paused, cash and securities fell to $4.2 billion, and management flagged possible incremental financing around the 2027 convertible maturity. Concentration risk is also rising: the Anthropic deal carries the lowest-return pricing, and Akamai will stop announcing every large CIS deal. Management did offer mitigants. Colocation and power for the Anthropic deal are fully secured, about 70% of the hardware is procured with a contractual price-adjustment mechanism, and recent deal pricing is running well above earlier 2026 contracts.
The market setup is more complicated than the surprise implies. Shares closed at $85.93 the day before the report. That was 30.7% below the open following the August report, 23.5% below the $112.31 200-day moving average and just 3% above the inter-earnings low of $83.39, set that same day. The stock had peaked at $128.46 in late September, so it gave back the entire run and more heading into the print. Earnings Whispers investor sentiment improved from essentially neutral to a modestly positive 0.18, a meaningful but not euphoric shift. The trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Akamai delivered a modest beat on a quarter of shrinking margins, then reset its story around a multi-year AI infrastructure build that could roughly reshape the company's growth profile by 2028. The upside case now rests on execution: deploying capacity on time, keeping the funding requirement manageable and proving that CIS can finally deliver against its guidance. Investors are being asked to accept lower 2026 numbers, trough margins in 2027 and heavy capex in exchange for that visibility. The stock's slide into the report suggests the market was already skeptical about that trade.
Read our earnings preview for Akamai Technologies, Inc.: https://www.earningswhispers.com/article/AKAM/22231
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 |
