Arteris Stock Has Fallen A Third Since Raising Guidance; Can Backlog Growth Reverse It?
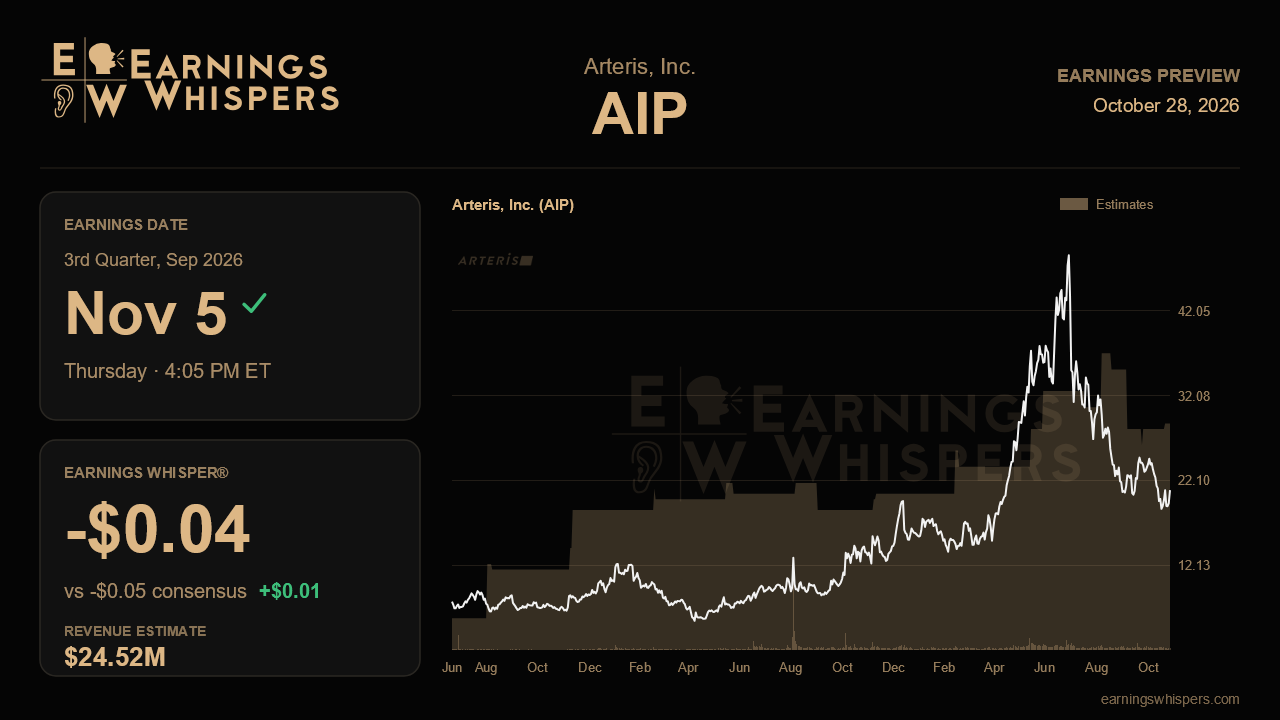
Arteris enters its third-quarter report with an unusual disconnect. Three months ago, management delivered what looked like its strongest quarter in years. It raised full-year revenue guidance for a second straight time, posted record backlog and named a hyperscaler that has standardized on Arteris interconnect IP. Since then the stock has dropped about 34% while the S&P 500 was essentially flat. When the company reports after the close on November 5, it needs to show that the operating story behind that guidance raise is still intact, even though the market has treated it as suspect.
The near-term bar is not demanding. Analysts expect revenue of about $24.5 million, up roughly 41% from $17.4 million a year ago. That figure sits at the midpoint of management's $24.0 million to $25.0 million guidance range, so a modest top-line beat would be routine. The Street's full-year estimate of about $95.7 million sits near the low end of the raised $95 million to $98 million range, which leaves room for another lift. The consensus calls for a non-GAAP loss of 5 cents a share. The whisper number is a penny better, a small gap that suggests traders lean slightly optimistic without expecting a dramatic surprise.
For a licensing business like this, the headline numbers matter less than the forward indicators. Annual contract value plus royalties reached a record $99.5 million last quarter, up 44% from a year earlier, and growth has accelerated for four straight quarters. Remaining performance obligations climbed to $135 million. If both metrics keep rising, the hyperscaler and custom-ASIC wins management highlighted are turning into signed contracts. A stall would suggest those headline deals were one-time events rather than a broadening trend. Royalties are the other key test. A customer supply-chain delay dented them last quarter, and management said the problem has been resolved. A clean sequential rebound would support that claim, especially now that Li Auto's self-driving chips have begun generating initial royalties. Management has already said royalty growth should slow from its recent pace of roughly 65% to the high-30s or low-40s percent range, so some cooling would not by itself be a problem.
Profitability is the weaker part of the story. Non-GAAP gross margin fell to about 87% from 92% after the Cycuity security acquisition moved subcontractor costs into cost of goods sold. The full-year operating loss guidance also widened to $7 million to $10 million. Part of that came from a French payroll tax on stock awards that rises and falls with the share price, so the stock's slide may reduce that cost. Higher sales commissions and lower-margin government work are less likely to disappear. Management still points to non-GAAP operating profitability as early as the fourth quarter. Any sign that this goal is slipping would matter, particularly on the first call with new CFO Saurabh Sinha, who started September 8.
Sentiment has improved to about 30% bullish from 13.5% heading into the last report, even as the stock has fallen. Shares trade near $21, well below the 200-day moving average near $25 and closer to the $18.15 low of their post-earnings range than to the $33.57 high. That is a sharp drop from last quarter's range, which topped out above $50. The company raised about $72 million in an at-the-market offering at roughly $35 a share, so it has ample funding for the acquisitions it has discussed.
The main question is whether forward demand is still accelerating. If contract value and backlog set new records and management keeps its fourth-quarter profitability target, the selloff will look like a reaction to sector-wide worries rather than to anything specific to Arteris. If those leading indicators flatten, investors will have more reason to believe the second quarter was the peak.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-21 | |
| Oct-21 | |
| Oct-14 | |
| Oct-08 | |
| Oct-06 | |
| Oct-05 | |
| Oct-02 | |
| Oct-02 | |
| Sep-24 | |
| Sep-22 | |
| Sep-18 | |
| Sep-16 | |
| Sep-15 | |
| Sep-14 |
