American Healthcare REIT Must Show Its $1 Billion Senior Housing Buying Spree Is Paying Off
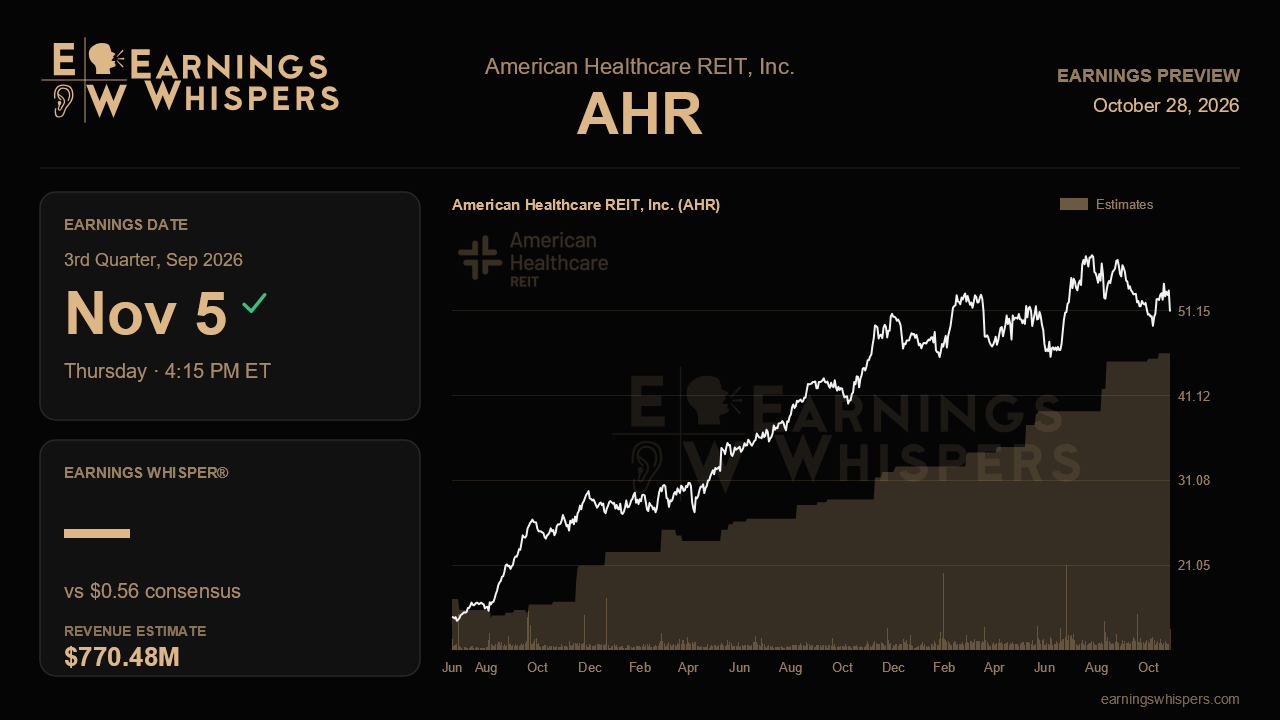
American Healthcare REIT heads into its third-quarter report with a curious disconnect. Management has raised its full-year outlook three times in a row, closed roughly $1.4 billion of acquisitions by midyear, and cut leverage at the same time. Yet the stock has slipped 8.5% since the last report while the S&P 500 was essentially flat. The question for November 5 is whether the operating story is still accelerating fast enough to win back a market that seems to have grown wary of how quickly the company is scaling.
The Street expects normalized funds from operations of $0.56 per share on revenue of $770.5 million, up 27.3% and 34.5% from a year ago. That is strong growth by any REIT standard, and the revenue jump of roughly $96 million from the second quarter reflects how much new property has entered the portfolio. The arithmetic around guidance is instructive. After posting $0.50 and $0.54 in the first two quarters, the company needs about $1.11 to $1.15 in the back half to land within its raised range of $2.15 to $2.19. A $0.56 print would sit right around the lower to middle portion of that path, so meeting consensus keeps the year on track without proving much. The older full-year consensus figure of $2.07 sits below management's range, which suggests some estimates have not fully caught up to the latest raise and leaves room for upward revisions if the quarter comes in clean.
The operating proof points come from the two growth engines. Senior housing operating properties were guided to 18% to 21% same-store NOI growth after delivering 20.5% in the second quarter with margins up more than 240 basis points to 22.3%. The Trilogy integrated senior health campuses hit a post-pandemic margin high of 21.1% and were guided to 13% to 16% growth. Validation would look like Trilogy holding margins near that level despite slower Medicare rate increases, with Medicare Advantage mix gains continuing to fill the gap, and skilled occupancy recovering from its seasonal second-quarter dip. In the senior housing book, sustained occupancy and pricing gains ahead of winter matter because the portfolio is heavily weighted toward assisted living and memory care, where colder months tend to bring more involuntary move-outs. Outpatient medical, trimmed to flat to up 1%, is shrinking by design and should not move the needle.
The acquisition engine is the more novel test. After the second quarter, the company bought 10 senior housing communities for about $1 billion, bringing in new regional operators that opened the Northeast at scale and deepened the Southeast, and it flagged a pipeline of more than $800 million that is not in guidance, plus an $86.2 million loan with a path to ownership. Management openly addressed concerns about underwriting discipline, so this report should show whether early results from those operators look like the existing portfolio and whether the Trilogy revenue management tools are being extended to them. With about $631 million in unsettled forward equity as dry powder and net debt to EBITDA at 2.5x, funding is not the issue; returns on deployed capital are. Leadership continuity under Jeff Hanson, who returned as permanent CEO after Danny Prosky's retirement, also remains a background consideration.
Sentiment has warmed considerably, with the bullish reading jumping to about 52% from under 9% a quarter ago, even as the share price retreated. At $51.06, the stock sits just below its 200-day average and near the bottom of its post-earnings range of $49.25 to $57.46, a setup where solid execution could be rewarded but any wobble would likely test support.
Ultimately, the narrative hinges on whether same-store growth stays near the top of the raised segment targets while the newly acquired properties integrate smoothly. If both hold, a fourth consecutive guidance increase becomes plausible and the stock's recent discount looks overdone. If growth merely meets the bar while integration questions linger, the market's skepticism about rapid scaling may persist.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-01 | |
| Sep-18 | |
| Sep-14 | |
| Sep-11 | |
| Sep-10 | |
| Sep-08 | |
| Sep-08 | |
| Sep-03 | |
| Sep-02 | |
| Sep-01 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Aug-06 |
