Benchmark Electronics Delivers A Third Straight Beat-And-Raise, But Payables-Funded Inventory Growth And Fading Free Cash Flow Complicate The Story
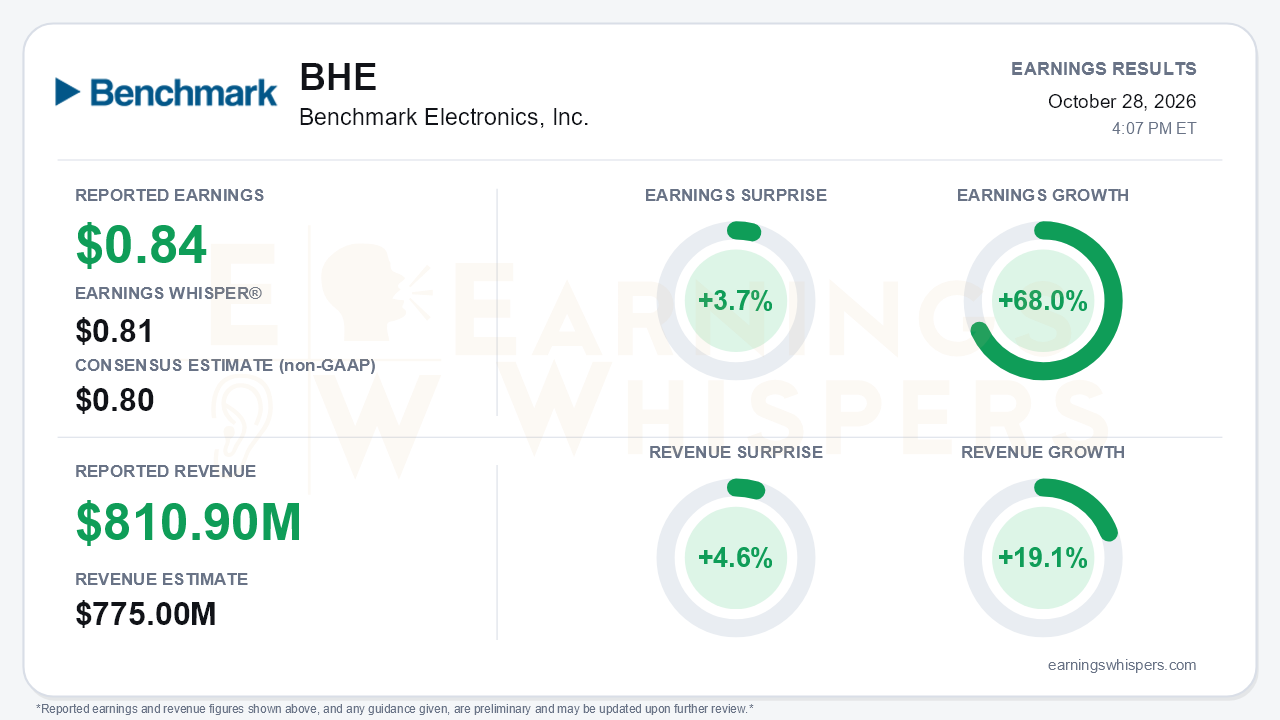
Benchmark Electronics (NYSE: BHE) delivered the kind of quarter its shares had not been priced for. Non-GAAP earnings of $0.84 per share beat the $0.80 consensus by 3.7% and edged past the $0.81 Earnings Whisper. Revenue reached a record $810.9 million, up 19.1% year over year and 4.6% above the $775.0 million consensus. Both figures cleared the top of management's own guidance ranges ($0.76-$0.82 and $755-$795 million). Fourth-quarter guidance also came in above estimates, and the full-year revenue outlook rose again, to roughly 16% growth and above $3 billion. That marks the third consecutive increase, up from mid-single-digit growth at the start of the year. The central tension is that the growth story keeps improving while the cash and balance-sheet story is moving the other way.
The earnings comparison deserves a note. Earnings Whispers calculates year-over-year EPS growth of 68.0%. The company's own non-GAAP reconciliation shows $0.84 against $0.62 a year ago, which is the 35% increase management cited. The difference reflects the prior-year comparison basis. Either way, earnings are growing far faster than sales, consistent with management's goal of expanding earnings 1.5-2x faster than revenue. Non-GAAP operating margin rose to 5.5%, up from 5.2% in the second quarter and 4.8% a year ago, on a steady 10.5% gross margin.
The GAAP picture is less flattering. GAAP EPS fell sequentially to $0.47 from $0.55, and GAAP operating margin slipped to 3.8% from 4.0%. Two items drove that gap:
- Stock-based compensation jumped to $9.5 million from $6.2 million.
- The quarter's tax burden was heavier.
Investors focused only on the non-GAAP line are seeing the cleaner version of the margin expansion.
The operating breadth is the strongest part of the report. By segment:
- **Semi-cap:** Grew 30% year over year, accelerating from 17% in the second quarter. Management now describes customer visibility extending into 2029-2030 and expects fourth-quarter growth to accelerate further.
- **AC&C:** Rose about 50%, and Benchmark expanded capacity on a compressed timeline for an AI on-premise customer. Management guided a material sequential AC&C increase in the fourth quarter.
- **Industrial:** Grew 13%, and its full-year outlook moved to mid-to-high single digits from flat, helped by lift-and-shift and competitive-takeaway wins.
- **Medical:** Landed the quarter's largest award, a program with a new device customer, though that program does not ramp until 2028 or later.
- **A&D:** Remains the soft spot, still down about 1% year over year despite a 15% sequential rebound.
Management's tone shifted from recovery to durability, and the fourth-quarter guide reflects that confidence: revenue of $815-$855 million and non-GAAP EPS of $0.85-$0.91. The guide also calls for a 5.5-5.7% operating margin and a lower 25-26% tax rate.
Bears have legitimate ammunition beneath the surface. Free cash flow has declined every quarter this year, from $29 million to $22 million to $14 million. Inventory climbed to $633.6 million from $482.5 million at year-end, and turns slipped below the 5x target as supply tightness spread from memory into ASICs. The improved 54-day cash conversion cycle looks good, but much of it came from stretching payables to 82 days, up from 73 last quarter. Accounts payable have swelled to $663.7 million from $403.2 million in December, which is not an indefinitely repeatable source of working capital. Two more risks weigh on the outlook:
- The next-generation HPC opportunity slipped to mid-to-late 2027, from the late 2026 or early 2027 start cited last quarter.
- Faster growth in lower-margin AC&C, plus higher variable compensation, will pressure mix.
The market setup is more complicated than the surprise implies. Shares closed at $70.70 heading into the report, down 17.5% from the $85.67 open following the July release. They had fallen from an inter-earnings high of $88.61 on October 2 to a low of $65.09 just days before earnings. The stock sat about 2% below its 200-day moving average and roughly 20% below its quarterly high. Investor sentiment was modestly negative at -0.20, suggesting expectations had cooled even as fundamentals strengthened. Earnings Whispers trend readings are mixed: momentum is positive while AVWAP remains negative, consistent with a stock that sold off hard during a quarter of rising estimates. That gap between improving fundamentals and a skeptical tape is what the beat-and-raise now has to address.
The bottom line is that Benchmark is executing a credible growth acceleration. Demand is broadening across semi-cap, AI-related computing and industrial, with margins and guidance moving higher together. Watch whether that earnings strength converts into cash. Rising inventory, payables-driven working capital gains, a widening GAAP-to-non-GAAP gap and the HPC delay give skeptics something to hold onto. Coming off a steep pre-report pullback, the stock's next leg likely depends as much on the cash flow trajectory as on another raise.
Read our earnings preview for Benchmark Electronics, Inc.: https://www.earningswhispers.com/article/BHE/20908
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 4 hours | |
| Oct-20 | |
| Oct-14 | |
| Sep-22 | |
| Sep-08 | |
| Aug-27 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Jun-30 | |
| Jun-29 | |
| Jun-17 |
