AMN Healthcare's Nurse Staffing Rebound Faces Its First Clean Test After A 48% Rally
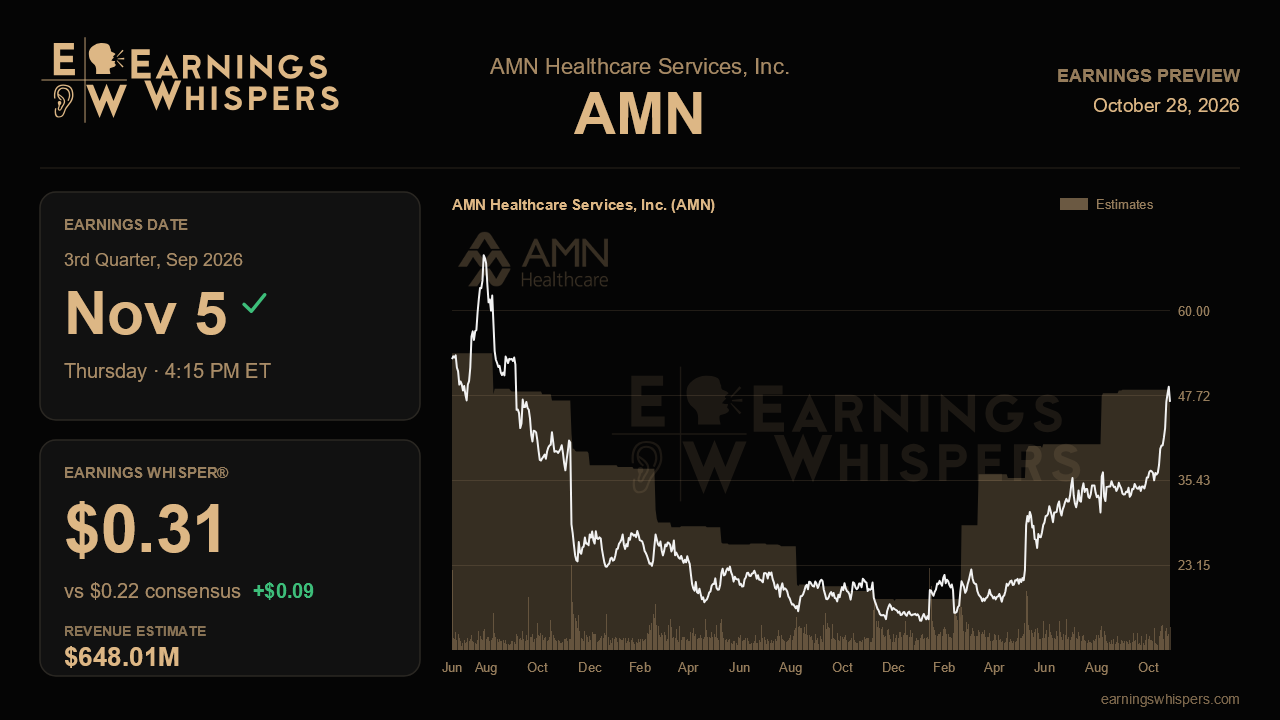
AMN Healthcare enters its third-quarter report with something it has lacked for years: a credible growth story in its core travel nurse business. Last quarter, management described the strongest volumes in four years and swung its nurse and allied outlook from a modest decline to roughly double-digit growth. The stock has rallied nearly 48% since then. When the company reports after the close on November 5, the question is whether that inflection holds up once the one-time items that flattered the prior quarter are gone.
The Street expects earnings of $0.22 per share on revenue of about $648 million. That revenue figure sits almost exactly at the midpoint of management's $640 million to $655 million guidance range. It is also well above where consensus stood when that guidance was issued, so analysts have already absorbed the raise. The forecast implies year-over-year revenue growth of about 2%, while earnings are expected to fall roughly 44%. The more telling comparison is sequential. Second-quarter revenue of $673 million included about $27 million of non-recurring benefits from labor disruption accruals and reserve reversals. Those items added roughly 290 basis points to gross margin and 370 basis points to EBITDA margin. Stripping them out leaves an underlying base close to the current guide, which is why a drop from $0.77 in EPS should not alarm anyone. The whisper number of $0.31 sits well above consensus, though. Many in the market expect AMN to clear the official bar by a comfortable margin, which raises the effective threshold for a positive reaction.
The nurse and allied segment carries the narrative. Management guided it to grow 9% to 11% year over year. It pointed to orders that turned positive in May and were running about 40% above the prior year by early August, with allied orders growing in the mid-teens. Confirmation would mean revenue at or above the top of that segment range, rising fill rates, and evidence that demand stayed broad across regions and care settings. The next lever is bill rates. They were still flat last quarter, which left pricing as upside the company had not yet captured. Any sign of firming rates, or commentary that winter orders are tracking ahead of last year, would suggest the recovery is moving from volume alone toward better economics heading into 2027.
The weaker segments still matter because they dilute that momentum. Physician and leadership solutions was guided down 5% to 7%, with locum tenens not expected to grow until 2027. Technology and workforce solutions was guided down 11% to 13%, weighed down by roughly 8% price-per-minute compression in language services. Search was a bright spot, up 27% in the second quarter, and is worth checking for durability. International nurse growth will draw attention after management trimmed its 2027 outlook to single digits because of embassy visa backlogs. The largest overhang is the Kaiser relationship, which is up for competitive re-bid at the end of 2026. Any update on that process could matter more than the quarter's numbers.
Expectations have clearly shifted. Sentiment has moved from mildly bearish before the last report to modestly bullish now. The stock, at $46.81, trades far above its 200-day moving average of about $28 and near the upper end of its post-earnings range, roughly 6% below the $49.62 high. That positioning suggests investors have already priced in a good deal of the recovery. The balance sheet gives management room to act on its newly stated appetite for acquisitions, with leverage at 1.5 times and $362 million in cash.
Ultimately, this report needs to show that the demand inflection is real in a clean quarter. If nurse and allied growth lands in double digits and management signals stable or rising bill rates into winter, the rebound narrative strengthens. If segment growth undershoots the guide, or Kaiser commentary turns cautious, a stock that has run this far could struggle to justify its gains.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-24 | |
| Sep-15 | |
| Aug-17 | |
| Aug-12 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-27 |
