Alkami Beats And Raises Again, But A GAAP-Basis EPS Miss And Cooling Leading Indicators Cloud The Growth Story
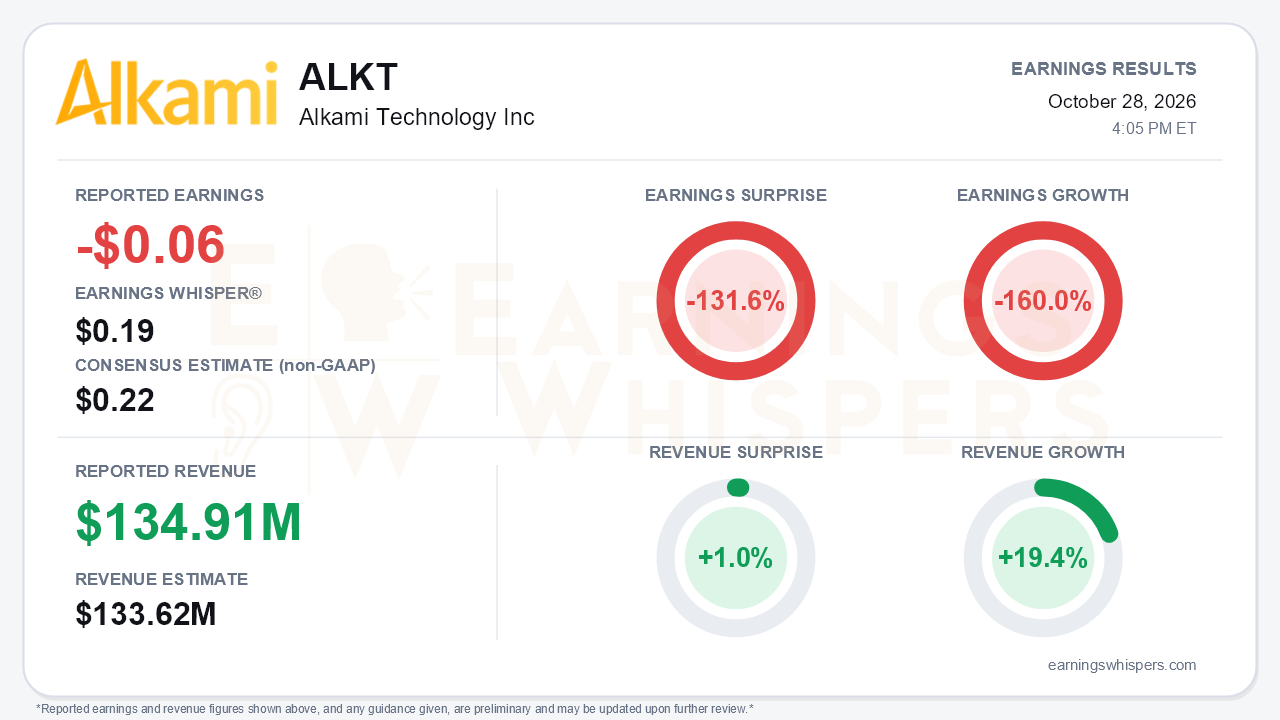
Alkami Technology reported a third-quarter loss of $0.06 per share on revenue of $134.91 million. Measured against the $0.22 non-GAAP consensus and the $0.19 Earnings Whisper number, that is a 131.6% earnings miss. The comparison needs context. The reported figure is a GAAP loss, while the estimates were non-GAAP, and on the company's own operating measures the quarter was clearly ahead of plan. Revenue beat consensus by 1.0% and grew 19.4% year over year. Adjusted EBITDA of $26.3 million (a 19.5% margin) cleared the company's $23.5-$24.3 million guide. Earnings Whispers calculates a 160.0% year-over-year earnings decline, yet the GAAP loss itself narrowed sharply, from $(0.14) per share a year ago. The headline miss is real on the stated basis, but it is not the central issue. The central tension is that Alkami again beat and raised on near-term financials while nearly every leading indicator of future growth softened.
The quality of the quarter deserves scrutiny on two fronts.
- **GAAP charges.** The GAAP line carried $2.1 million of stockholder-matters expense tied to the strategic review and $2.1 million of lease-assignment costs. Stock-based compensation remained heavy at $19.2 million. Non-GAAP income before taxes rose to $24.4 million from $13.6 million.
- **Flattered top line.** Management acknowledged that Q3 growth was helped by an easy comparison plus one-time third-party and core-conversion revenue.
- **Gross margin.** Non-GAAP gross margin of 63.1% slipped from 63.7% a year ago and fell short of expectations because of higher third-party product costs.
The upside came from operating leverage. Non-GAAP sales and marketing and G&A were essentially flat year over year, driving the 530-basis-point EBITDA margin expansion. Nine-month free cash flow climbed to $32.4 million from $19.9 million.
The forward metrics tell a more cautious story:
- **ARR growth:** live ARR growth decelerated to 19% ($533 million), from 21% in Q2, 22% in Q1 and 35% at the end of fiscal 2025.
- **ARR backlog:** shrank to $56 million across 31 clients, from $61 million and 37 clients last quarter.
- **Revenue per user:** growth slowed to 5%, from 20%, 9% and 7% over the prior three quarters. Management trimmed its outlook for this metric to mid-single digits.
- **RPO coverage:** fell to 3.2x live ARR from 3.6x.
- **New logos:** 16 digital banking wins year to date, versus a historical average of roughly 21 through Q3.
- **Margin target:** the earlier goal of exiting 2026 near a 65% gross margin was not reiterated.
Management blamed the new-logo shortfall on uncertainty created by the ownership review. That explanation is plausible but had not been flagged on prior calls. A technical problem also cut the Q&A short, leaving investors with less pipeline color than they needed.
The bull case rests on several new catalysts:
- **Strategic review resolved.** The board unanimously chose to remain independent in September, removing the ownership overhang management says weighed on new sales.
- **Agentic AI roadmap.** Plans include an in-app conversational agent, connectors to third-party assistants, and beta KYC, document-review and MCP-server agents in account opening. AI products already represent about 10% of revenue.
- **Implementation momentum.** Alkami completed a record seven core conversions this year and expects that to nearly double in 2027.
- **Customer depth.** Clients with at least $2 million of ARR rose to 56 from 50, and full-suite clients reached 60, up from 45 four quarters ago.
- **Cost efficiencies.** Management expects AI-driven savings to appear across the cost structure in 2027 and reaffirmed its Rule of 45 target for 2030.
The risk is timing. Today's new-logo and backlog weakness feeds into ARR well after the overhang lifts.
Guidance reinforces that split. Full-year targets were raised for the third straight call:
- **Revenue:** $530.5-$532.0 million.
- **Adjusted EBITDA:** $98-$99 million, with the midpoint margin edging up to 18.5%.
The fourth-quarter outlook, however, came in below some models even though it is broadly in line with consensus:
- **Q4 revenue:** $139.7-$141.2 million.
- **Q4 adjusted EBITDA:** $30-$31 million.
Management cited one-time revenue pulled into Q3 and a rising third-party cost mix. Much of the full-year raise therefore reflects the third-quarter beat rather than a stronger exit trajectory.
The market had been skeptical well before the report. Shares closed at $15.36 ahead of the release, down 16.4% from the $18.38 open following the July report. They sat 11.6% below the $17.37 200-day moving average and 27% below the August 14 high of $21.05. The stock set a 52-week low of $13.21 on September 29 and has since recovered about 16% from that level. Investor sentiment remains firmly negative but improved modestly, from -0.45 to -0.41, which is hardly a vote of confidence. Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP remain negative. That split fits a business whose near-term numbers are improving as its share price lags.
The bottom line is that Alkami delivered a quarter of genuine margin progress and another guidance raise, and it removed the ownership uncertainty that management says hurt new sales. The GAAP-basis miss against non-GAAP estimates matters less than what sits beneath the beat. Slowing ARR, a shrinking backlog, decelerating revenue per user and a softer gross margin give bears legitimate ammunition. The coming quarters need to show that new-logo wins rebound now that the strategic review is resolved. Until then, investors are being asked to trust the AI and conversion story while the growth engine cools.
Read our earnings preview for Alkami Technology Inc: https://www.earningswhispers.com/article/ALKT/20897
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-06 | |
| Oct-02 |
