A10 Networks Must Prove Its Raised Outlook And Microsoft Deal Can Outrun Memory Costs
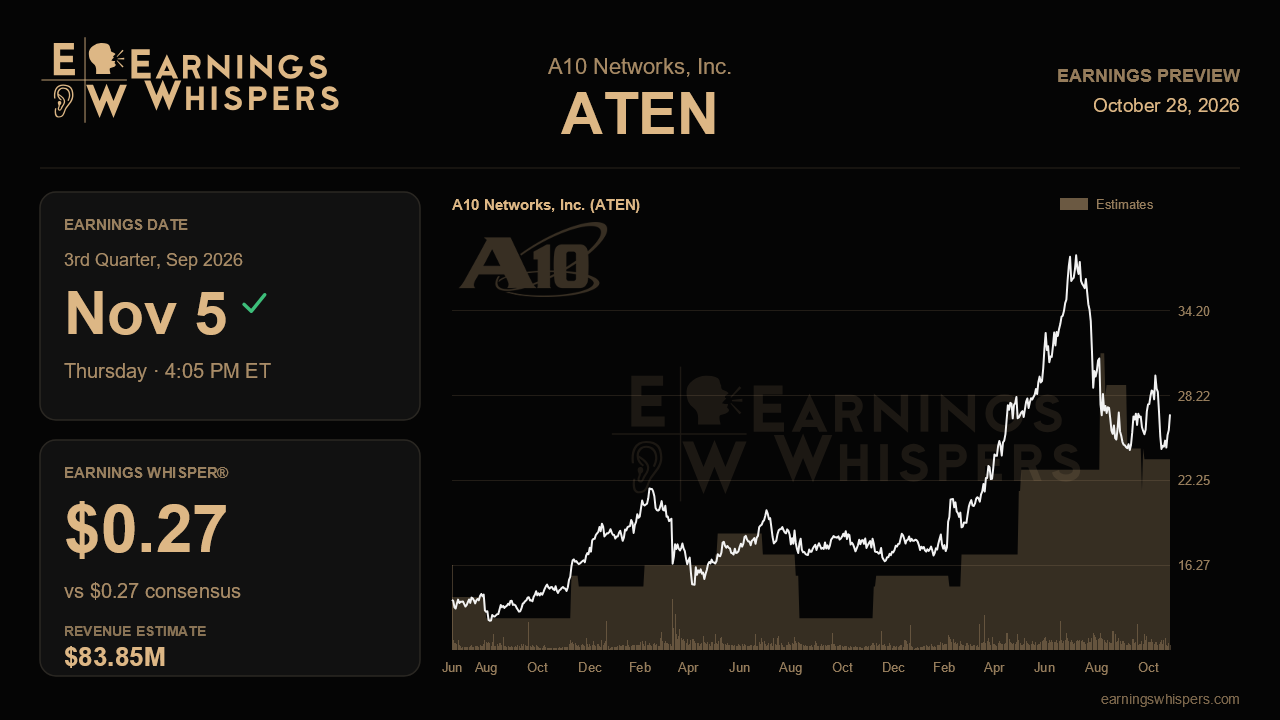
A10 Networks heads into its third-quarter report with a credibility test it largely set for itself. Last quarter management abandoned its habit of simply reiterating guidance and raised its full-year targets for both revenue and earnings, pointing to accelerating product sales, an expanded multi-year Microsoft agreement and the purchase of AI security specialist TrojAI. The market has not rewarded that newfound confidence. Shares have slipped 3.7% since the last report, trailing a roughly flat S&P 500, which means the burden of proof sits squarely on the numbers released after the close on November 5.
The Street is looking for non-GAAP earnings of $0.27 per share on revenue of $83.9 million. The Earnings Whisper matches consensus, so there is no hidden bar above the published estimate. Revenue at that level would represent 12.3% growth from $74.7 million a year ago, solid but a step down from the 15.5% pace posted in the second quarter. The earnings estimate is more ambitious, implying a sizable jump from $0.19 last quarter and $0.18 a year earlier, so margin execution matters as much as the top line. On the full year, management guided to revenue of roughly $325 million to $331 million and non-GAAP EPS of $1.03 to $1.04. Consensus of $1.04 sits at the top of the earnings range, while the $325.0 million revenue estimate sits essentially at the bottom of the sales range. That split suggests analysts trust the profit story more than the growth story, leaving room for a revenue upside surprise if demand holds.
Product revenue is the number that best captures whether the acceleration is real. It grew 25% last quarter after 22.3% in the first quarter and 13% in the fourth quarter of 2025, and management treats it as a leading indicator for the broader business. Another quarter of growth in the 20% range would validate the guidance raise; a sharp slowdown would raise the question of whether the second quarter pulled demand forward. Commentary on North American service providers, which management described as beginning to normalize, should show that improvement broadening rather than stalling. Early evidence that the Microsoft relationship is producing enterprise revenue on a new product set, alongside its legacy service provider business, would give the partnership tangible weight.
The risks flagged last quarter have not gone away. Memory and component cost pressure was expected to linger for several quarters, and gross margin has drifted from 80.8% to 80.3% over recent periods. Holding margins near 80% while absorbing those costs, plus TrojAI integration expenses, is essential if EPS is to reach $0.27. EMEA service providers remain hampered by geopolitics, and Japan and the broader Asia-Pacific region continue to push spending out. Customer concentration also deserves scrutiny, with a single end customer accounting for about 37% of revenue earlier in the year, which makes any lumpiness from that buyer a swing factor in either direction.
Sentiment has cooled, with bullish readings easing to 14.5% from 21.0% heading into the prior report. The chart tells a similar story of deflated enthusiasm. The stock traded as high as $38.49 in the previous quarter but has since been confined to a range of $23.98 to $29.85. At $26.90 it sits just above its 200-day moving average and in the middle of that band, neither breaking down nor pressing toward a breakout.
The central question is whether the mid-year guidance raise marked a durable inflection or a single strong quarter. If product revenue keeps growing briskly, margins hold near 80% despite memory costs and management at least reaffirms its full-year targets, the improving narrative stays intact and the stock's lag looks like an opportunity. If growth fades toward the low end of the range and cost pressures dent profitability, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-08 | |
| Sep-14 | |
| Sep-01 | |
| Sep-01 | |
| Aug-13 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-08 | |
| Jun-15 | |
| Apr-29 | |
| Apr-28 | |
| Apr-28 | |
| Apr-28 |
