Vanda Pharmaceuticals Beats On A Timing-Aided Quarter, But A Guidance Cut To The Old Floor And Slower Launches Overshadow The Print
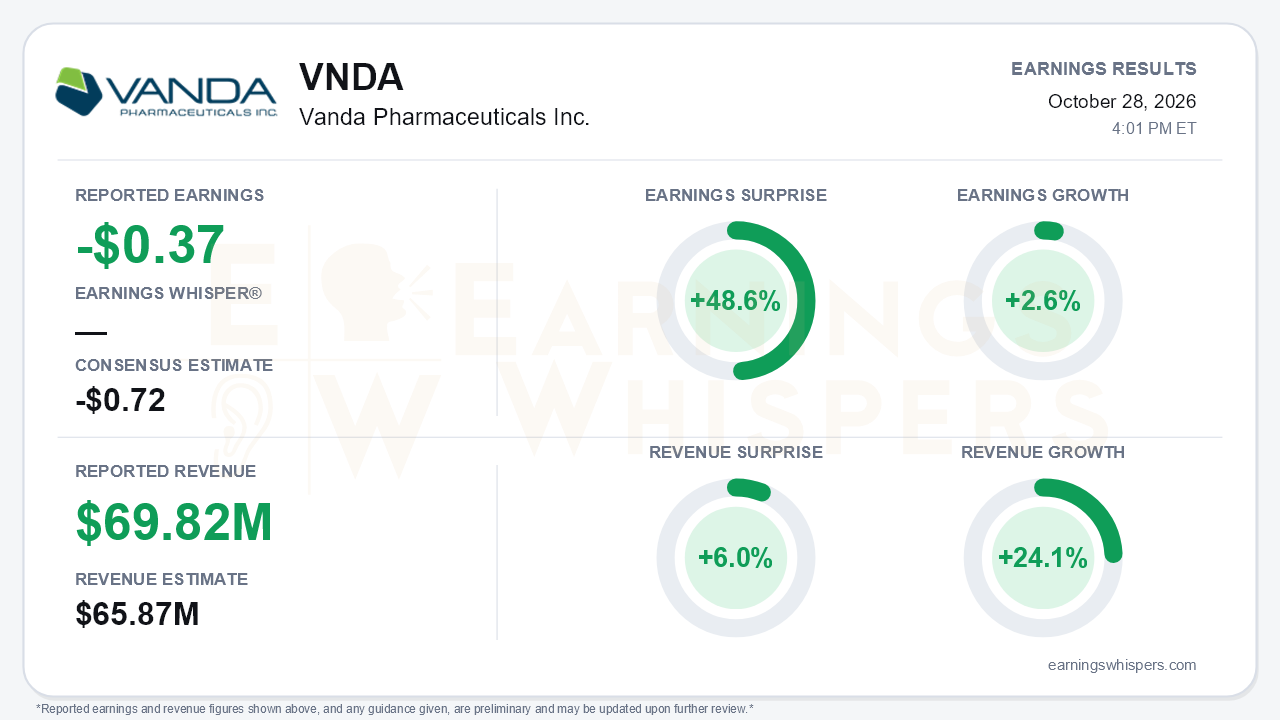
Vanda Pharmaceuticals posted a third-quarter loss of $0.37 per share. That was well ahead of the -$0.72 consensus, a 48.6% earnings surprise. Revenue rose 24.1% year over year to $69.82 million, beating the $65.87 million consensus by 6.0%. On the surface, revenue growth accelerated sharply. Sales were up 38% from Q2's $50.5 million and well above the 8% pace for the first nine months. But the beat came alongside a guidance reset. Full-year revenue guidance moved from $240-290 million to "greater than $240 million," which is effectively the old floor. The NEREUS outlook was also cut hard. That is the central tension: a strong quarter on paper, paired with a lower trajectory for the year and a launch slate running behind schedule.
The quality of the beat deserves scrutiny. Q3 revenue included about $7.0 million of HETLIOZ orders that shipped on June 29 but were recognized in July. The call also cited specialty pharmacy restocking. HETLIOZ sales jumped to $21.7 million from $5.6 million in Q2, yet nine-month HETLIOZ sales are still down 21% year over year, so the generic-erosion story has not reversed. Excluding the timing shift, revenue would have been roughly $63 million, short of consensus. The earnings line has its own nuance. Earnings grew only 2.6% year over year, and GAAP net loss was essentially flat at $22.6 million. Pre-tax loss actually improved, from $28.4 million to $22.4 million, but a $5.8 million tax benefit in the year-ago quarter flattered the comparison. The clearest genuine improvement was cost control. Operating expenses fell 18% sequentially to $93.3 million from $114.3 million, and the net loss narrowed from $62.5 million in Q2. Management guided to further declines as Phase III and launch-preparation work winds down.
Fanapt remains the engine, but it is slowing at the margin. Sales rose 24% year over year to $38.8 million. Weekly prescriptions hit an 11-year high of roughly 2,800 in September. However, new-to-brand prescription growth decelerated from +76% in Q1 to +32% in Q2 to +18% in Q3. Total prescription growth eased from 32% to 31% to 25%. The Fanapt-plus-BYSANTI sub-guide of $150-170 million was not reiterated. NEREUS is the bigger disappointment. Prescriptions and unique prescribers more than doubled after sales-force promotion began, but Q3 sales were only $1.6 million. Full-year NEREUS revenue is now expected below $10 million, versus $10-30 million previously, as consumer uptake proves slower.
The pipeline produced real news, though with caveats. NEREUS delivered a positive Phase III result in GLP-1-induced vomiting, and HETLIOZ succeeded in a pivotal study for Delayed Sleep-Wake Phase Disorder. Both are headed toward supplemental filings. Yet the NEREUS GLP-1 primary effect was a 27% relative reduction, versus 50% in Phase II, which tempers the commercial case. December is crowded with binary events: the Quimilza PDUFA date on December 12 and the HETLIOZ jet-lag hearing on December 14-18. The BYSANTI launch has slipped to Q4, with management hoping to launch before year-end. Its expected mid-30s gross-to-net, versus about 50% for Fanapt, matters because Fanapt faces loss of exclusivity around the end of 2027. The MDD readout has drifted again, to the first half of 2027, and the long-acting injectable program is being rethought.
Bears have legitimate ammunition on the balance sheet. Cash fell $29.5 million in the quarter to $140.5 million and is down $123.4 million since December. The prior "funded through end-2027" language was not repeated. Falling opex helps, but the runway now depends heavily on BYSANTI execution and the December outcomes.
The market had largely braced for disappointment. Shares closed at $3.99 the day before the report. That is down 14.0% since the open after the August release and 36.4% below the 200-day moving average of $6.27. The stock sat just 3% above the 52-week low of $3.88 set on October 23, far from the inter-earnings high of $5.64 in early September. Investor sentiment moved modestly more negative, from -0.0143 to -0.0912. The Earnings Whispers price and AVWAP trend readings remain negative.
The bottom line is that Vanda delivered a headline beat and meaningful cost discipline, but much of the revenue upside was timing-driven. Meanwhile, guidance, NEREUS expectations, Fanapt's new-patient growth, and the BYSANTI timeline all moved the wrong way. With shares near their lows and cash declining, the investment case now rests on December's regulatory events and a timely BYSANTI launch rather than on the quarter itself.
Read our earnings preview for Vanda Pharmaceuticals Inc.: https://www.earningswhispers.com/article/VNDA/21264
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-02 | |
| Sep-30 | |
| Sep-29 | |
| Sep-29 | |
| Sep-02 | |
| Aug-31 |
