McGrath RentCorp Beats As TRS Data-Center Demand Surges, But Delayed Modular Sales Force A Revenue Guidance Cut
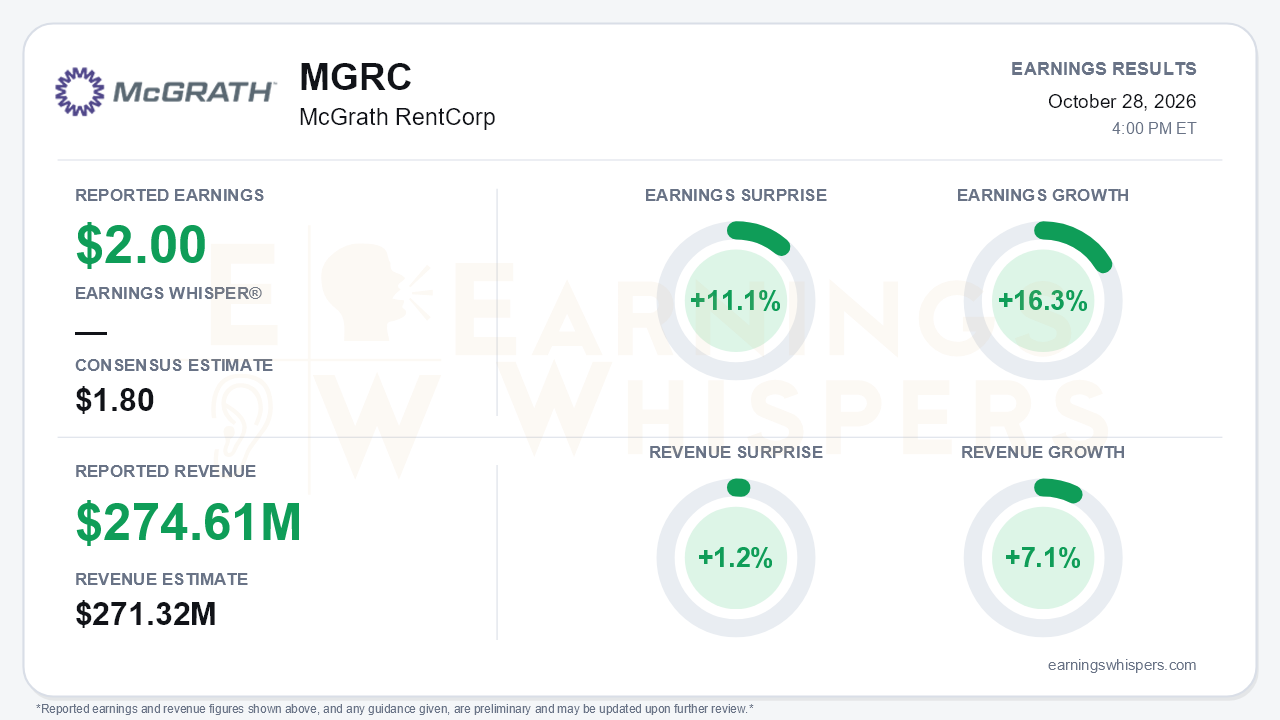
McGrath RentCorp delivered a clean headline beat for the third quarter, earning $2.00 per share against a $1.80 consensus, an 11.1% surprise. Revenue of $274.61 million topped expectations by 1.2%. Earnings grew 16.3% year over year and revenue grew 7.1%, a sharp reversal from a second quarter in which revenue fell 6% and adjusted EBITDA fell 4%. Yet the company also cut its full-year revenue outlook to $945–$960 million from $955–$985 million. That is the central tension. The rental engine, led by a data-center-fueled surge at TRS-RenTelco, is strengthening. Meanwhile, the new-unit modular sales business that investors had been counting on keeps slipping to the right.
The quality of the beat deserves scrutiny, because much of the year-over-year improvement came from timing rather than run-rate growth. Consolidated income from operations rose $7.2 million to $73.9 million. Enviroplex alone added $8.2 million of operating income, as sales nearly doubled to $25.7 million from $13.7 million when second-quarter project delays converted. TRS contributed another $3.9 million. Mobile Modular and Portable Storage together subtracted roughly $4.9 million. Mobile Modular segment revenue slipped 1% and its adjusted EBITDA fell 3% to $62.6 million, with sales revenue down 10% on weaker new-equipment sales. Portable Storage adjusted EBITDA dropped 20% to $7.4 million. Trucking costs drove rental-related services gross margin there to negative 25%, versus negative 13% a year ago. A modestly lower share count and slightly reduced interest expense also helped the per-share result.
The operating story that matters longer term is TRS. Rental revenue grew 26%, an acceleration from 17% in the second quarter and 13% in the first. Rental gross profit jumped 42%, and management cited a rental margin of 48% versus 43% a year ago. Ending utilization reached 71.9%, which management described as the highest in roughly 20 years. On the call, management framed AI infrastructure as an attractive multi-year opportunity spanning semiconductor R&D through data-center field testing. It also cautioned that record utilization is not sustainable over the long term and that the cycle's duration is uncertain. Mobile Modular rental revenue improved to 4% growth from 2%, and bookings and backlog are running above last year. Beneath that, average utilization fell to 70.2% from 72.6% and monthly yield eased. Units on rent were roughly flat after the second quarter's inflection, education returns exceeded shipments amid enrollment declines, and re-rent costs tied to Mobile Modular Plus are compressing rental margins.
Guidance reflects that split. The adjusted EBITDA range narrowed to $365–$373 million, with the midpoint held near $369 million. The entire revenue reduction is attributed to lower Mobile Modular new-equipment sales. Management pointed to contracted large projects taking longer because of permitting and site readiness, and said it will be cautious forecasting 2027 sales. The bigger forward-looking signal is capital spending. Gross rental capex guidance jumped to $270–$290 million from $200–$220 million last quarter and $180–$200 million in February, with most of the increase directed to TRS. Year-to-date rental purchases already total $219 million versus $92 million a year ago. Operating cash flow of $178 million did not cover that plus property investments, buybacks of $34 million and dividends. Notes payable rose to $618 million from $515 million, though leverage remains a manageable 1.68x. Bears have legitimate ammunition: McGrath is levering up to chase a utilization peak that management itself calls unsustainable.
Investor sentiment entering the report remained negative but improved meaningfully, rising to -0.18 from -0.29 at the prior report. The stock has been treated with similar cautious optimism. Shares closed at $119.56 before the release, up 2.9% from the open after the July report and about 5% above the 200-day moving average of $113.82. The stock sat 3.4% below its August 7 inter-earnings high of $123.82, well recovered from the September 3 low of $108.77. Earnings Whispers trend readings lean positive, with price, sequential growth and AVWAP all constructive.
The bottom line is that McGrath's quarter was better than its guidance cut implies, but not as strong as the headline beat suggests. Enviroplex timing flattered the comparison, and the core modular franchise is still treading water. The genuine upside is a TRS business riding data-center demand at multi-decade utilization, and management is backing that view with sharply higher capital. Whether that spending earns its return will depend on how long the TRS cycle lasts and whether delayed modular projects actually close in 2027.
Read our earnings preview for McGrath RentCorp: https://www.earningswhispers.com/article/MGRC/20959
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-01 | |
| Sep-18 | |
| Sep-11 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jun-30 | |
| Jun-25 | |
| Jun-03 | |
| May-11 |
