Century Aluminum's Record Quarter Setup Collides With A 30% Stock Slide
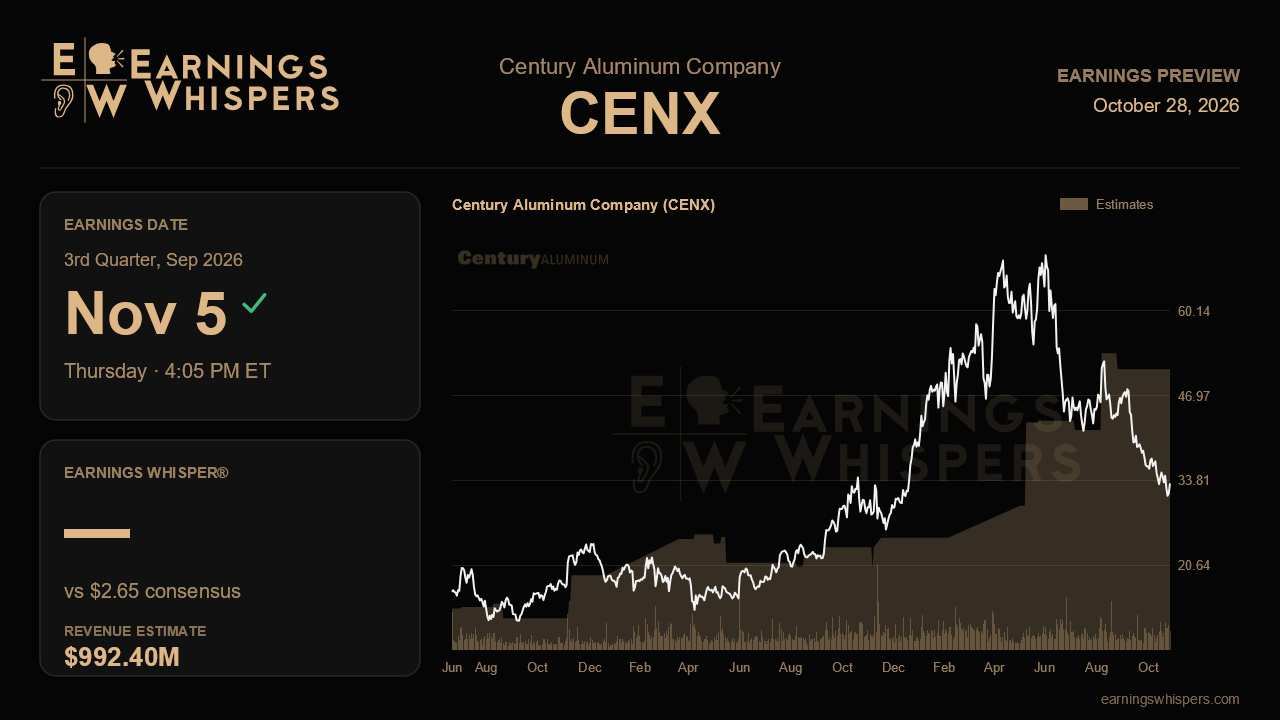
Century Aluminum heads into its third-quarter report with an odd disconnect. Management spent the last call describing what amounted to a payoff quarter: both major restarts finished, every smelter running at full capacity for the first time in over a decade, and the balance sheet flipped to net cash. Since then the stock has fallen about 30%, trailing a flat S&P 500 by roughly the same margin. Either the market sees something the operating story does not, or the November 5 release, due after the close, is an opportunity for the numbers to reassert themselves.
The Street expects earnings of $2.65 a share on revenue of $992.4 million. A year ago Century earned just $0.15 on $632.2 million, so the implied jumps of more than 1,600% in earnings and 57% in revenue mainly reflect how far aluminum pricing and Century's volumes have come. The more useful comparison is sequential. Last quarter's $2.39 came on $752.1 million of revenue, and consensus now assumes a roughly $240 million revenue step-up. Management's third-quarter adjusted EBITDA guide of $325 million to $345 million sits roughly in line with the second quarter's $327 million. Analysts appear to be building in a solid but not heroic step-up. That looks reasonable given guided LME pricing of about $3,325 a ton versus $3,250 realized, and a European duty-paid premium guided to $520 a ton from $450.
The operating test is whether full capacity actually shows up in the volumes. Second-quarter shipments rose 6% to 131,000 tons. With Mount Holly's final 90 pots online since late June and Grundartangi's Line 2 restarted about six months early in late July, the third quarter should be the first to capture most of that added output. Management flagged a few items that could dent the result. Mount Holly showed some instability after the restart, which the company said would be confined to this quarter. Grundartangi is running at slightly reduced amperage until new transformers arrive in the fourth quarter. Jamalco is still wrestling with lower-quality bauxite, a drag the company expects to last about two more quarters. The lagged Midwest premium was also guided down 3 cents to $1.09 a pound. None of these looks large on its own. Together, though, they explain why the EBITDA guide is not much higher despite firmer metal prices.
Cash is the other scorecard. Growth capex is essentially done, and $94 million of 45X credits plus about $20 million in insurance proceeds arrived after the second quarter closed. That should make this quarter's free cash flow notably cleaner. Management raised the idea that a stronger balance sheet creates room for shareholder returns, and any concrete movement there would carry weight with a stock this beaten down. Updates on the Oklahoma smelter matter too. The July executive order allowing Century's share of up to 300,000 tons a year of imports at a 25% tariff is meant to fund its equity, but the power contract and final investment decision are still pending against local pushback, with a year-end target.
Sentiment has edged from mildly bearish to mildly bullish, but the price action tells a harsher story. At $33.36, the shares sit well below the 200-day moving average near $50 and just above the post-earnings low of $30.75, far from the $55.55 high. Expectations embedded in the stock look considerably lower than those embedded in the earnings estimates.
The central question is whether Century can prove that its newly restored capacity converts into higher volume and cash at current prices, without the Mount Holly and Jamalco issues spreading beyond this quarter. EBITDA at or above the top of the guide, clean cash generation and a credible Oklahoma path would validate last quarter's confidence. A miss tied to operations rather than pricing would give the market's skepticism some justification.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-23 | |
| Aug-31 | |
| Aug-23 | |
| Aug-22 |
U.S. Steel Stocks Nucor, Steel Dynamics: Big Winners As Canada Trade Talks Collapse?
CENX
Investor's Business Daily
|
| Aug-19 | |
| Aug-14 | |
| Aug-11 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 |
