Cardlytics Must Prove Its Advertiser Rebound Can Outrun A Shrinking Cash Cushion
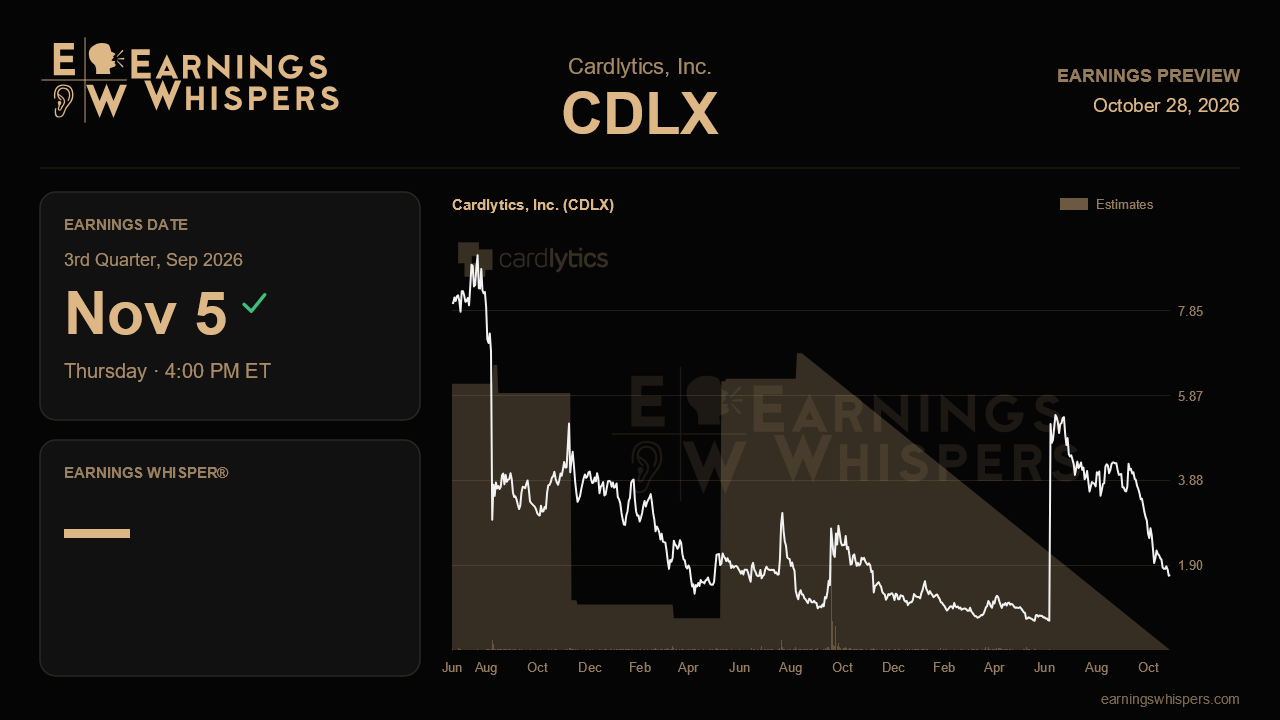
Cardlytics heads into its third-quarter report with a split personality. Last quarter, management argued that the reset of its bank-rewards advertising business was finally working. Active advertisers rose 18% from the prior quarter, new-logo volume jumped 59%, and churn fell by half by count and by 88% by dollar impact. Shareholders reacted as if they believed none of it. The stock has lost nearly 58% since that report, while the S&P 500 was essentially flat, and it now trades around $1.68. When the company reports after the close on November 5, the question is whether better advertiser metrics can start showing up in revenue and cash before the balance sheet forces the issue.
Management guided for third-quarter revenue of $34 million to $39 million. The Street sits at about $38.6 million, near the top of that range. That is a demanding spot for a company whose own outlook implies little or no improvement from the second quarter's $36.9 million. Consensus would still mean revenue roughly 26% below the $52.0 million reported a year ago, which is a smaller decline than the 36% drop last quarter. The improvement comes mostly from easier comparisons after bank-partner changes, not from new momentum. Billings guidance of $61 million to $67 million puts the midpoint below the second quarter's $65.5 million. That quietly walked back the steady sequential-growth story management had stressed earlier in the year. A result near the low end of either range would undercut the claim that the business has turned. Reaching the high end with billings above $65.5 million would restore some credibility.
The operating story rests on a few measurable claims. Adjusted contribution margin climbed to 57.7%, helped by a richer mix of newer bank partners. Adjusted EBITDA of $1.7 million beat the top of guidance. Holding margins near that level while revenue stalls would show the gains are structural rather than a one-quarter mix effect. Management also listed several new catalysts. These include an expanded Monzo partnership in the UK that began in July, local third-party offers now live at four banks, and a set of AI tools that roughly halved campaign build times. Monzo deserves particular attention. UK growth has slowed every quarter, from 35% to 21% to just 10% last quarter. A reacceleration there would be the clearest early sign that a new catalyst is paying off. Another quarter of slowing would suggest the international engine is fading just as the US business tries to stabilize.
Cash is the uncomfortable center of the story. Free cash flow was negative $10.7 million last quarter, and cash fell to $28 million from $48.7 million two quarters earlier. One bank partner temporarily cut its revenue share to fund joint development, which helps near-term economics. Even so, another quarter of burn at that pace would leave little room for error. Any commentary on liquidity, working capital or financing options could matter as much as the income statement. The company has posted losses of $1.36 per share a year ago and $1.50 last quarter, so profitability on a per-share basis is not the near-term debate.
Sentiment has soured noticeably, with readings far more bearish than before the last report. The stock sits below its 200-day moving average of $2.31 and just above its post-earnings low of $1.61, well off the $4.91 high. Expectations are clearly depressed. That lowers the bar for a relief move but also signals deep doubts about durability.
Ultimately, this report will be judged on conversion. Advertiser counts, lower churn and AI productivity are encouraging, but they need to translate into sequential billings growth and a narrower cash burn. If they do, the reset narrative survives. If revenue lands at the low end and cash keeps draining, investors will likely conclude the turnaround is running out of time.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-06 | |
| Sep-24 | |
| Sep-24 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Jul-31 | |
| Jul-29 | |
| Jul-21 | |
| Jul-02 | |
| May-07 | |
| May-07 | |
| May-01 |
