Impinj Posts A Clean, License-Free Record Quarter As Demand Begins To Outrun Backend Capacity
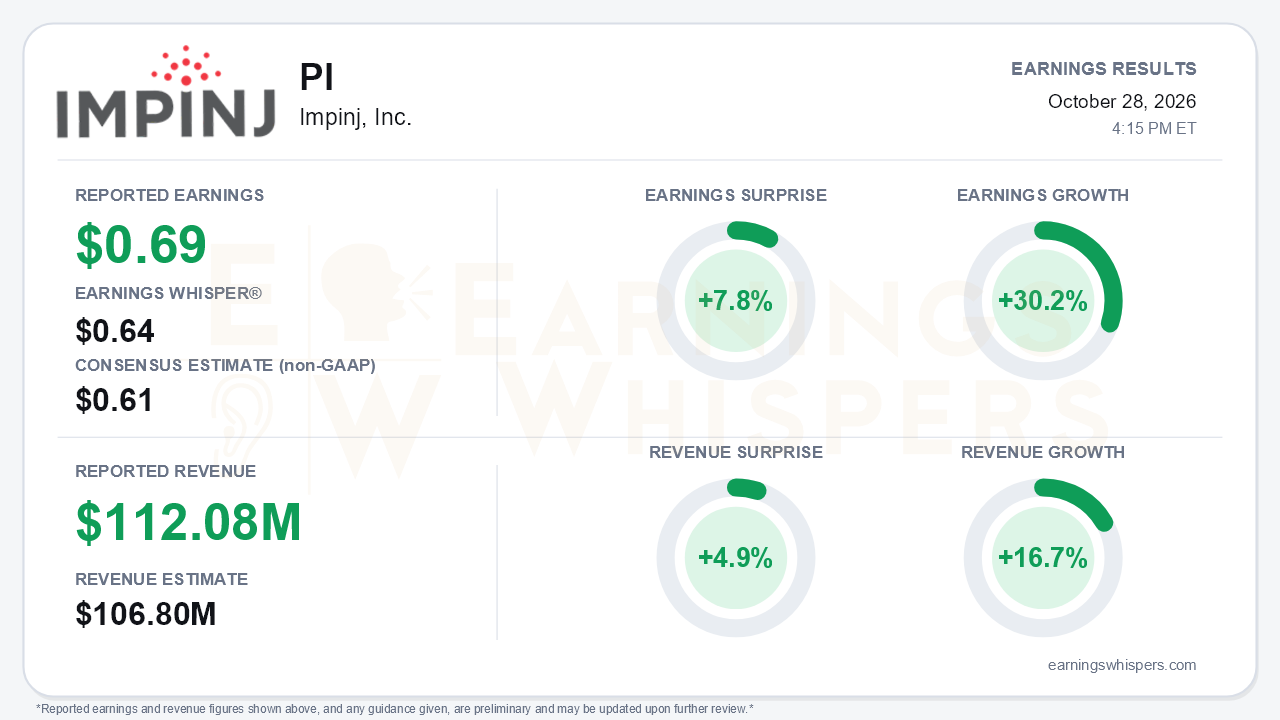
Impinj delivered the quarter that bulls needed: a record driven entirely by product sales, with no licensing revenue. Non-GAAP earnings of $0.69 per share beat the $0.61 consensus by 7.8% and cleared the $0.64 Earnings Whisper number. Earnings grew 30.2% year over year. Revenue of $112.08 million topped the $106.8 million consensus by 4.9%, rose 16.7% from a year ago and exceeded the top of management's own $105.5 million to $108.5 million guidance range. Fourth-quarter revenue guidance of $104 million to $107 million also came in above estimates. The central development is that the conversation has shifted from whether demand would hold to whether Impinj can build enough product to meet it.
The quality of the beat holds up well. Second-quarter results included a roughly $17 million license payment. Third-quarter results did not, yet endpoint IC revenue still reached a record $97.3 million, up 24% from a year ago and 23% sequentially excluding that license. Systems revenue climbed 23% sequentially to $14.8 million, with reader ICs the fastest-growing piece. Third-quarter growth was also well ahead of the roughly 10% pace for the first nine months, so the top line is accelerating. Non-GAAP gross margin improved to 54.9% from 53.0% a year earlier, and adjusted EBITDA of $24.5 million beat the guided range of $20.7 million to $22.2 million. On a GAAP basis, Impinj earned $4.7 million, or $0.15 per share, compared with a $12.8 million loss a year ago. Much of that swing reflects a far smaller induced-conversion charge ($1.8 million versus $15.0 million). The gap between GAAP and non-GAAP results remains wide, driven largely by $16.1 million in quarterly stock-based compensation, and investors should keep that in view.
The call marked a clear change in tone. Over the past year, management has moved from guiding to inventory burndown, to flagging macro caution for the second half, to dropping that caution this quarter. On the call, management cited broad-based demand, customers booking into the first quarter of 2027 and a rising backlog. Product gross margin rose 130 basis points sequentially, and management guided roughly another 100 basis points of improvement in the fourth quarter. Drivers include the M800 and the return of margin-accretive specialty endpoint ICs after a multi-year drought. The fourth-quarter guide implies only a modest sequential decline, compared with the typical 5% to 10% seasonal drop. Additional catalysts include:
- two new food-sector customers, including a direct whole-solutions engagement;
- Kroger bakery pilot data showing roughly 70% faster counts, 50% lower waste and a sales lift of about 200 basis points;
- the September physical intelligence platform launch;
- software general availability expected in "months, not quarters," with modest software revenue in 2027.
Bears have legitimate ammunition, however. Backend wafer post-processing capacity is now a binding constraint. Management said it cannot get ahead of demand for at least two more quarters, and capex will step up in the first quarter of 2027. Fourth-quarter systems revenue is guided down sequentially, which is atypical, because a lighthouse enterprise project has shifted right. Endpoint IC bookings, while still above a 1.0 book-to-bill, fell short of the first- and second-quarter records. Rising costs are prompting price increases in first-quarter 2027 negotiations. The M800 reaches terminal mix in the fourth quarter, which removes an incremental margin tailwind. Free cash flow of $20.6 million was down from $29.2 million in the license-boosted second quarter, though up from $18.0 million a year ago. Cash and investments fell to $228.3 million after a $56.3 million convertible repurchase. Management again acknowledged it must "prove" the first quarter of 2027 after two consecutive mid-teens first-quarter declines in endpoint IC revenue.
Investor expectations had been improving before the report. Earnings Whispers sentiment rose from -0.24 to -0.09, which means it remains negative but is meaningfully less so. The stock entered earnings at $174.81, up 16.5% from the open after the July report and 21% above its 200-day moving average. It was also 29% above the inter-earnings low set the day after that report. Shares had pulled back about 9% from the October 14 high of $192.82, so some enthusiasm had already cooled heading into the print. Price, momentum and AVWAP trend readings are positive, while the sequential-growth reading remains negative. That split fits the guided fourth-quarter dip and the open questions about the first quarter.
The bottom line is that Impinj answered the license-quality question decisively with a record product quarter, expanding margins and a better-than-seasonal outlook. The investment debate now shifts to execution. Investors will be watching whether capacity can keep pace with demand, whether price increases offset rising costs once the M800 margin lift is gone, and whether the first quarter of 2027 finally breaks the pattern of steep seasonal declines.
Read our earnings preview for Impinj, Inc.: https://www.earningswhispers.com/article/PI/20976
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-01 | |
| Sep-10 | |
| Sep-08 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-06 | |
| May-26 | |
| Apr-30 | |
| Apr-30 | |
| Apr-29 |
