Universal Display Beats On Adjusted EPS, But A Missed Materials-Margin Recovery And A Low-End Revenue Outlook Temper The Rebound
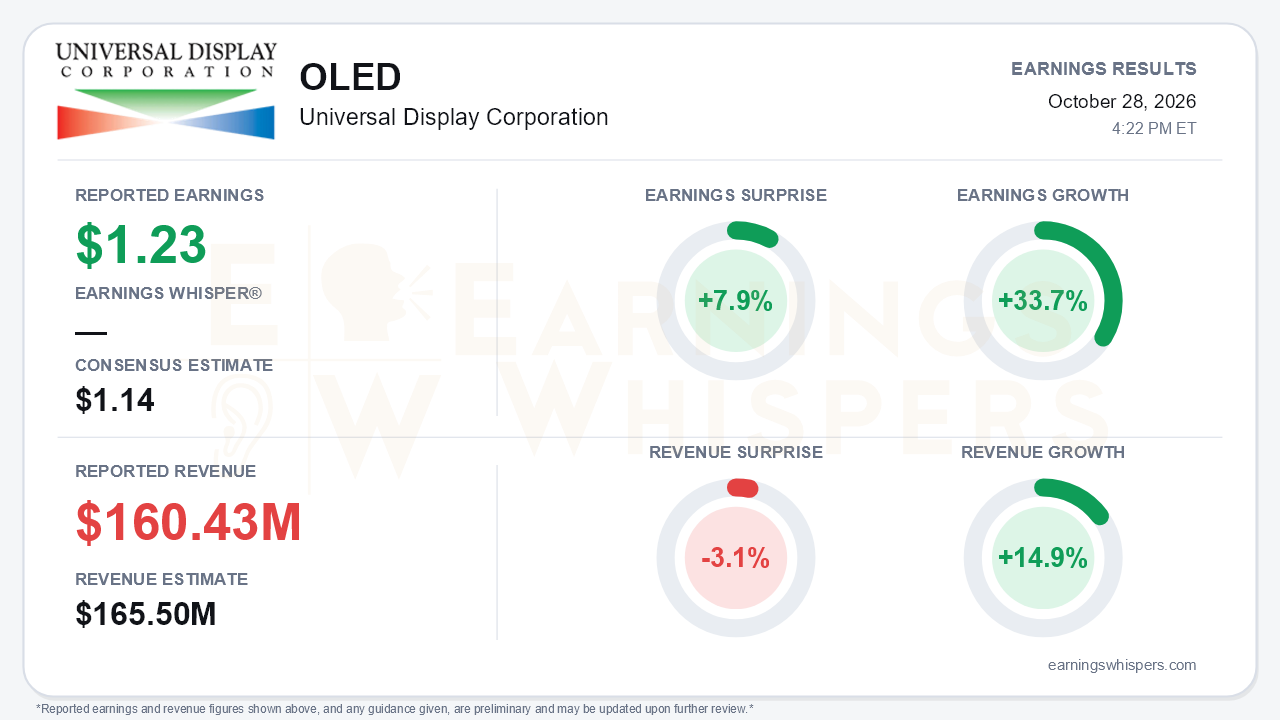
Universal Display (NASDAQ: OLED) delivered a third-quarter earnings beat, but the quarter's real story is margin erosion and a fourth quarter that now has to do a lot of work. Adjusted earnings of $1.23 per share topped the $1.14 consensus by 7.9% and grew 33.7% year over year. Revenue of $160.43 million rose 14.9% but missed the $165.5 million consensus by 3.1%. GAAP EPS was a much louder $1.72, but that figure was inflated by a $28.9 million non-cash gain on a UDC Ventures investment and a $7.2 million currency gain on a won-denominated tax receivable. The beat is real. Its quality, however, deserves scrutiny.
On the surface, revenue reaccelerated. Sales rose from $152 million in Q2 and returned to year-over-year growth after a first half that ran below 2025 levels. Nine-month revenue is still down, at $454.8 million versus $477.7 million. The composition of the growth matters. Royalty and license fees jumped to $75.5 million from $53.3 million, but the year-ago comparison was depressed by a $9.5 million out-of-period adjustment. Material sales, meanwhile, slipped to $79.7 million from $82.6 million on customer mix and a $4.8 million unfavorable catch-up adjustment, despite higher unit volume. Materials gross margin fell to 50% from 60% a year ago, which pulled total gross margin down to 73% from 76% in Q2 and 75% a year earlier. Operating margin still improved to 33% from 31%, helped by flat R&D spending, but the gross-margin line is moving the wrong way.
That is the central tension. On the Q2 call, management said materials margins would return to roughly 60% in the second half. Instead, they held near 50% for a second straight quarter. The full-year gross-margin outlook has now slid to the low end of the 74%–76% range, after tracking above 75%. The materials-to-royalty ratio has also drifted down, from 1.3:1 to 1.2:1 and now about 1.1:1, as customer and product mix shift. Looking into 2027, CFO Brian Millard flagged several headwinds:
- higher input costs;
- continued memory-cost tightness;
- only mid-single-digit OLED area growth.
Blue development revenue is also expected to stay low during what management called a "strategic transition" to next-generation blue materials, which reads as a timeline reset.
Guidance needs careful reading. The Earnings Whispers guidance note characterizes the outlook as a raise in line with estimates. The release, however, says only that the company continues to expect 2026 revenue around the low end of its prior $630–$670 million range. That range was itself cut from $650–$700 million earlier in the year. Investors should treat this as a reaffirmation of a twice-lowered target, not an upgrade. Even the low end implies roughly $175 million in Q4, a meaningful sequential step-up from $160 million, so execution risk remains.
The call did offer a credible long-dated growth story:
- Apple's iPhone Duo foldable reportedly sold out its initial allocations, with deliveries extending into 2027.
- Samsung Display restarted construction of a greenfield OLED fab for foldables and IT, and LG Display is expanding Gen 6 capacity while evaluating Gen 8.
- The company introduced its OLED X light-extraction platform.
- UVJC launched NovaJet, its first commercial equipment system.
- An AI discovery platform has generated hundreds of new blue cores.
These catalysts are tangible, but they mostly pay off beyond the near-term margin problem. Capital return remains aggressive. Buybacks rose to $78.8 million in Q3 from $48 million in Q2, helped by stronger nine-month operating cash flow of $234 million. Cash and investments, however, have fallen to $828 million from $955 million at year-end.
Investors had already shifted their stance before the report. Earnings Whispers sentiment remained negative but improved substantially, rising from -0.69 after the prior report to -0.22. The stock closed at $90.36 ahead of the release, up 14.4% from the $79.00 open after the July report. Shares recovered nearly 28% from a 52-week low of $70.77 set on October 9 and entered earnings about 4% below the inter-earnings high. That rally left the stock just 2.5% below its 200-day moving average of $92.67, so much of the turnaround enthusiasm was arguably already priced in. The trend readings are mixed, with sequential growth and AVWAP positive while momentum remains negative.
The bottom line is that Universal Display cleared a low bar on earnings and showed sequential revenue improvement, but the details give bears legitimate ammunition. Materials margins did not recover as promised, gross-margin guidance moved lower, the full-year revenue target sits at the bottom of a reduced range, and management is already flagging 2027 cost pressures. Foldables, new fabs and next-generation platforms keep the long-term thesis intact. With the stock having rebounded sharply into the print, though, the near-term setup depends on whether Q4 can deliver the required ramp without further margin slippage.
Read our earnings preview for Universal Display Corporation: https://www.earningswhispers.com/article/OLED/20972
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| Oct-26 | |
| Oct-20 | |
| Oct-15 | |
| Oct-13 | |
| Oct-08 | |
| Oct-08 | |
| Sep-30 | |
| Sep-22 | |
| Sep-20 | |
| Sep-16 | |
| Aug-25 |
