Happen Beats And Raises Full-Year EPS Guidance, But Credit Releases, A Revenue Miss And A Softer Q4 Outlook Leave A Battered Stock Waiting For Proof
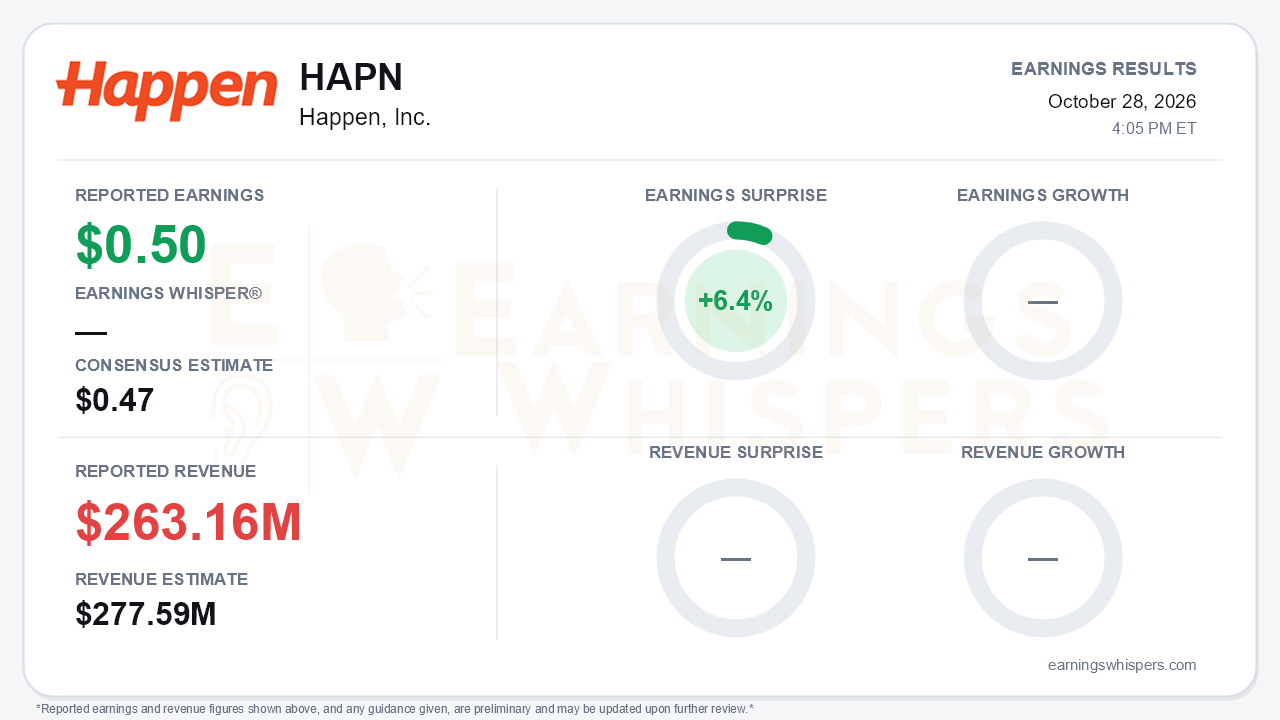
Happen, Inc. (NASDAQ: HAPN) delivered another earnings beat in its first quarter reporting under its new name. Diluted EPS was $0.50, against a $0.47 consensus estimate, a 6.4% upside surprise. EPS was also above the company's own $0.43-$0.48 guidance and up 35% from $0.37 a year ago, by the company's measure. Revenue told a different story. Net revenue of $263.16 million missed the $277.59 million consensus by 5.2% and was slightly below the prior-year $266.2 million. Management also raised full-year EPS guidance to $1.87-$1.92 from $1.80-$1.90, yet the fourth-quarter outlook of $0.43-$0.48 is below the $0.50 just reported. That is the central tension. Happen keeps clearing the EPS bar, but the drivers of the beat are less durable than the headline, and the forward run-rate is flattening.
The quality of the beat deserves scrutiny. Pre-tax income reached a record $76.8 million, only marginally above the second quarter's $75.7 million, and EPS was flat sequentially. Two items did much of the work:
- **Provision benefit.** A $15.9 million benefit replaced a $46.3 million expense a year ago. It came from the shrinking legacy amortized-cost book: the allowance fell to $152 million from $276 million at year-end, while new loans are carried at fair value.
- **One-time gain.** The call identified about $12 million of one-time benefit from repurchasing a $300 million discounted loan portfolio.
The fair value option election also explains the revenue miss. Net fair value adjustments swelled to a $131.4 million drag from $38.4 million a year earlier, offsetting a 64% jump in origination fees. Risk-adjusted revenue, which nets out provision, rose 27% to a record $279.1 million. That suggests reported revenue understates underlying activity, but it also means the accounting transition flatters year-over-year comparisons.
Underneath, the operating engine is growing.
- **Volume and income.** Originations rose 26% to $3.34 billion, at the top of the prior guide. Net interest income hit a record $183.1 million.
- **Credit.** Held-for-investment net charge-offs improved to 3.1% from 3.2% in the second quarter and 3.4% a year ago.
- **Balance sheet.** Deposits climbed 22% to $11.5 billion.
- **Efficiency.** Management highlighted AI-driven gains, with 26% higher volume handled by 20% fewer operations staff and compensation up only 6%.
The cost of that growth is rising, however. Marketing expense jumped 79% year over year to $72.8 million, or 2.18% of originations versus 1.53% a year ago. Management attributed part of this to rebrand friction and less efficient new up-funnel channels. Net interest margin slipped to 6.05% from 6.14%, and ROTCE edged down to 15.8% from 15.9%. CET1 also fell to 15.7% from 16.9% as the held-for-investment book grew 13% sequentially.
Rates are the main risk the call surfaced. Benchmark rates rose about 60 basis points in the quarter, producing roughly $20 million of balance-sheet markdowns and pressure on loan sale prices. Hedges, now about $2.45 billion notional, offset about $15 million of that. Management responded by prioritizing unit margins: it raised borrower prices and pulled back on auto refinance. As a result, it trimmed the top of full-year origination guidance to $12.4 billion from $12.6 billion and guided fourth-quarter volume to $3.1-$3.2 billion, below the third quarter. Guidance also assumes a December Fed hike.
On the positive side, the catalysts are tangible:
- Home improvement topped $100 million in its first full quarter.
- Structured certificates passed $10 billion cumulative and added a top-10 insurer.
- First cleanup calls in the fourth quarter are expected to support pricing.
- A home equity product is slated for the second half of 2027.
- Management signaled heavier buybacks with $41 million of authorization remaining.
The market setup is more complicated than the surprise implies. Investor sentiment deteriorated sharply, falling from roughly neutral at -0.10 after the prior report to a decidedly negative -0.66 ahead of this one. Shares entered the report at $14.32, down 26.8% from the post-July open of $19.55. The stock peaked at a 52-week high of $21.25 on August 4 and fell to a 52-week low of $13.73 on October 26, leaving it just 4.3% above that low. The supplied 200-day moving average of $10.63, shown as 34.7% below the current price, is hard to reconcile with a 52-week low of $13.73, so the inter-earnings range is the more reliable read on price action. The AVWAP trend reading remains negative. Investors were clearly positioned for rate-driven disappointment, not for a raise.
The bottom line is that Happen produced a credible beat-and-raise backed by strong credit, 26% origination growth and expanding new channels. However, bears have legitimate ammunition: a revenue miss, earnings helped by legacy reserve releases and one-time gains, rising acquisition costs and a fourth-quarter guide that implies sequential decline. With sentiment depressed and shares near their lows, the report changes the debate from whether the model works to whether it can sustain earnings growth as reserve releases fade and rates stay elevated.
Read our earnings preview for Happen, Inc.: https://www.earningswhispers.com/article/HAPN/20944
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-09 | |
| Oct-06 | |
| Sep-30 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-09 | |
| Jul-07 | |
| Jun-22 | |
| Jun-02 |
