Nextpower Beats And Raises Again As Revenue Accelerates, But Margin Compression Is The Price Of Growth
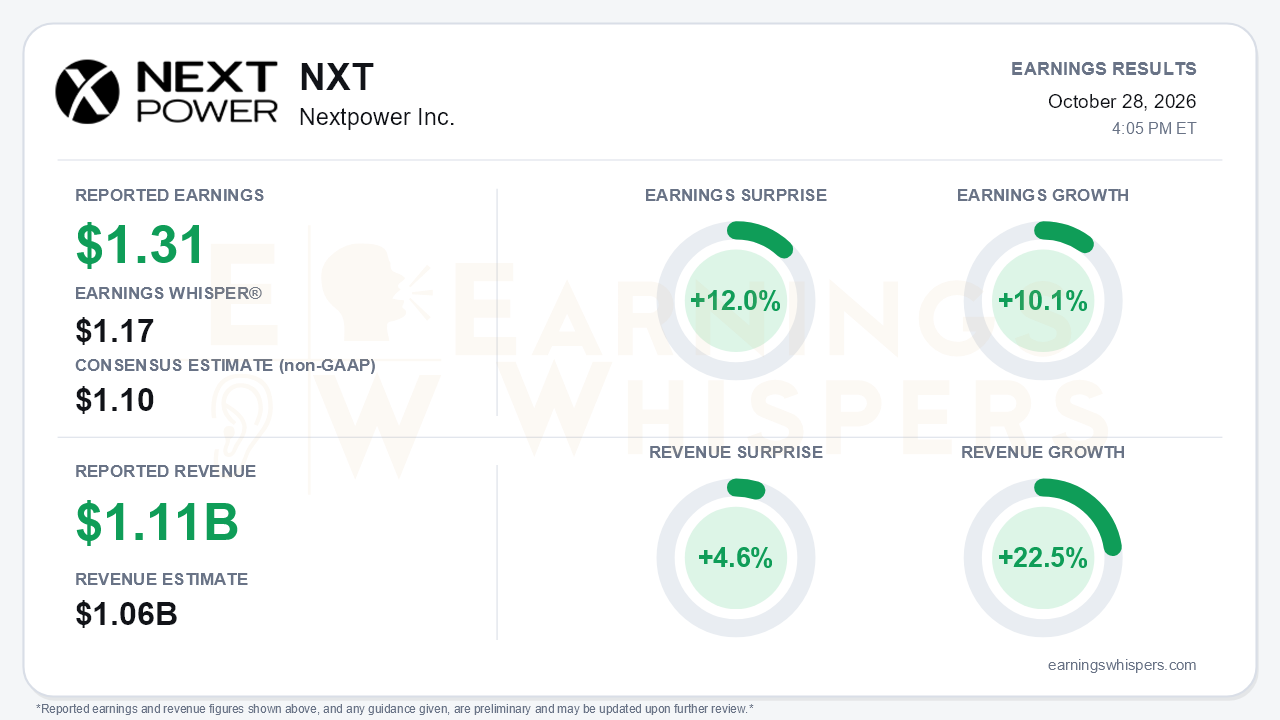
Nextpower delivered the revenue acceleration bulls wanted, but margins moved the wrong way. Adjusted earnings of $1.31 per share topped the $1.10 consensus by 12.0% and cleared the $1.17 Earnings Whisper number. Record revenue of $1.109 billion beat the $1.06 billion estimate by 4.6%. Revenue grew 22.5% year over year, a sharp step up from roughly 8% growth in the fiscal first quarter. Earnings, however, grew just 10.1%. That gap between top-line growth and bottom-line growth is the central tension of the quarter.
The quality of the beat deserves scrutiny. Adjusted gross margin fell to 32.0% from 36.6% in the prior quarter and 33.1% a year ago. Adjusted EBITDA margin slid to 22.5% from 24.9% sequentially and 24.7% a year earlier, leaving adjusted EBITDA up about 12% against 23% revenue growth. GAAP results tell a similar story. GAAP EPS of $1.08 was barely above the prior quarter's $1.07, as operating income rose but a heavier tax provision of $49.6 million (versus $33.6 million) absorbed the gain. The roughly $99 million of 45X credits, vendor rebates and tariffs, net, was flat sequentially, so the margin slippage was not a credit story. It reflected mix, investment spending and cost inflation. Cash generation held up. Quarterly adjusted free cash flow of about $135 million improved from $105 million in the first quarter, and the company ended the quarter with more than $1 billion in cash and no debt while funding acquisitions and roughly $162 million in buybacks.
The call preserved a credible growth story, and the business is visibly changing shape. Non-tracker revenue jumped to about 22% of the total, up from 14% in the first quarter and well above the roughly 15% fiscal-year target. The energy storage business contributed about $100 million in revenue and more than $20 million in adjusted EBITDA in its first quarter, including a behind-the-meter project for a Tier 1 hyperscaler AI data center. Other new businesses also gained traction:
- eBOS bookings set a record above $100 million.
- NX PowerMerge firm orders topped 2 GW, up from 850 MW last quarter.
- A 1.1 GW inverter framework agreement accompanied the first shipments of Nextpower-branded power conversion systems.
Record bookings, well above a 1x book-to-bill, lifted backlog above $6 billion from more than $5.5 billion last quarter.
The forward outlook is where bears have legitimate ammunition. Fiscal 2027 guidance was raised for a third straight time. Revenue guidance is now $4.2 to $4.45 billion, adjusted EBITDA $890 to $940 million and adjusted EPS $4.61 to $4.87, with free cash flow now expected above $500 million. But the raise was in line with estimates rather than ahead of them, and the details are less flattering:
- Third-quarter revenue is guided to roughly 10% annual growth, a sequential decline from the second-quarter record, which leaves the second half weighted toward the fourth quarter.
- Second-half margins are guided to the high-20s at the gross line and high-teens for adjusted EBITDA, well below the first quarter's 37% and 25%.
- Management flagged diesel costs up about 80% year to date, along with steel, freight and truck-driver shortages, and does not expect normalization before fiscal 2028.
- The power conversion ramp carries a roughly $50 million P&L drag plus about $40 million in capex over the next 12 months.
- Zimmermann's purchase price was cut to about €230 million after diligence, and its near-term contribution was lowered to about $100 million in revenue and $10 million in EBITDA for the rest of the year.
- Section 232 tariffs on modules and some permitting delays add further friction.
The market had already priced in a good deal of that worry. Shares closed at $79.44 ahead of the report, down 23.4% from the opening price after the July release and 25.8% below the 200-day moving average of $107.06. The stock had slid from an inter-earnings high of $108.39 in mid-August to a 52-week low of $75.41 on October 23, leaving it only 5.4% above that low entering the print. Investor sentiment nonetheless became more positive, rising from 0.14 to 0.30. Expectations improved, though they remain far from euphoric. The Earnings Whispers trend readings are split, with sequential growth and momentum positive while price and AVWAP remain negative. That split is consistent with improving fundamentals running into a stock that has been under persistent selling pressure.
The November 16 Capital Markets Day is the next major catalyst. Management indicated it will present a materially accelerated 2030 outlook. Investors will likely judge that framework less on growth ambition, which the backlog already supports, than on what margin structure the newer storage, inverter and eBOS businesses can sustain once cost inflation and ramp spending fade.
The bottom line is that Nextpower is growing faster and diversifying successfully, with record bookings, a backlog above $6 billion and a third guidance raise. That growth is coming at the cost of thinner margins, a softer third quarter and a fourth-quarter-loaded second half. With the stock trading near its 52-week low and well below its 200-day average, the market setup is more complicated than the surprise implies. The debate has shifted from whether demand is there to whether profitability can keep pace with it.
Read our earnings preview for Nextpower Inc.: https://www.earningswhispers.com/article/NXT/20970
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-19 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-07 | |
| Sep-01 | |
| Aug-31 | |
| Aug-26 | |
| Aug-26 | |
| Aug-20 |
