Corsair's Whisper Runs Ahead Of Guidance As Peripherals Strength Meets Memory-Driven DIY Slump
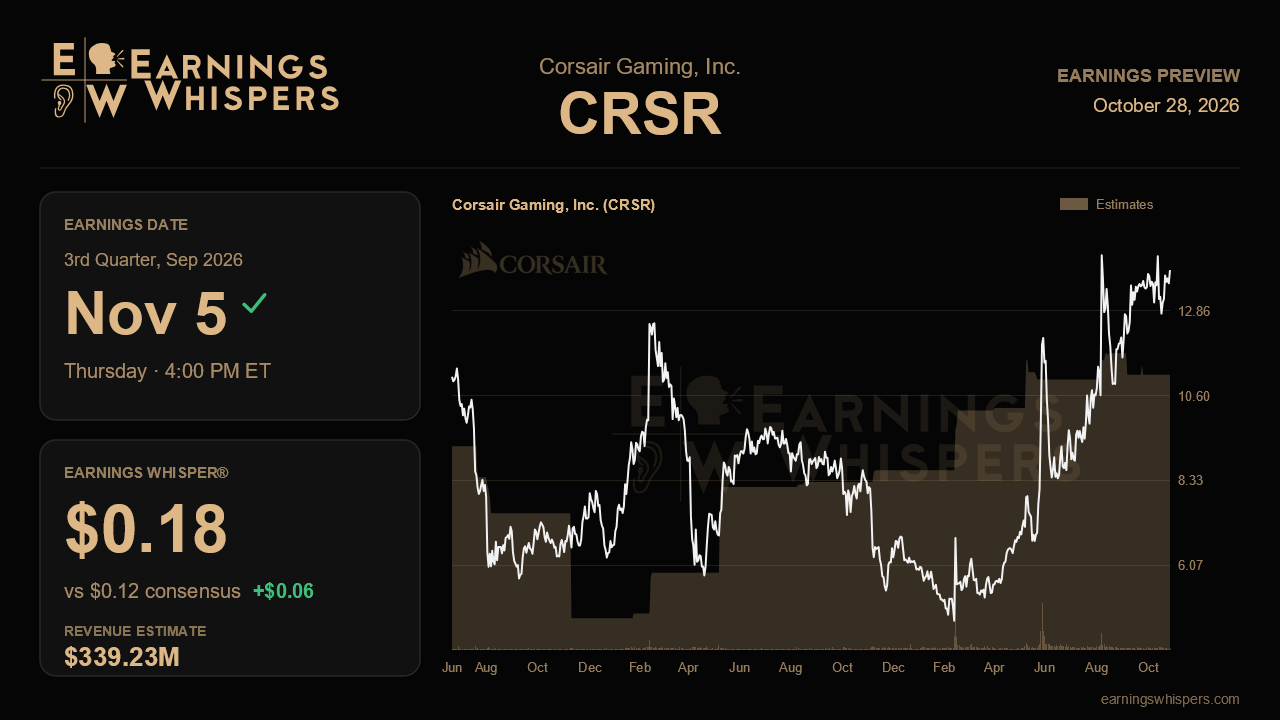
Corsair heads into its third-quarter report with an unusual expectations gap. Management guided to non-GAAP earnings of $0.09 to $0.12 a share, and the published consensus sits right at the top of that range at $0.12. The Earnings Whisper is $0.18, half again above consensus and well beyond anything the company has formally promised. That is a demanding bar for a business still digesting a sharp slowdown in its largest segment, and it means a result that merely matches guidance could land as a disappointment.
On the top line, analysts expect about $339.2 million in revenue, a decline of roughly 1.9% from $345.8 million a year ago and a bit above the $335 million midpoint of management's $320 million to $350 million range. A flat-to-down quarter is not the story here. The story is mix. Last quarter, peripherals revenue grew 13% while the gaming components and systems segment fell 9%, as elevated DRAM pricing pushed would-be PC builders to delay their projects. Management guided that segment down by low double digits again this quarter and described the demand as deferred rather than lost. A components decline in line with that guidance, paired with continued double-digit peripherals growth, would support the view that Corsair's mix is shifting in a profitable direction. A deeper components drop, or a peripherals slowdown, would undercut it.
Margins are where the real test sits. Second-quarter gross margin hit a company record 33.2%, but roughly 500 basis points came from a one-time IEEPA tariff refund that also added about $0.13 to EPS. Excluding the refund, GAAP results showed a small loss. That makes the reported $0.14 a misleading anchor for this quarter. The more useful benchmark is the year-ago $0.02, which the current consensus would beat by a wide margin. Gross margin landing around the high 20s without help from the refund would show that the expansion in peripherals margin, which reached 44.9% last quarter versus 40% a year earlier, reflects structural gains rather than a one-time accounting benefit. Management also warned that memory margins would slip from 23.4% toward the high teens by the fourth quarter, so any faster erosion would be an early warning.
The full-year guidance raised last quarter is the narrative the market has bought into. Corsair lifted its 2026 non-GAAP EPS outlook to $0.85 to $0.94 from $0.58 to $0.74, and the increase exceeded the size of the tariff refund. That excess implies management expects a genuinely stronger second half, helped by the expected GTA 6 launch in the fourth quarter. Notably, the full-year consensus of $0.72 remains below even the low end of that range, which suggests analysts have not fully accepted the raise. Reaffirming or tightening the annual outlook would carry as much weight as the quarterly print. Updates on the TrackRacer integration under Fanatec, the Bitfocus partnership, and Elgato Marketplace, where revenue and transactions more than doubled in the first half, would add color, though none is large enough yet to move the numbers.
The stock has already priced in a good deal of this. Shares are up 10% since the last report against a flat S&P 500, trade near $13.95, and sit far above the 200-day moving average of $8.89. The stock remains about 7% below its post-earnings high of $14.98, so it is not pressing a breakout. Sentiment has cooled from roughly neutral to modestly bearish, suggesting some caution after the run-up.
In the end, the report turns on one question: can Corsair show that its margin and cash-flow improvements hold up once the tariff refund is stripped out, while the memory slump stays contained? If it can, the raised annual outlook looks credible. If it cannot, last quarter's record will look more like a one-time windfall than a turning point.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Sep-17 | |
| Aug-19 | |
| Aug-06 | |
| Aug-05 | |
| Jul-31 | |
| Jul-23 | |
| Jul-23 | |
| Jul-09 | |
| Jul-07 | |
| Jun-22 | |
| Jun-02 |
