EverCommerce's First Report Under New CEO Tests Whether Pricing Can Offset EverPro Slowdown
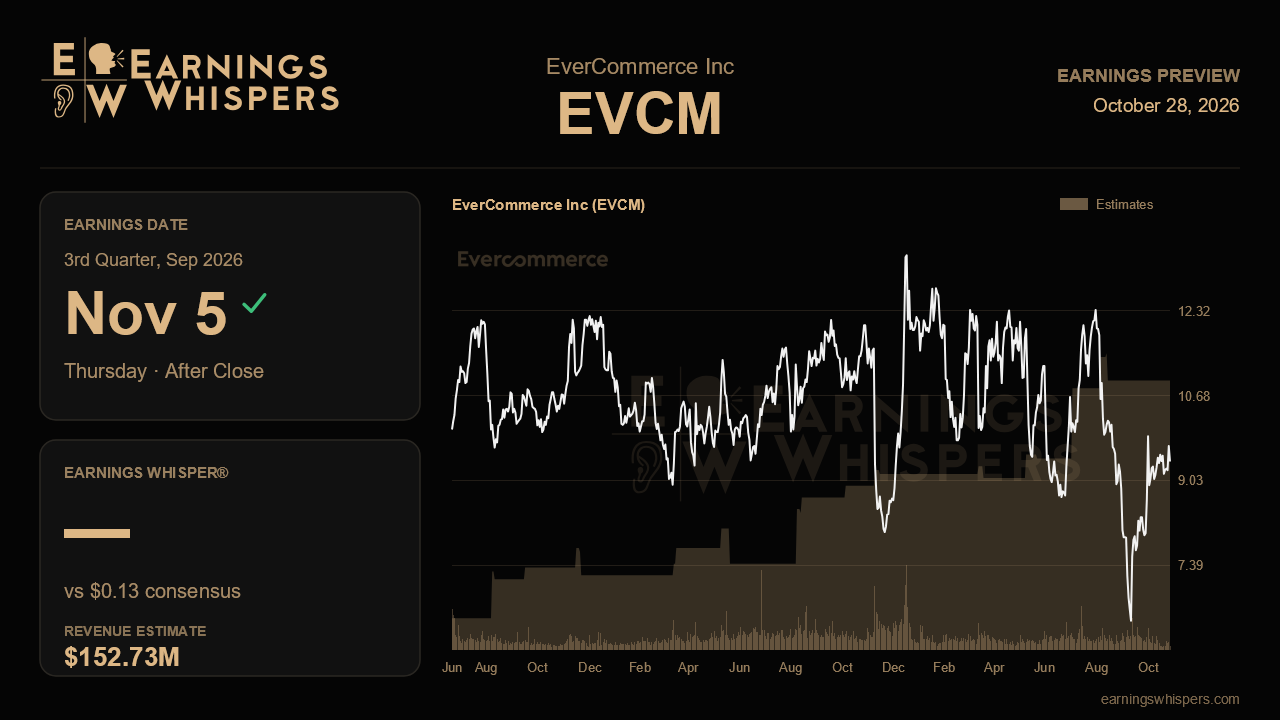
EverCommerce heads into its third-quarter report with a new chief executive, a full-year outlook already nudged toward the floor, and a stock that has lost about a fifth of its value since the last update. The quarter ending in September is the first full period with Alex Gore in the top job, and it is also the first real test of whether the second-half revenue lift management still expects can arrive through pricing when organic customer acquisition is struggling.
The Street is looking for earnings of $0.13 a share on revenue of $152.7 million. The earnings figure would be more than four times the $0.03 posted a year ago, though that comparison starts from a tiny base and says more about expense discipline than about demand. The revenue estimate tells the more important story. It implies growth of 3.6%, a modest step up from the 2.7% pace of the second quarter and roughly in line with the first quarter. That is a far cry from the reacceleration toward 5% or better for the fourth quarter that management talked up confidently earlier in the year, and it fits the company's own admission last quarter that full-year revenue would trend toward the low end of its $612 million to $632 million range, with adjusted EBITDA likewise skewing toward the bottom of $183 million to $191 million.
The culprit management identified was slower new-customer acquisition in certain EverPro home-services products, where changing search behavior driven by AI tools has cut into organic traffic. That matters because cheap inbound leads are the lifeblood of small-business software. A sequential uptick in revenue powered mostly by price increases would technically meet the plan, but it would not answer whether the top of the funnel has stabilized. Net revenue retention is a useful tell here: it slipped from 96% to 95% to 94% over the past three quarters. Another decline would suggest pricing gains are being offset by churn or downgrades, while a flat or improved reading would lend credibility to the pricing strategy. Payments deserve similar scrutiny. Growth in payments revenue from the top six solutions cooled to 8.5% from 10%, and processing volume growth slowed to 16.4% from nearly 20%. Holding those rates steady would ease fears of a broader slowdown.
Profitability has been the dependable part of the story. Second-quarter adjusted EBITDA of $44.5 million, a 29.3% margin, beat the top of guidance, and the rapid growth in customers using multiple solutions, up 26% to roughly 140,000, supports the cross-selling thesis. Another margin beat is likely to be taken for granted, however. The more consequential question is whether Gore signals changes to investment pacing or go-to-market spending. A decision to reinvest in customer acquisition could pressure near-term margins and the 2026 EBITDA range, yet could also be welcomed if it comes with a credible growth plan. Early commentary on priorities and capital allocation, with net leverage near 2.2 times and $133 million in cash, may move the stock as much as the quarterly numbers.
Sentiment remains firmly bearish, though somewhat less so than heading into the last report, and the shares at $9.40 sit below their 200-day moving average of $10.39. The stock has bounced well off its post-earnings low of $6.21 but remains comfortably beneath the $12.11 high, leaving room for either a relief rally or a retest of the lows.
Ultimately, the report hinges on whether EverCommerce can show that the low end of its guidance is a floor rather than a waypoint. Revenue near 3.6% growth with stable retention and payments trends would validate the pricing-led plan; another leg down in retention or an outright cut to the range would confirm that the EverPro acquisition problem is deeper than management has acknowledged.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-15 | |
| Sep-21 | |
| Sep-11 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-20 | |
| May-07 | |
| May-07 | |
| May-06 | |
| Apr-17 | |
| Mar-27 | |
| Mar-13 |
