EGain's AI Growth Faces Its First Test Against Accelerating Legacy Runoff
eGain enters its fiscal first-quarter report with two stories pulling in opposite directions. Its AI franchise is growing at a double-digit clip and recently earned a Leader position in Gartner's first Magic Quadrant for customer service knowledge management. Yet management has guided total revenue lower for fiscal 2027, because older products are shrinking faster than the AI business can replace them. The September quarter is the first real read on whether that tradeoff is unfolding as planned or getting worse.
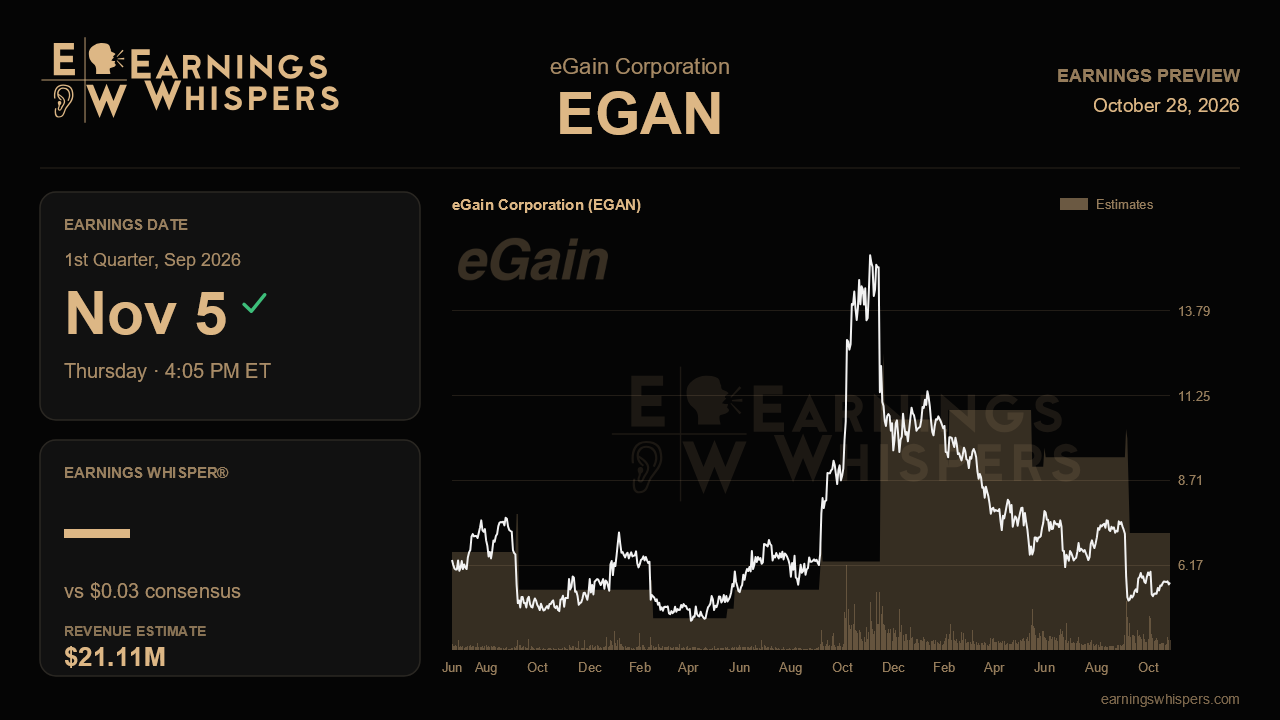
The Street is braced for contraction. Consensus calls for revenue of about $21.1 million, down roughly 10% from $23.5 million a year ago, and earnings of $0.03 per share against $0.15 in the prior-year quarter. The revenue estimate sits near the middle of management's $20.9 million to $21.4 million range, so a modest beat or miss on the top line will not mean much by itself. Earnings are less clear. Management guided non-GAAP EPS of $0.05 to $0.08, and the $0.03 consensus is below that range, which suggests either a different accounting basis or real skepticism about costs. The full-year EPS outlook of $0.04 to $0.07 is roughly what the company expects to earn in the first quarter alone. That points to heavier go-to-market spending later in the year, so a strong Q1 profit figure should be read with that in mind.
The biggest question is legacy runoff. Last quarter, management said fiscal 2027 assumes roughly a 20% revenue decline and a 60% ARR decline in the non-AI business, a steeper drop than the messaging sunset it had flagged earlier. Total SaaS ARR slipped 1% year over year after three quarters of 7% growth. Remaining performance obligations fell 5%, a reversal from double-digit gains earlier in the year. If ARR and RPO stabilize, the guide was conservative and the decline is contained. Further deterioration would suggest the runoff has momentum the forecast did not capture.
On the growth side, the AI cohort must keep compounding. AI customer ARR grew 13% and now makes up 72% of total SaaS ARR, and management's fiscal 2030 model calls for $100 million to $120 million of AI ARR. Getting there requires something closer to 20% annual growth, so a pickup in that rate would strengthen the long-term case. Net retention also matters. AI retention fell to 104% from 116%, partly because the company was lapping a large JPMC expansion, and all-customer retention dropped to 93%. A rebound would support management's argument that the dip was a one-time comparison effect. Investors should also look for progress on the eight paid pilots signed last quarter with Global 2000 accounts. A conversion to full production would offer the clearest proof that the record pipeline, including a doubling in $500,000-plus opportunities, is turning into revenue.
The stock has edged up about 3% since the last report while the S&P 500 was flat, but that small gain hides a reset. Shares trade around $5.65, well below the 200-day moving average near $7.54. The post-earnings range of $5.02 to $6.07 sits almost entirely below the prior quarter's $5.94 to $7.86 band. Sentiment leans bearish, and the report follows October's investor day, where the multiyear model had its public airing. Expectations are low, but so is the market's patience.
In the end, this report comes down to which trend is winning. If AI growth accelerates while legacy declines stay within the guided path, the reduced outlook starts to look like a deliberate reset with a floor beneath it. If total ARR, RPO, or retention weakens again, the market is likely to conclude that the runoff is still outrunning the growth engine, and the fiscal 2030 targets will be harder to believe.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-26 | |
| Oct-13 | |
| Oct-13 | |
| Oct-08 | |
| Oct-08 | |
| Sep-29 | |
| Sep-04 | |
| Sep-04 | |
| Sep-03 | |
| Sep-03 | |
| Aug-25 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 |
