Devon Faces A Proof Test On Cotera Synergies And Its Portfolio Review
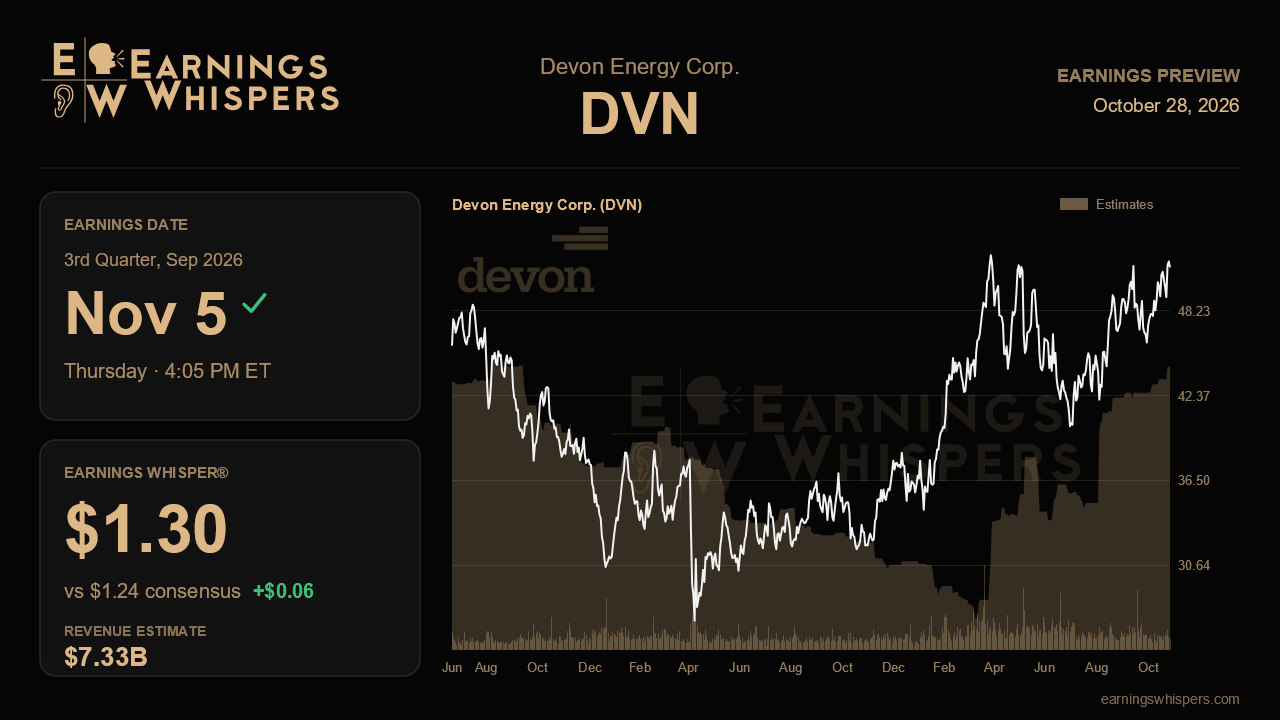
Devon Energy heads into its third-quarter report with a stock that has finally started to behave the way management said it should. After openly conceding in August that shares had lagged their new large-cap peers since the Cotera merger closed, Devon has rallied 17% since that call while the S&P 500 slipped slightly. That turns the November 5 release, due after the close, into less of a rescue mission and more of a test of whether the combined company can keep delivering numbers that justify a rerating already underway.
The Street expects earnings of $1.24 a share on revenue of $7.33 billion. The revenue figure would be up about 69% from a year ago, a jump that reflects the Cotera combination rather than any surge in organic demand. Earnings growth of roughly 19% is far more modest, and the consensus implies a sizable sequential drop from the $1.57 Devon earned last quarter on nearly identical revenue. In other words, analysts are not assuming the second-quarter profitability carries over cleanly. The Earnings Whisper of $1.30 sits modestly above consensus, suggesting some investors think that sequential decline is too conservative. With revenue expected to be roughly flat with last quarter, any upside likely has to come from costs and execution rather than volume.
That puts the operating details from the last call at the center of the story. Devon beat on every guided metric in the second quarter: oil output of 503,000 barrels a day, total production at the top of its range, operating costs of $8.23 per barrel of oil equivalent and capital spending below plan. It also tightened full-year oil guidance to 495,000 to 505,000 barrels a day. Because this is the first quarter with Cotera contributing for all three months, it offers a cleaner read on the combined run rate. Oil volumes holding near the top of that range, unit costs staying around last quarter's level and Delaware drilling and completion costs remaining near $800 per foot would validate the claim that the merger is producing efficiencies ahead of schedule. Slippage on any of those would make the second quarter look like a high-water mark.
Synergies are the bigger narrative. Management said it had identified more than 350 initiatives supporting its $1 billion annual target, up from 156 a quarter earlier, and described itself as more confident than at announcement. Investors should want that confidence translated into dollars captured, not just ideas catalogued. Capital returns deserve similar scrutiny: the dividend was lifted 33% to $0.32, an $8 billion buyback launched, and the 2026 debt target was already met. The pace of repurchases this quarter, and whether free cash flow approaches last quarter's $1.7 billion, will show how durable that payout story is. Gas realizations remain a swing factor given persistent Waha takeaway constraints.
The wild card is the portfolio review, with an update promised for the fall. If details arrive with this report, the market will weigh which assets are on the block, how much tax leakage on low-basis properties dents proceeds, and whether the remaining mix looks more focused. Sentiment has warmed, rising to 21% bullish from 14% before the last report, and the stock at $51.23 sits well above its 200-day average and within about 1.5% of its post-earnings high of $51.97, testing a breakout.
That elevated positioning raises the bar. Devon does not need a dramatic beat so much as evidence that the combined company's cost structure, synergy capture and cash generation are repeatable, paired with portfolio clarity that removes the overhang management itself identified. Deliver both, and the rerating has room to run. Stumble on either, and a stock pressing against its highs has little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-23 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Oct-04 |
These Energy Companies Put Oklahoma City on the Map. Now They're Moving to Texas.
DVN
The Wall Street Journal
|
| Sep-28 | |
| Sep-23 |
