JFrog's Cautious Third-Quarter Guide Puts Cloud Usage And AI-Lab Momentum To The Test
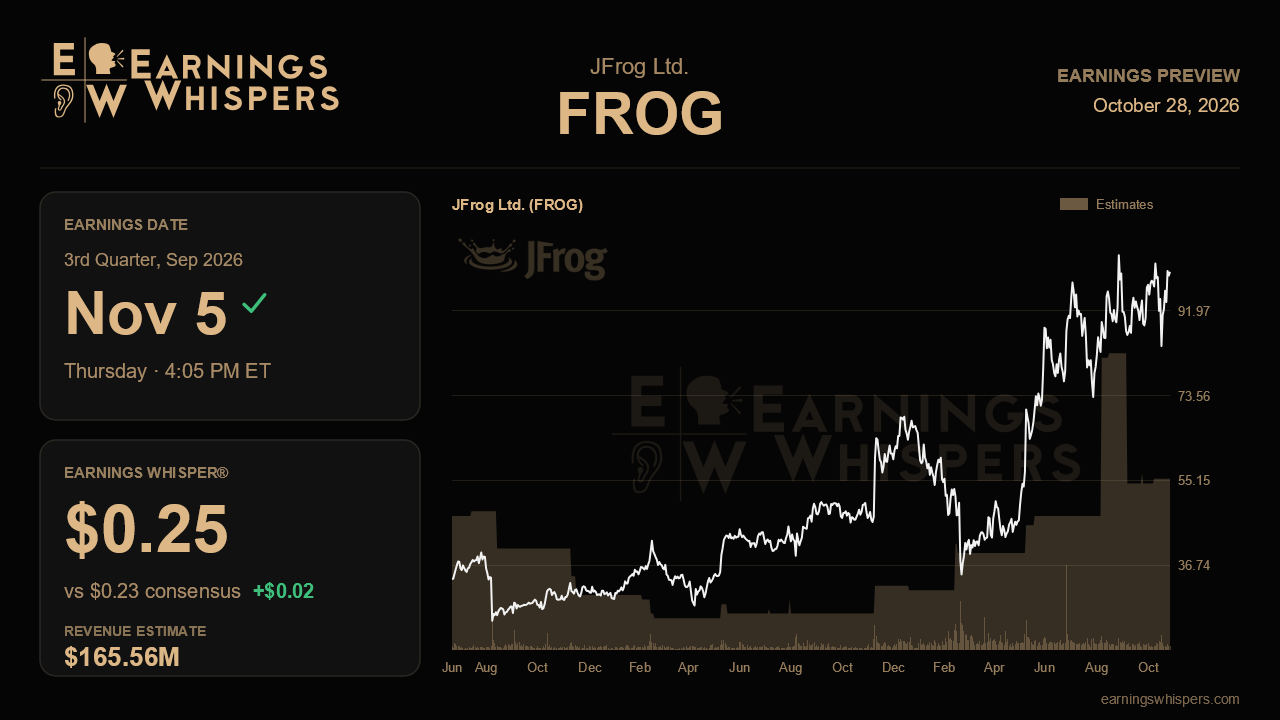
JFrog heads into its third-quarter report with a puzzle built into its own guidance. Revenue grew 29% last quarter, cloud sales accelerated past 50%, and management raised its full-year outlook for the second straight time. Yet the forecast for the September quarter implies growth of roughly 21%, along with almost no sequential increase from the $163.8 million posted in the second quarter. Either the business is about to downshift abruptly, or management is once again leaving plenty of room to outperform. The report due after the close on November 5 should show which explanation fits.
The Street has settled squarely on management's numbers. Consensus calls for non-GAAP earnings of $0.23 per share on revenue of $165.6 million, right at the midpoint of the company's guidance of $0.22 to $0.24 and $164 million to $166 million. The Earnings Whisper of $0.25 sits above the top of that range. That is a modest gap in absolute terms, but it suggests the informal bar is a clean beat, not merely a matching of guidance. Against last year's $136.9 million, the consensus revenue figure represents solid growth of about 21%, which would still be a deceleration from the pace of recent quarters if it came in exactly as modeled.
The explanation for the gap lies in how JFrog builds its outlook. Management excludes cloud usage above customers' contracted commitments, and that overage has become a large share of recent cloud upside. The guidance therefore functions as a floor, while actual results depend heavily on whether consumption stays elevated. The same mechanism is also the main source of risk. Overage usage is less predictable than committed spending, and management flagged growing CFO scrutiny of AI-driven token budgets as something that could eventually temper consumption. If cloud growth holds near last quarter's 53% pace, or if overages begin turning into larger annual commitments, the bullish story stays intact. A sharp slowdown toward the raised baseline cloud growth target of 41% to 43% would suggest the usage surge is cooling.
The forward-looking indicators may matter even more than the headline beat. Remaining performance obligations jumped 38% to $659 million last quarter, helped by a record sequential gain, and security products were attached to most new seven-figure customers. Another strong RPO increase, continued growth in the count of customers paying more than $1 million beyond last quarter's 97, and net dollar retention holding at or above the newly raised 120% floor would all confirm that security and governance are becoming durable growth drivers. Early evidence of revenue from the Anthropic and Cursor integrations, the fourth foundational AI-lab customer, and the DevGovOps offering would help show that last quarter's new catalysts are real and not just press releases. The self-hosted business is the weak spot to watch. It still accounts for nearly half of revenue but grew only 9%, and the zero-day vulnerability discovered there raises the question of whether customers migrate to the cloud or simply reconsider spending.
Sentiment has improved from modestly bearish before the last report to mildly bullish now, and the stock has risen 4.4% since then while the S&P 500 was flat. At about $100, shares trade far above their 200-day moving average near $71 and sit in the upper part of their post-earnings range, roughly 5% below the $105.76 high. That is a market leaning optimistic without being euphoric. Even so, two consecutive raises have taught investors to expect a third.
The real issue is whether JFrog can deliver another full-year increase built on cloud consumption and security attach rather than one-time usage spikes. Results near the top of guidance, firm cloud growth and another sizable RPO gain would extend the acceleration story. Results that merely match the conservative guidance would leave the stock exposed to the possibility that its best growth is already behind it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-21 | |
| Oct-14 | |
| Sep-18 | |
| Sep-02 | |
| Sep-02 | |
| Sep-02 | |
| Sep-02 | |
| Aug-31 | |
| Aug-31 |
Oil Names Mix With AI Stocks On Elite Screen As Three Trade Near Buy Points
FROG
Investor's Business Daily
|
| Aug-27 | |
| Aug-26 | |
| Aug-24 |
