Health Catalyst's Debt-Free Reset Meets Its First Real Test As Migration Churn Lingers
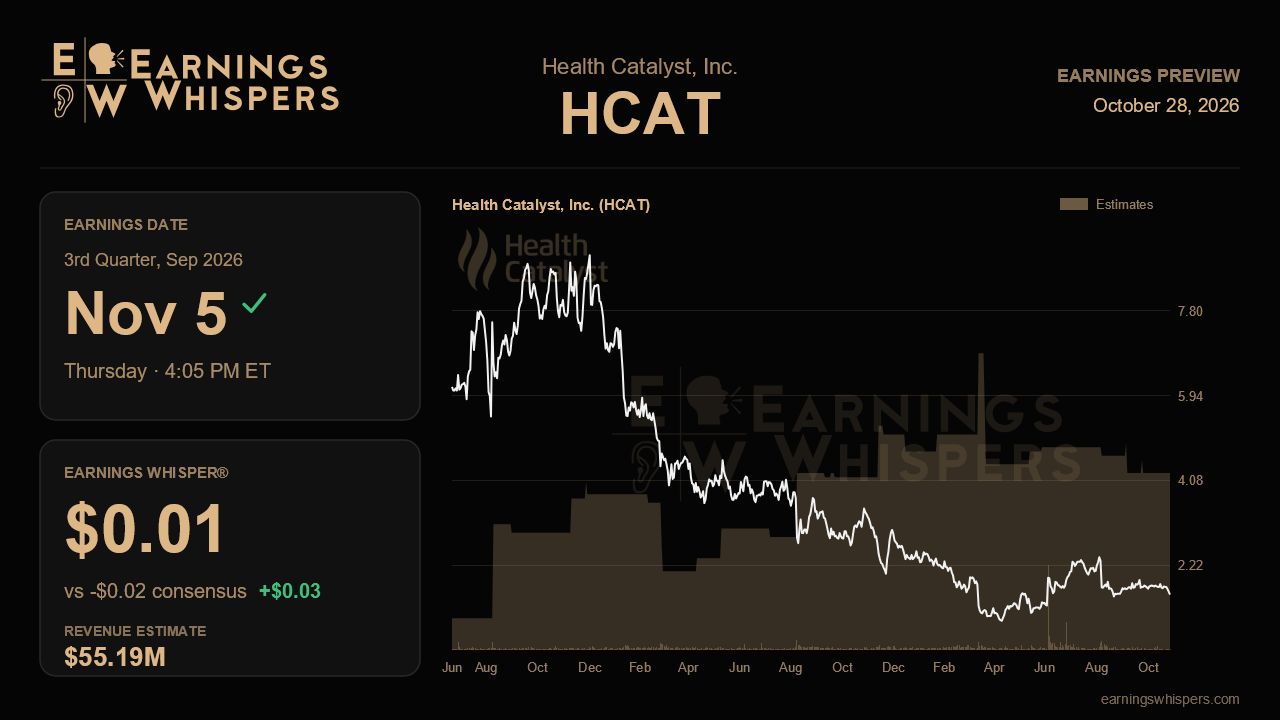
Health Catalyst enters its third-quarter report with a cleaner balance sheet than it has had in years and a shrinking business that still has not found its floor. The sale of VitalWare and the payoff of roughly $160 million in debt removed the financial overhang, but management also cut its full-year outlook last quarter and admitted that customer churn tied to its platform migration was not getting better. The release after the close on November 5 is the first to reflect the company in its smaller, debt-free form, and investors need to learn whether what remains can stabilize.
The Street expects revenue of $55.2 million, a 27.7% drop from the $76.3 million posted a year ago and a steep slide from the $70.5 million reported last quarter. Much of that decline comes from removing VitalWare, but not all of it. Management guided to $55 million to $56 million, so consensus sits near the low end of the range after analysts cut their quarterly estimate from about $62.5 million. Full-year guidance now stands at $246 million to $249 million, down from $260 million to $265 million. On earnings, consensus calls for a non-GAAP loss of 2 cents a share, while the whisper number sits at a profit of 1 cent. The gap is small in dollars, but it suggests some traders expect the absence of about $16.5 million in annual cash interest to show up quickly in the bottom line. That is reasonable, since adjusted EBITDA guidance of break-even to $0.5 million leaves little operating cushion.
The central issue is the shift of clients from the legacy DOS platform to Ignite. Last quarter management laid out $12.5 million of churn customers had already announced plus about $52 million of revenue it considered at risk, of which it expected to keep only around $22 million. Leaders said they had hoped to improve those numbers but were still seeing significant pressure, and some churn, along with related services revenue, was arriving sooner than planned. Holding those figures steady would be a modest win. Any increase in announced churn or lower retention expectations would show that the problem is spreading. Investors should also look for specific Ignite renewals or expansions, because talk of AI improvement agents built on the company's proprietary data means little until it shows up in retained revenue.
Margins are the second test. Management trimmed its technology gross margin outlook to the low 60s from the mid-60s and said full-year adjusted gross margin would fall below 50%. Services are expected to exit the year near the low end of their range, about $55 million annually, as clients bring managed services work back in house. In its favor, services gross margin improved to 22% from 18% a year earlier, and Project Nexus is on track to beat its original target of about $30 million in annualized savings, although net savings were guided toward the lower end. If technology margins hold steady and Nexus savings show up clearly in operating expenses, the reinvestment story becomes believable. Further margin erosion would point to price pressure from platform rivals rather than a temporary effect of the divestiture.
Sentiment has swung sharply, from 26% bearish before the last report to 63.2% bullish now, yet the stock has not followed. Shares have fallen 15.6% since the last report while the S&P 500 was roughly flat. At $1.57, the stock trades below its 200-day moving average of $1.73 and only a few cents above its post-earnings low of $1.53. The trading range has narrowed considerably from the previous quarter's swing between $1.12 and $2.40, which suggests the market is waiting for proof before picking a direction.
For the turnaround story to hold, Health Catalyst does not need to beat expectations by much. It needs to show that churn has stopped worsening and that the debt-free company can earn its way toward break-even. A clean quarter with stable migration numbers would support management's view that headwinds will fade by the end of 2027. Another increase in at-risk revenue would leave investors with a strong balance sheet and a shrinking business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Sep-14 | |
| Sep-14 | |
| Sep-10 | |
| Sep-08 | |
| Aug-31 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-28 | |
| Jun-16 | |
| Jun-04 | |
| Jun-04 | |
| May-12 |
