Guardian Pharmacy's Q3 Test: Can Margins Keep Beating A Shrinking IRA-Hit Top Line?
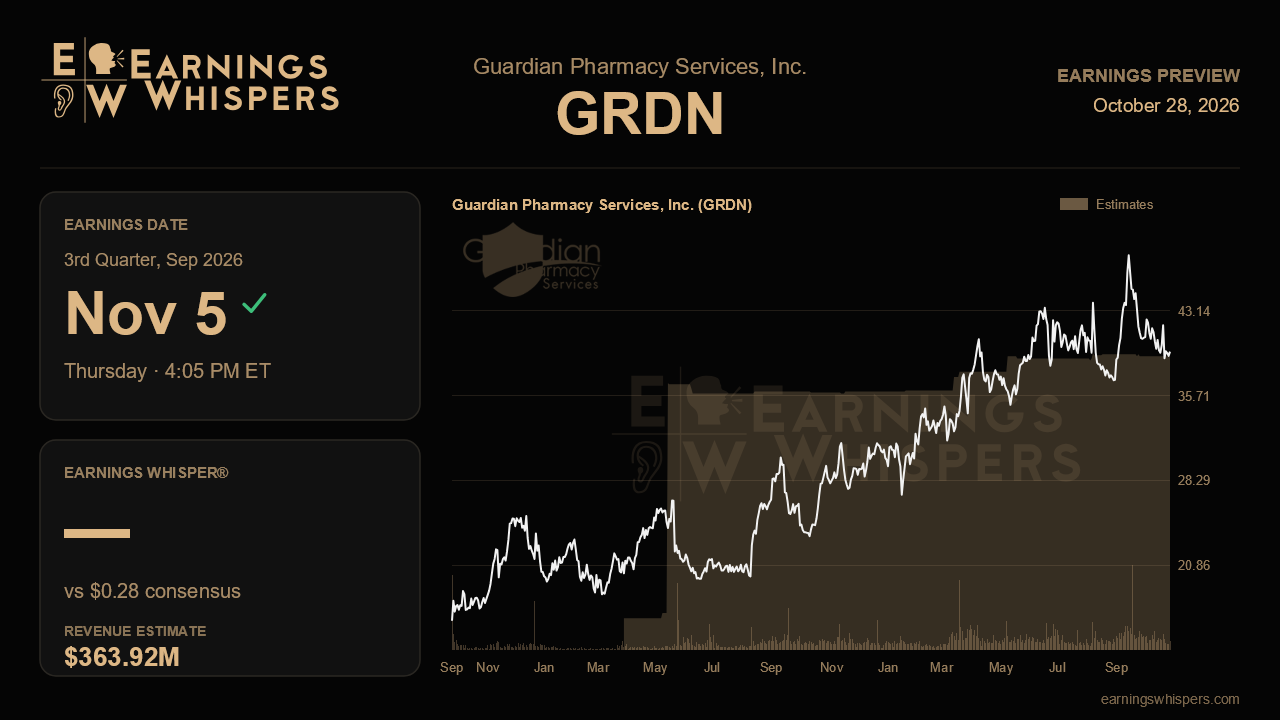
Guardian Pharmacy Services heads into its third-quarter report with an unusual setup: the company is expected to post sharply higher earnings on revenue that is actually shrinking. That gap is the whole story. Federal drug price cuts under the Inflation Reduction Act have stripped dollars out of the top line, while underlying demand and profitability keep improving. The report should show whether that divergence can hold now that management has raised its outlook and the stock has drifted lower anyway.
The Street is looking for earnings of $0.28 a share, up about 47% from $0.19 a year ago, on revenue of roughly $363.9 million, down about 3.6% from $377.4 million. A decline of that size is no surprise. Last quarter management said second-half reported revenue would fall by a low single-digit percentage year over year as the IRA's roughly 60% price cuts on affected branded drugs work through the comparisons. A modest sequential gain from the second quarter's $351.8 million would fit that script. The more interesting tension sits in the annual numbers. Management raised its 2026 revenue forecast to $1.43 billion to $1.45 billion, yet consensus for the year is about $1.41 billion, below even the low end of the new range. Analysts are either skeptical of the raise or have not fully updated their models, which leaves room for a revenue print that clears a modest bar.
The raise to adjusted EBITDA guidance, now $129 million to $131 million from $123 million to $127 million, is the claim that most needs supporting evidence. First-half adjusted EBITDA grew 23%, and second-quarter gross margin rose to 22.8% from 22.7% in the first quarter. The drag from newer acquisitions and greenfield pharmacies narrowed to about 60 basis points from 80 as the 2024 and 2025 cohorts matured. A further step down in that drag, along with stable or rising gross margin, would confirm that operating leverage is real and not a one-quarter event. Margin slippage, especially if management again blames fuel costs, would undercut the case for the higher EBITDA range.
Demand is the other part of the story worth checking. Residents served topped 210,000 last quarter, up high single digits, with prescription volumes growing at a similar pace. Continued growth in both would show that the revenue decline really is about pricing and not about volume. Investors should also want early updates on the newer catalysts: the Wellness Concepts tuck-in in Virginia, the first Kentucky greenfield in Lexington, the expanding Falls Risk clinical program, and any progress on deploying cash, which reached about $90 million, toward possible Omnicare asset sales. Any refinement of the 2027 IRA tranche, which management now sizes at roughly 40% of this year's impact instead of about half, could matter more for the stock than the quarter itself.
The market has not rewarded last quarter's upbeat tone. Shares are down about 8% since the prior report while the S&P 500 was roughly flat. Some of that likely reflects the supply overhang from the late-September conversion of about 13.5 million Class B shares, plus a large block of insider-held stock. At $39.56, the stock sits above its 200-day moving average of $37.90 but in the lower half of its post-earnings range of $35.90 to $48.33. Sentiment has improved noticeably, to about 34% bullish from 8% ahead of the last report, so expectations are warmer, though hardly euphoric.
The central question is simple. Can Guardian keep turning a contracting revenue line into rising profit while volumes keep growing? If margins improve again and management holds or nudges up its guidance, the recent selloff looks more like a supply problem than a skeptical verdict on the business. If the margin gains stall, the falling top line will become much harder to treat as merely cosmetic.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-21 | |
| Sep-01 | |
| Aug-19 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-15 | |
| Jul-01 | |
| Jun-22 | |
| May-06 | |
| May-06 | |
| Apr-23 | |
| Apr-14 |
