Howard Hughes Faces First Full Vantage Quarter As Insurance Margins Take Center Stage
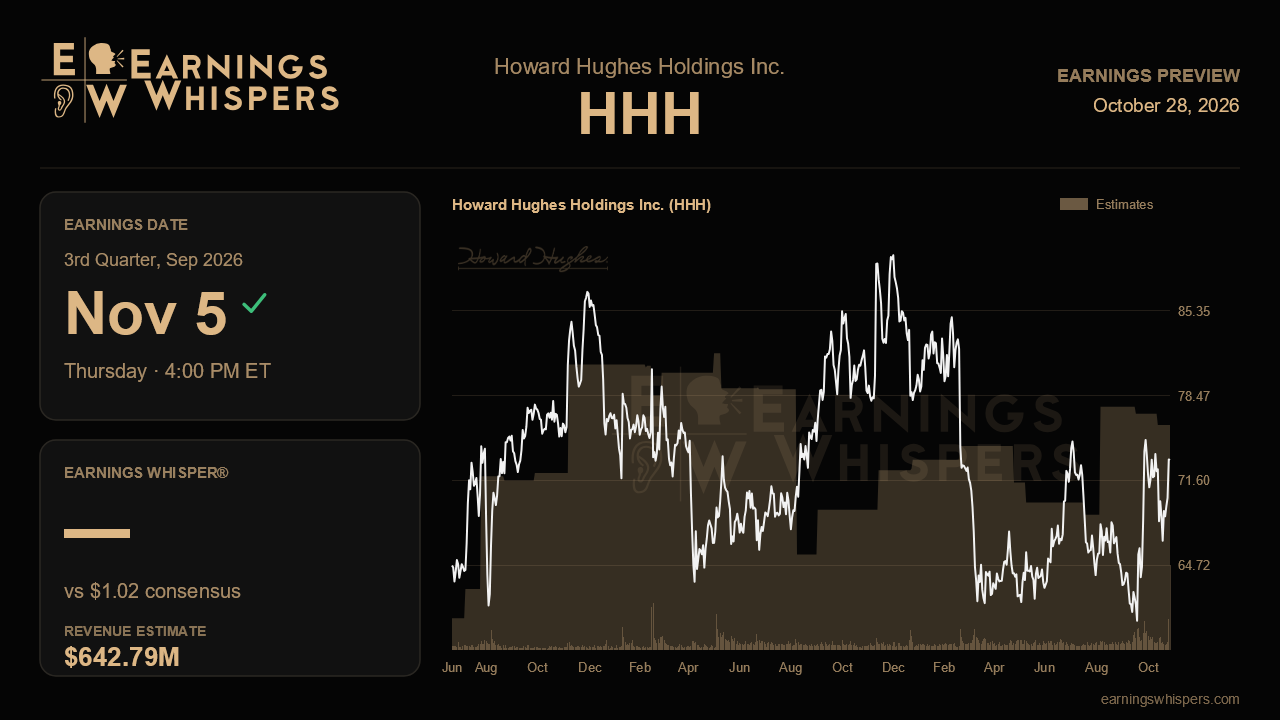
Howard Hughes Holdings enters its third-quarter report on November 5 as a different company from the one that reported a year ago. This will be the first full quarter with Vantage, the specialty insurer that closed on June 4, consolidated into results. That makes it the first clean look at whether the insurance pivot can deliver steady earnings alongside a real estate business that has been compounding cash. The answer will matter more than the headline numbers.
The Street's figures show the shift. Analysts expect revenue of about $642.8 million, up 64.7% from $390.2 million a year ago, a jump that mostly reflects insurance premiums now flowing through the top line. Earnings are expected to move the other way. Consensus calls for $1.02 per share, roughly half the $2.02 earned in the year-ago quarter and far below the $2.68 posted last quarter. That prior result was flattered by the Park Ward Village condo closing, which generated about $227 million in net proceeds. Condo deliveries at Ward Village are lumpy, so a quarter without a comparable tower closing will naturally look thinner. Management withdrew formal annual guidance earlier in the year because of the Vantage deal, so there is no company target to measure the consensus against. Investors will have to judge the quarter on its operating details.
The insurance underwriting line is the key test. Vantage's headline combined ratio was 101.6% last quarter, meaning it paid out slightly more in losses and expenses than it collected in premiums. Management attributed roughly 10 points of that to $18 million in catastrophe losses tied to the Iran conflict and $19 million of adverse prior-year development in transactional liability. Strip those out and the current accident-year ratio excluding catastrophes improved to 91.4% from 96.2% a year earlier. A third-quarter combined ratio back comfortably below 100%, with little or no further reserve strengthening, would support the view that last quarter's damage was one-off. Another round of adverse development would raise harder questions about the book Howard Hughes acquired. Investors should also look for any pricing commentary. Management acknowledged that some property and casualty lines are entering a softer phase, with lower rates and more competition, which could squeeze underwriting margins even if losses behave.
The investment portfolio is a newer swing factor. Pershing Square added $300 million of capital and the $3.4 billion portfolio was rebuilt from all fixed income into a barbell of roughly 60% short-term Treasuries and 40% equities. That mix offers more upside over time but adds mark-to-market volatility to reported earnings. The portfolio was down about 3% heading into the last quarter-end. Equity swings could move the reported figure against the consensus in either direction for reasons unrelated to operations.
Real estate is meant to be the steady part of the story. Master planned community earnings before taxes rose 32% last quarter to $134.7 million, and new home sales gained 12%, led by The Woodland Hills and Bridgeland. Continued strength in land sales and homebuilder demand would show the core business can keep funding growth. The same goes for progress on the condo pipeline, which carries more than $4 billion of future revenue and is about 78% presold. Updates on joint ventures and asset sales aimed at raising capital for Vantage also matter. One soft spot to watch is operating-asset cash flow, which slipped on leasing costs and higher interest expense.
The market has grown more comfortable. Shares are up 7.6% since the last report while the S&P 500 was flat. At $73.25 the stock sits above its 200-day average and within about 2% of its post-earnings high of $75.01, so it is approaching a breakout. Sentiment remains bearish, but less so than before the prior report. The rally suggests investors are giving the insurance strategy the benefit of the doubt. The report will show whether that trust is earned. If Vantage's underwriting margin normalizes without new reserve surprises, the transformation narrative holds. If it doesn't, the softer-looking quarter could start to look like a trend rather than a timing issue.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-26 | |
| Oct-23 | |
| Oct-12 | |
| Sep-25 | |
| Sep-25 | |
| Sep-08 | |
| Aug-20 | |
| Aug-12 | |
| Aug-11 | |
| Aug-06 | |
| Aug-05 | |
| Jul-16 | |
| Jul-07 | |
| Jun-04 |
